
Howmet Aerospace (HWM) Could Be 28% Below Fair Value After 2026 Guidance Lift
Howmet Aerospace (HWM) put fresh numbers behind its confidence as management lifted full-year 2026 guidance and outlined expected revenue growth into 2027, supported by commercial aerospace demand and expanding profitability.
Recent trading tells a mixed story. The share price is up 7.29% over the past week and 4.30% year to date, yet the 90 day share price return is down 23.64%. At the same time, the 3 year total shareholder return of very roughly 3x signals stronger longer term momentum that recent guidance and the buyback program are helping to reframe for investors.
Scan for other aerospace and capital-goods stocks showing a similar mix of guidance lifts, buybacks, and analyst support by using our curated 32 high quality undervalued stocks as a starting point.
Howmet Aerospace now pairs a long runway in commercial aviation with fresh guidance and a sizeable buyback. The real test for investors is whether that strength is already fully reflected in the current share price.
Most Popular Narrative: 28% Undervalued
Against the last close of $220.82, the analyst consensus Narrative on Simply Wall St points to a fair value of $306.75 for Howmet Aerospace. This frames the current setup as meaningfully undervalued and anchored in detailed earnings and cash flow forecasts.
The record high commercial aircraft backlog and accelerating global air travel, especially in Asia Pacific and Europe, are fueling increased production rates such as 737 MAX and A320. This continues to support higher revenue visibility and potential earnings growth for Howmet Aerospace as those build rates flow through its content per aircraft.
See why 94 investors see Howmet Aerospace as 28% undervalued.
Result: Fair Value of $306.75 (UNDERVALUED)
Still, the Howmet Aerospace narrative could shift quickly if market sentiment cuts the P/E multiple or if industrial gas turbine and spares demand proves less resilient.
Find out about the key risks to this Howmet Aerospace narrative.
Another View: Howmet Aerospace Through The P/E Lens
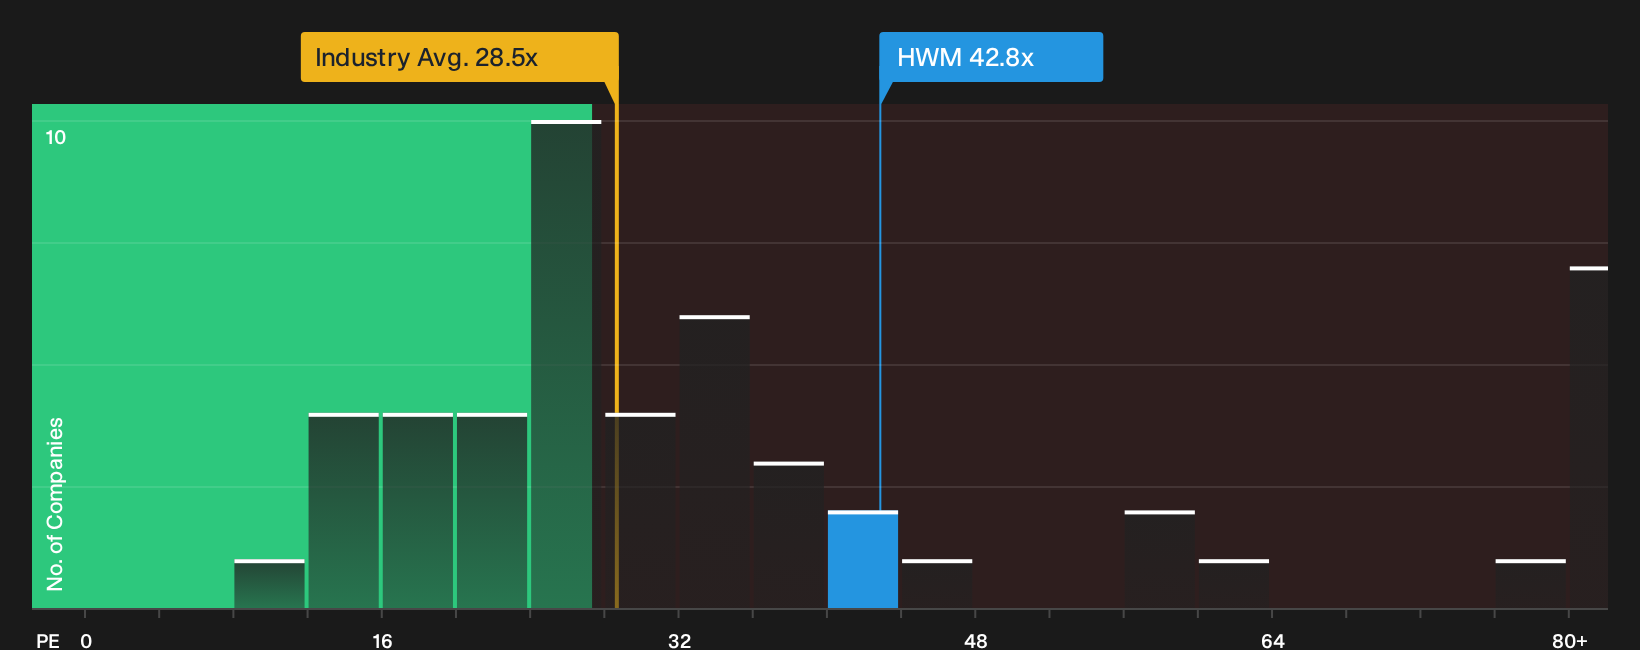
There is a very different message once you look at Howmet Aerospace through its current P/E. The shares trade at about 42.8x earnings, compared with a fair ratio of 32.7x, the US Aerospace & Defense sector at 28.5x, and peer averages around 24.2x. That kind of premium can signal confidence in future delivery, or it can leave little room for disappointment if earnings or sentiment soften.
For investors weighing those trade offs, it is worth stress testing what would need to go right for the valuation premium to remain intact over time. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals or a clear skew toward optimism around Howmet Aerospace? The only way to know is to pressure test the numbers yourself and weigh both sides quickly. To see the balance of concerns and potential upside set out in one place, review the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Howmet Aerospace?
If Howmet Aerospace has sharpened your focus on valuation and quality, do not stop here. Fresh opportunities often sit just outside your current watchlist.
- Target dependable income by scanning companies with robust payouts and balance sheets using our hand picked 6 dividend fortresses.
- Hunt for quality at a discount as you work through the curated 20 high quality undiscovered gems that many investors may not be watching yet.
- Prioritise resilience and capital protection by filtering candidates through the 31 resilient stocks with low risk scores that highlights businesses with sturdier risk profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com