
What MKS (MKSI)'s Strong Earnings Outlook Means For Shareholders
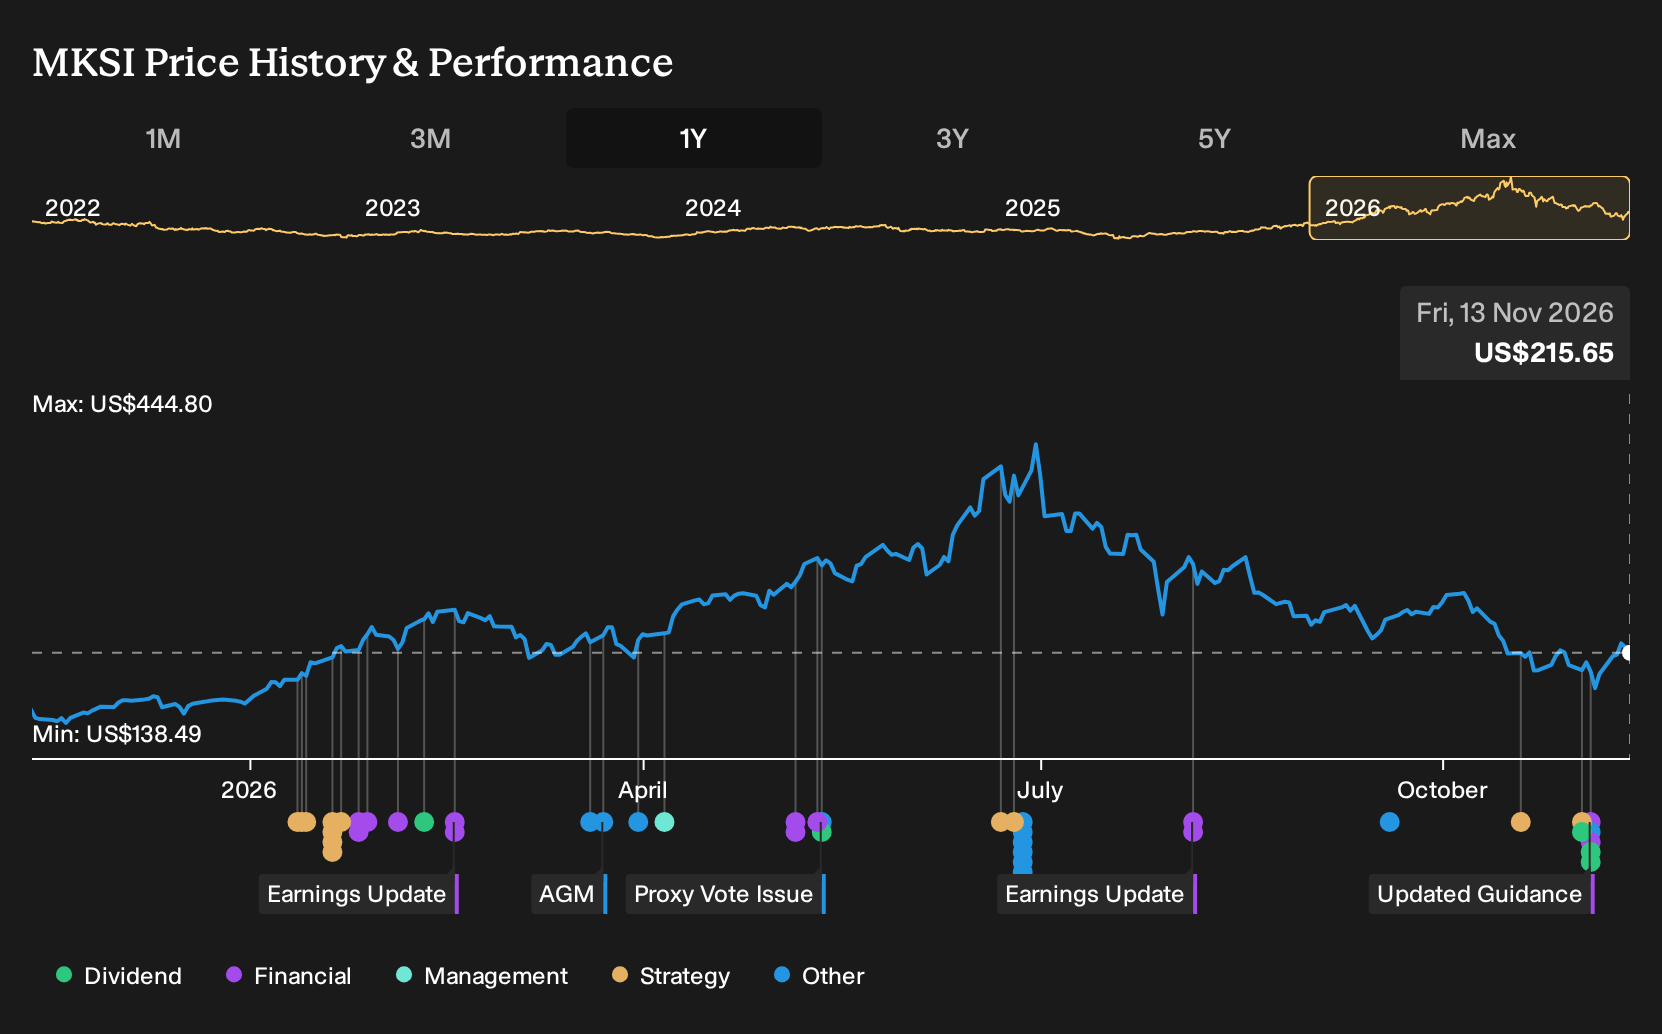
- MKS Inc. reported third quarter 2026 revenue of US$1,413 million and net income of US$236 million, alongside fourth quarter guidance that includes expected GAAP net income of US$294 million and diluted EPS of US$4.04, plus or minus US$0.38.
- The board paired these results with a US$0.25 quarterly dividend and a new US$500 million share repurchase authorization, reflecting actions on capital returns while the Guangzhou expansion and other ongoing investments continue.
- We will now look at how MKS Inc.'s third quarter earnings and fourth quarter guidance could influence its investment narrative.
MKS Investment Narrative Recap
For MKS, the big picture investors need to buy into is that AI driven chip complexity and electronics demand continue to support semiconductor and electronics equipment orders, while new capacity in places like Malaysia and Guangzhou ramps efficiently. The latest quarter, with US$1,413 million in revenue and US$236 million in net income, aligns with that operating story.
The key near term catalyst is execution on that expansion while keeping margins in line with guidance. The biggest risk remains a pullback or pause in wafer fab and electronics spending that would expose how sensitive MKS is to a lumpy capex cycle. Recent news does not remove that risk.
The announcement that matters most here is the new US$500 million share repurchase program alongside the US$0.25 quarterly dividend. Those decisions sit on top of guidance calling for fourth quarter GAAP net income of US$294 million and diluted EPS of US$4.04, plus or minus US$0.38.
For shareholders, this ties the story together. MKS is funding Guangzhou expansion, Penang capacity and chemistry growth while also committing cash to buybacks and dividends. Execution on new facilities and the semiconductor cycle remain the main levers, while capital returns add another layer to the catalyst mix without changing the operational risks.
MKS' narrative projects US$7.7b revenue and US$1.6b earnings by 2029. This assumes 17.2% yearly revenue growth and an earnings increase of about US$998m from US$602.0m today.
Uncover why MKS' fair value indicates a 63% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate view focuses on geopolitical risk. The most pessimistic analysts worry that rising trade barriers could keep MKS Inc.'s future margins and cash flow tighter than the consensus assumes. Before this earnings and dividend news, that group was working off revenue forecasts closer to US$6.8b and earnings of about US$1.6b by 2029. Those estimates were set without seeing the latest buyback plan or Guangzhou expansion update, so you should expect opinions to move as new information filters through. Exploring both the upbeat and cautious cases helps you decide where your own comfort zone sits.
Explore 3 other MKS fair value estimates, including one that suggests it could be worth just $215.54.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your MKS research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for MKS. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate MKS' overall financial health at a glance.
Looking for more investment ideas beyond MKS?
If MKS has sharpened your thinking on capital returns, growth assumptions and risk, the next step is to widen your watchlist. A targeted set of screeners can help you filter for businesses that fit your preferred mix of quality, balance sheet strength and potential return profile, without relying on headlines alone.
- If you want potential upside but still care about quality, start with companies flagged for strong fundamentals and meaningful valuation gaps through the 20 high quality undiscovered gems.
- For investors who prioritize resilience over thrills, focus on businesses with sturdier financial footing using the 31 resilient stocks with low risk scores.
- When you care most about cash strength and financial footing, anchor your research around the list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com