
EchoStar (ECHO) Is Getting Fresh Attention, What Is Behind It?
EchoStar (ECHO) has just posted a sharp shift into profit, with third quarter net income of US$2,782.25 million and basic earnings per share from continuing operations of US$9.57 catching investors’ attention.
Recent trading has reflected that earnings swing. EchoStar’s share price has climbed 13.8% over the past month and 8.8% over 90 days, even though the year to date share price return is still down 10.9%. At the same time, the 1 year total shareholder return of 48.4% and very large 3 year total shareholder return suggest that longer term momentum remains strong.
Scan for other potential earnings rebound stories on the Simply Wall St screener built around 20 high quality undiscovered gems, which, like EchoStar, are drawing fresh attention after sharp profitability swings.
EchoStar now appears to be a very profitable operation based on recent figures, yet the share price has only partly caught up to that shift. Is this still a strong business trading on a fair valuation today?
Most Popular Narrative: 28% Undervalued
EchoStar last closed at $100.00, while the analyst consensus Narrative on Simply Wall St pegs fair value at $139.20, based on detailed revenue, margin and discount rate assumptions that point to a sizeable gap between price and calculated worth.
The analysts have a consensus price target of $139.2 for EchoStar based on their expectations of its future earnings growth, profit margins and other risk factors.
Given the current share price of $102.2, the analyst price target of $139.2 is 26.6% higher. Despite analysts expecting the underlying business to decline, they seem to believe it is more valuable than what the market thinks.
See why 29 investors see EchoStar as 28% undervalued.
Result: Fair Value of $139.20 (UNDERVALUED)
Still, the EchoStar story hinges on a few pressure points, including bankruptcy related claims around DISH entities and concentrated exposure to the SpaceX stake.
Find out about the key risks to this EchoStar narrative.
Another View: EchoStar Versus Its Cash Flow Value
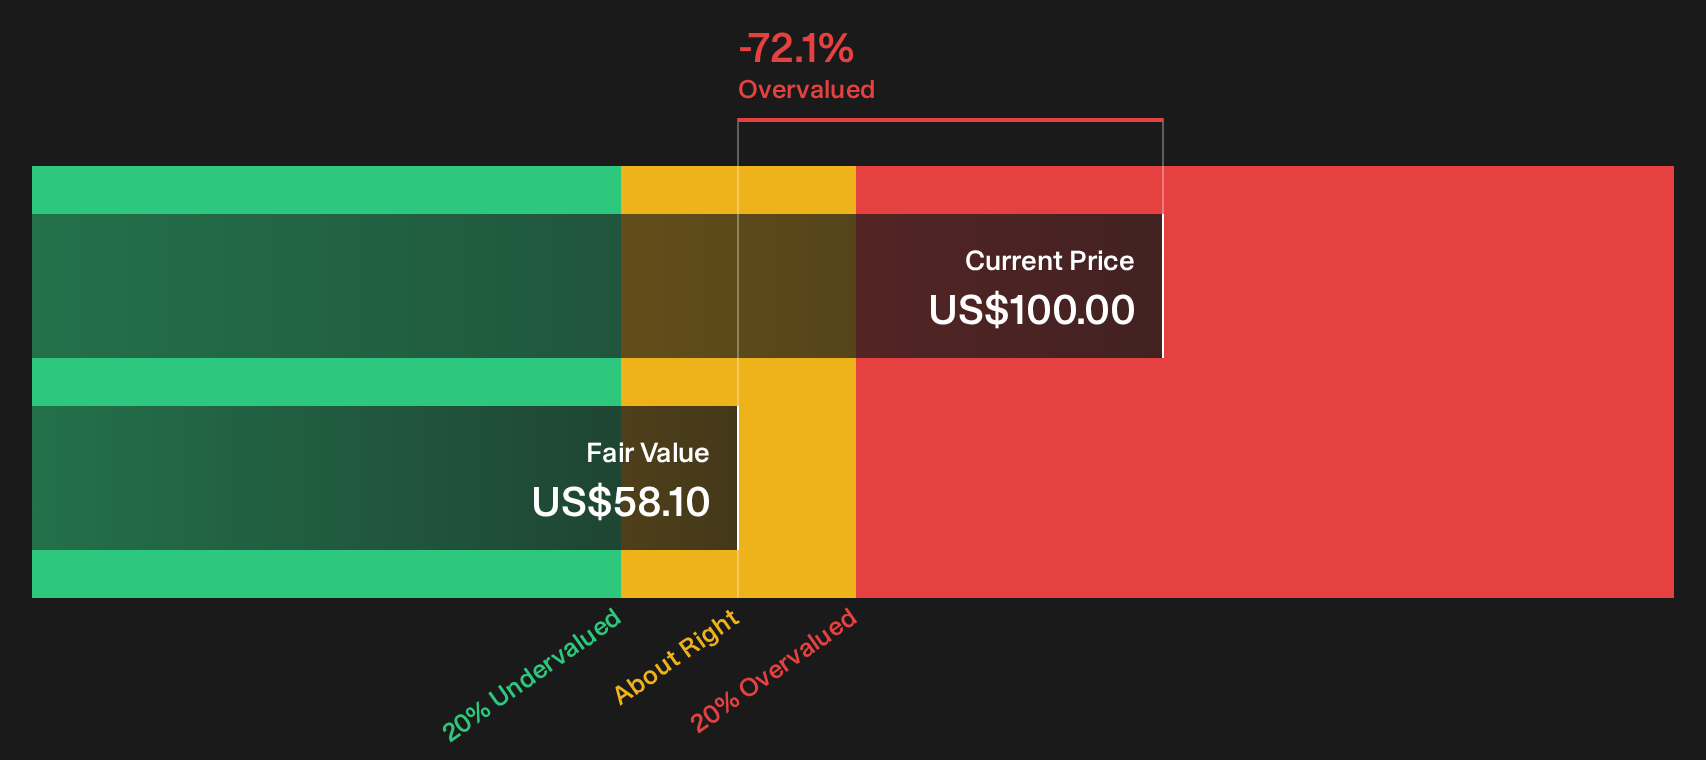
The first narrative paints EchoStar as about 28% undervalued based on analyst targets and asset estimates. A second lens tells a different story. The Simply Wall St DCF model puts fair value closer to $58.10 per share, with the current $100 price sitting well above that cash flow based estimate.
That gap suggests one key question for you: Are you more comfortable anchoring on analyst target ranges and asset values, or on what EchoStar’s projected cash generation implies about today’s price level?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out EchoStar for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around EchoStar is clearly split, with sharp profitability on one side and flagged issues on the other. Move quickly and weigh both angles for yourself with 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond EchoStar?
Do not stop your research with EchoStar. The same earnings swing that caught your eye here could be playing out in other corners of the market right now.
- Target resilient balance sheets first by scanning our list of solid balance sheet and fundamentals (24 results) so you can focus on companies with financial foundations that may better handle shocks.
- Hunt for potential mispricings using the 32 high quality undervalued stocks and see which businesses currently trade at valuations that differ sharply from their fundamentals.
- Build a watchlist of overlooked opportunities with the 31 resilient stocks with low risk scores and keep track of companies that pair measured risk scores with steadier profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com