
What Dollar Tree (DLTR)'s Exclusive Haribo Launch Means For Shareholders
- Dollar Tree has rolled out an exclusive collection of five Haribo gummy candy flavors across its stores, using multi price merchandising to widen its assortment and give shoppers more branded confectionery choice.
- This exclusive Haribo range positions candy as a traffic and basket building tool, testing how differentiated products can support Dollar Tree’s value, convenience and discovery pitch across income groups.
- We will now see how Dollar Tree’s investment narrative could be influenced by this exclusive Haribo candy launch within its multi price push.
Scan how Dollar Tree’s multi price merchandising play compares with other retailers that are leaning on differentiated products and branded impulse buys by shortlisting the 20 high quality undiscovered gems for your watchlist.
Dollar Tree Investment Narrative Recap
To own Dollar Tree, you need to believe the core discount model can keep attracting value focused shoppers while the multi price push and store upgrades translate into steadier profitability. The analyst consensus Narrative on Simply Wall St focuses on store standards, shrink control and focused growth as the main execution swing factors. The Haribo exclusives sit inside that same thesis rather than changing it.
In the near term, the key potential upside catalyst is whether multi price assortments and cleaner stores keep supporting traffic and average ticket as cost of living pressures persist. The biggest risk remains cost pressure from tariffs, freight and delivery partners, which could offset any merchandise wins if they erode gross and net margins.
The Haribo launch directly ties into the existing multi price rollout. The analyst consensus Narrative on Simply Wall St highlights this as already reaching about 17% of sales, while around 85% of sales remain at US$2 and below. More exclusive candy at higher price points fits that mix testing approach, giving Dollar Tree another way to expand assortment without moving away from low ticket value.
For your watchlist, it is worth connecting this with two ongoing catalysts. Management is concentrating capital on Dollar Tree after the Family Dollar divestiture and plans roughly 400 net store openings in 2026, alongside a new Arizona distribution center. If execution on store standards and shrink control holds, more differentiated products such as the Haribo range could help those new locations drive revenue and protect margins against rising logistics and delivery costs.
Dollar Tree's narrative projects US$23.8b revenue and US$1.5b earnings by 2029. This reflects 5.9% yearly revenue growth and a US$0.1b earnings decline from US$1.6b today.
Discover why Dollar Tree's fair value suggests a valuation gap that aligns with its current price.
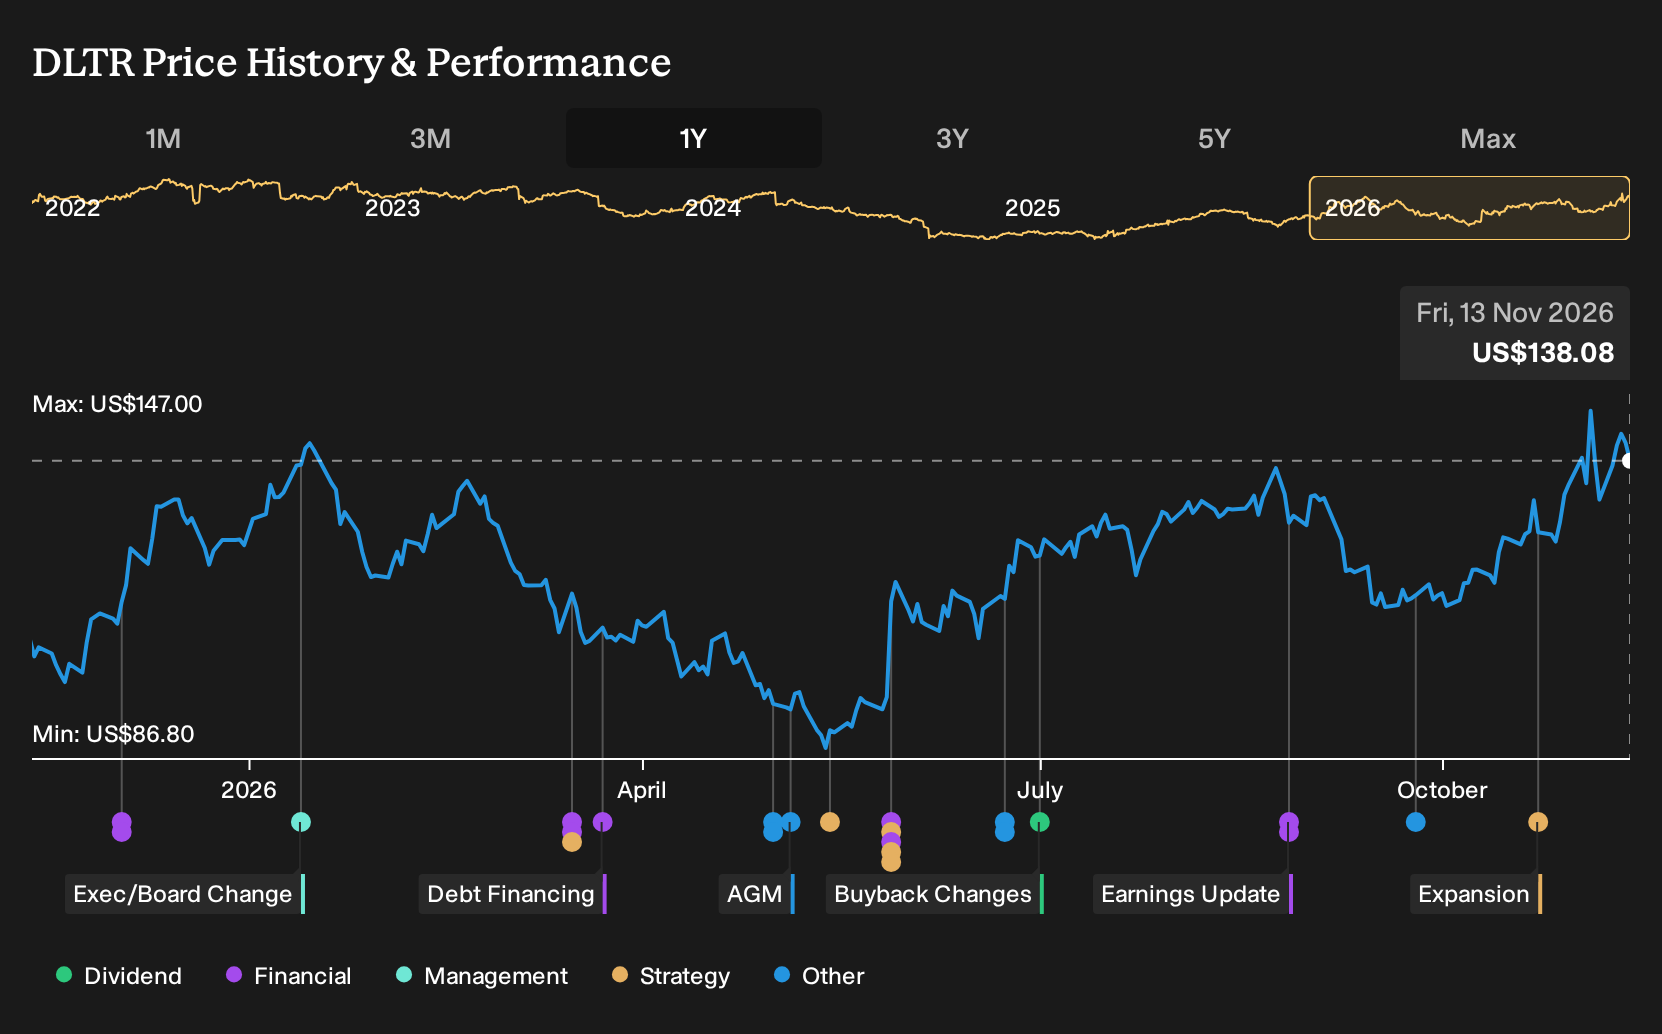
Exploring Other Perspectives
Some bearish analysts focused less on product exclusives and more on cost pressure. They were working with a 5.3% annual revenue growth assumption and earnings closer to US$1.1b by 2029, well below the consensus US$1.5b view. The Haribo launch at Dollar Tree might prompt you to reassess which camp feels closer to your own expectations.
Explore 3 other Dollar Tree fair value estimates, including one that suggests it could be worth just $135.08.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider developing your own view based on research and analysis.
- A great starting point for your Dollar Tree research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Dollar Tree. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Dollar Tree's overall financial health at a glance.
Looking for more Dollar Tree sized ideas?
If the Dollar Tree story has sharpened your thinking, use that same lens on a broader watchlist. The Simply Wall St Screener can help you filter for traits that match your own risk, quality and income preferences instead of relying only on headline stories.
- If capital protection is a priority, start with a basket of companies that screen as resilient on balance sheet strength and fundamentals through the list of solid balance sheet and fundamentals (24 results).
- For those hunting for mispriced quality, widen the search to stocks that combine strong underlying business metrics with potentially attractive pricing by reviewing the 32 high quality undervalued stocks.
- If income is central to your plan, focus on businesses with sizeable yields that also aim for durability by scanning the 6 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com