
Should Earnings Rebound Require Action From Marriott Vacations Worldwide (VAC) Investors?
- Marriott Vacations Worldwide reported third quarter 2026 revenue of US$1.367b and net income of US$82 million, compared with a loss a year earlier, along with higher earnings per share for both the quarter and the first nine months of the year.
- The shift from a prior loss to positive earnings, together with higher year to date revenue, highlights how Marriott Vacations Worldwide’s operating model is currently converting resort activity and financing into stronger profitability.
- We will now look at how Marriott Vacations Worldwide’s investment narrative could be influenced by this return to positive earnings.
Scan how Marriott Vacations Worldwide's earnings rebound compares with other companies turning stronger fundamentals into potential upside through our hand picked 20 high quality undiscovered gems.
Marriott Vacations Worldwide Investment Narrative Recap
An investor in Marriott Vacations Worldwide needs to believe the vacation ownership model can keep converting high resort usage and a healthy tour pipeline into sustainable contract sales and financing income. The third quarter move from a prior loss to US$82 million of profit and higher earnings per share supports that thesis, but does not remove execution risk around owner upsells and first time buyer conversion.
In the short term, the key catalyst remains sales productivity, particularly Value Per Guest and the balance between first time buyers and existing owner upgrades described in the analyst consensus Narrative on Simply Wall St. The biggest risk still looks tied to credit quality and loan performance, since any further step up in delinquencies or reserves would work directly against the earnings momentum just reported.
The upcoming Investor Day on 9 December 2026 now sits squarely in focus after this earnings rebound. Management plans to outline a long term strategy, a sustainable growth plan and a multi year financial framework. That should help you judge how repeatable the current US$1.367b quarterly revenue run rate and year to date performance might be.
For anyone tracking catalysts, that event is a practical check on the modernization, loyalty integration and capital discipline themes in the analyst consensus Narrative on Simply Wall St. Execution detail on contract sales initiatives, securitizations and balance sheet targets will matter, because the firm still carries risks around interest coverage, cost pressure and credit reserves that the recent quarter has not fully resolved.
Marriott Vacations Worldwide's current narrative ties analyst expectations to a forecast for about US$6.8b in revenue and US$676.9 million in earnings by 2029. That profile assumes revenue grows at roughly 25.5% a year and that earnings move from a loss of US$334.0 million today to US$676.9 million, which is an increase of about US$1.01b over that period.
Uncover why Marriott Vacations Worldwide's fair value indicates a 6% potential upside to its current price, which could narrow quickly.
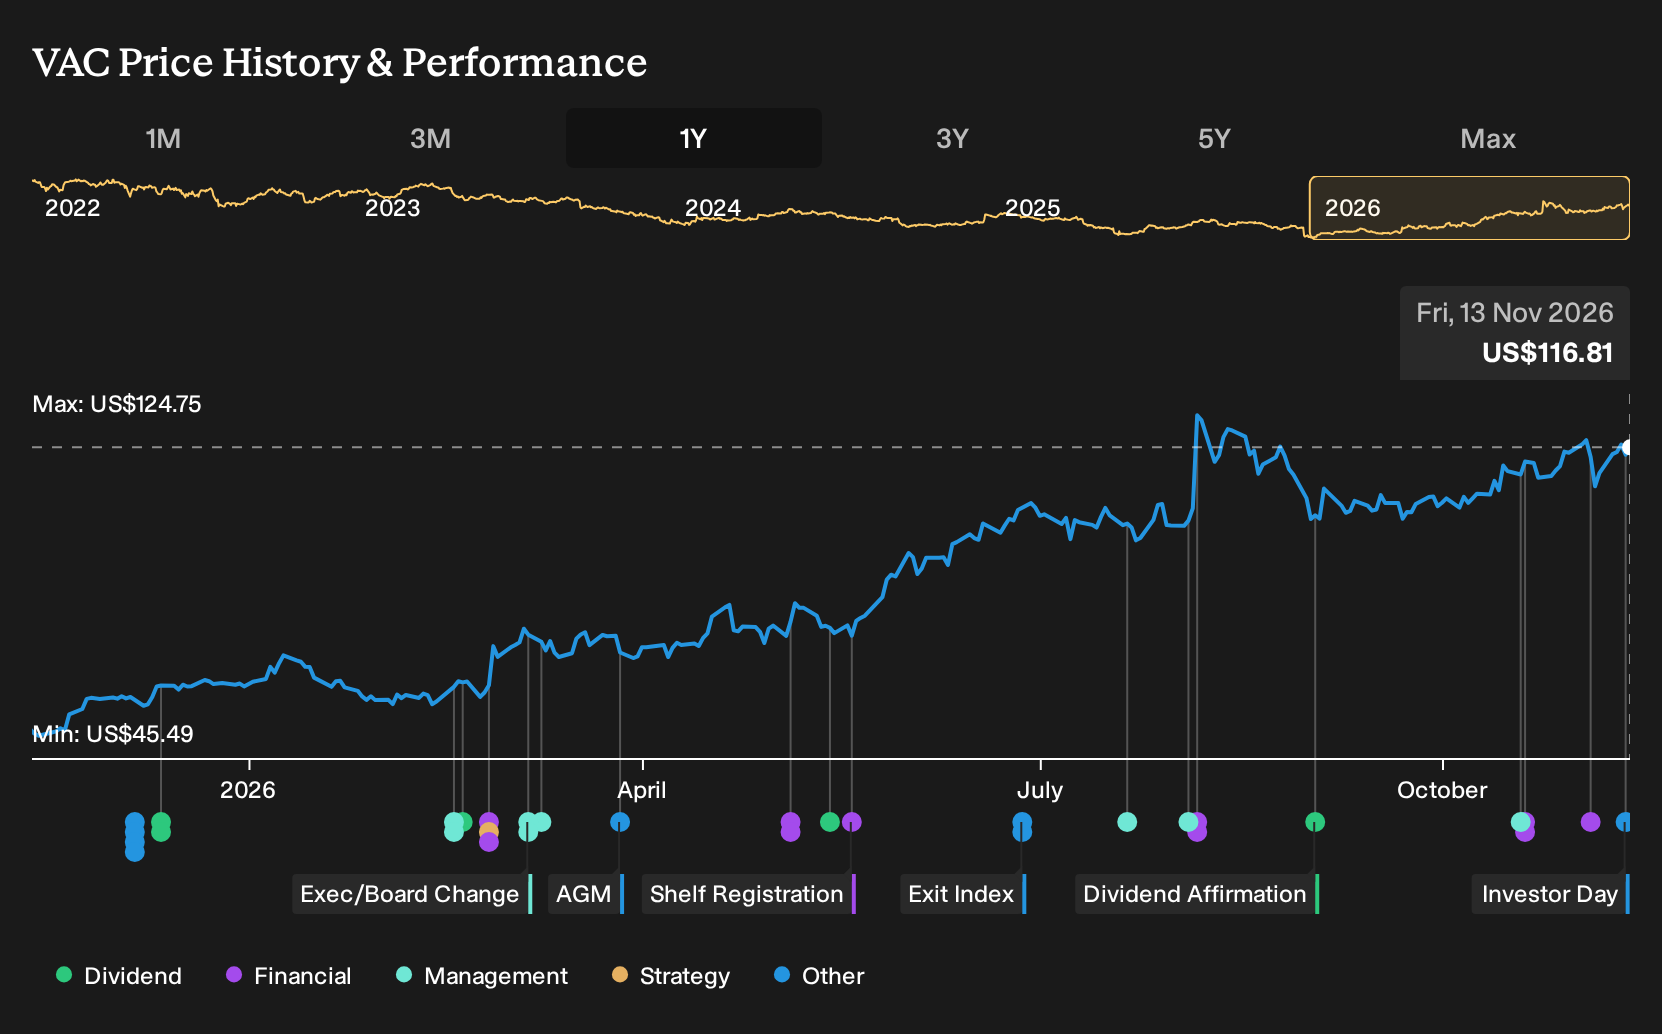
Exploring Other Perspectives
One bearish angle on Marriott Vacations Worldwide focuses on leverage. The most pessimistic analysts were working off a Fair Value that implied revenue of about US$6.2b and earnings of US$567.0 million by 2029, yet only a 6.6x P/E. Those views were set before this earnings jump, so you may see them shift as new information is incorporated.
Explore 3 other Marriott Vacations Worldwide fair value estimates, including one that suggests as much as 33% downside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider trusting your own analysis and instincts.
- A helpful starting point for your Marriott Vacations Worldwide research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Marriott Vacations Worldwide. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to review Marriott Vacations Worldwide's overall financial health at a glance.
Looking for more investment ideas beyond Marriott Vacations Worldwide?
If this Marriott Vacations Worldwide review has raised new questions rather than tying everything up neatly, that is useful. It means you are thinking in frameworks that can be applied to other opportunities as well, which is where a broad stock screener becomes a practical next step.
- If you want to focus on value and quality together, start with companies that combine strong fundamentals with attractive pricing through our 32 high quality undervalued stocks.
- For readers who care most about balance sheet strength and financial resilience, narrow your search using the list of solid balance sheet and fundamentals (24 results).
- Income focused investors can concentrate on payout strength and yield reliability by screening for companies that match your preferences using the 6 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com