
Tyson Foods (TSN) Stock Looks Reasonable At Today’s Earnings Level
Tyson Foods has climbed over the past three years while working through tighter cattle supplies and slimmer meat margins, which puts fresh focus on whether the current share price lines up with the earnings that support it. With the stock at US$58.82 after mixed shorter term moves, investors are asking how much of the company’s profit power is already reflected in that quote.
- Over the last 3 years the stock has returned 33.9% which raises the question of how fully that gain reflects the business’s earnings profile.
- The new long term partnership with Allied Beef and the plan to fully reopen a second shift at the Amarillo plant by 2027 can influence Tyson Foods’ margin outlook and the timing of future beef cash flows as cattle supply tightness eases.
- There is a second opinion on Tyson Foods worth weighing. See what analysts think Tyson Foods's shares could be worth.
The issue now is whether Tyson Foods’ current market value is justified by the level and quality of earnings the business is generating today.
If you are weighing Tyson Foods against other quoted meat and food producers, it often helps to compare it with companies that pass a similar quality and valuation screen such as 32 high quality undervalued stocks.
Where Does Tyson Foods Sit on Earnings?
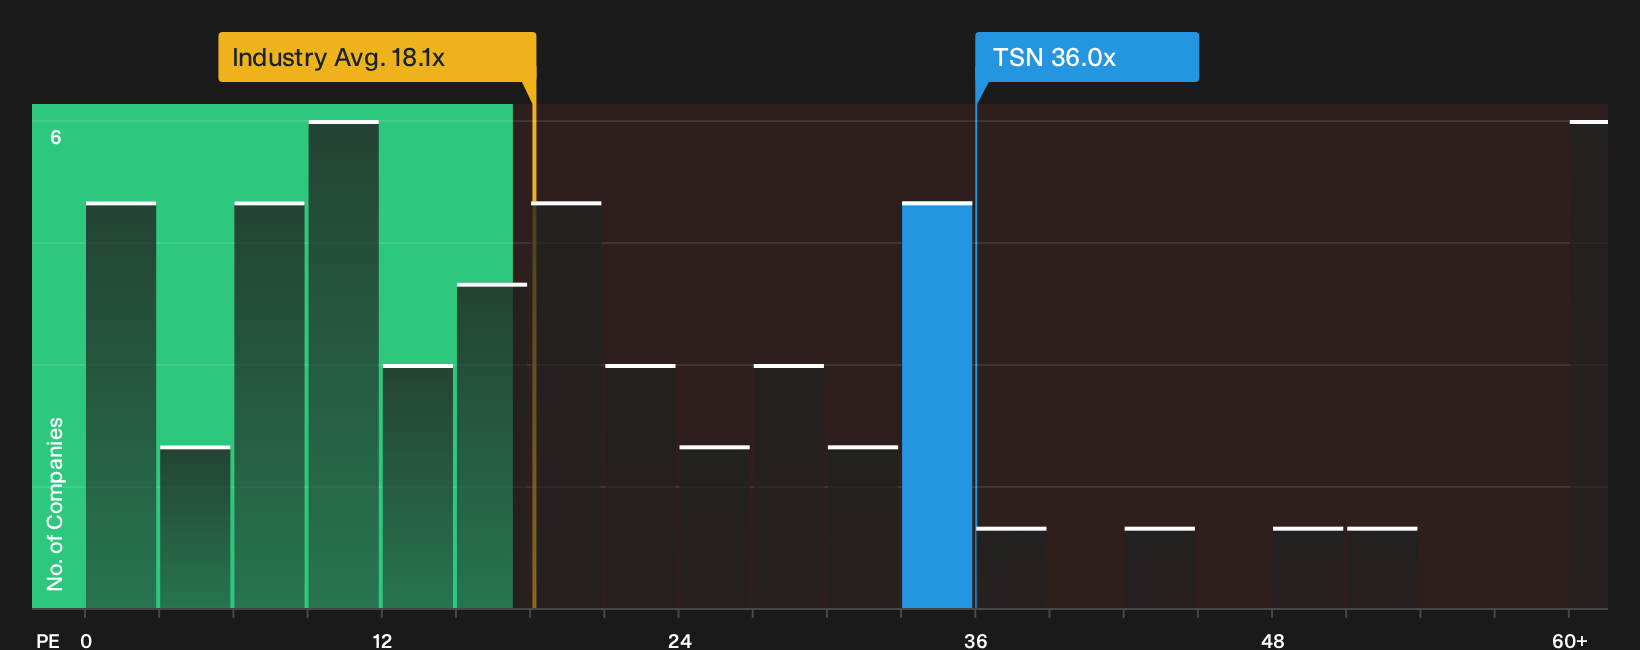
P/E is a useful yardstick for Tyson Foods because meat processing remains a mature, earnings driven business where profits matter more than story. On this measure, Tyson trades on a P/E of 36.0x, which is higher than both the food industry average of 18.1x and the peer group around 31.3x. The tailored fair P/E from the model, which blends Tyson’s margin profile, risk and growth assumptions, sits close enough to the current level that the ratio points to a price that is about right rather than clearly cheap or expensive.
Because the market is already paying a premium to the sector, the key question for you is whether Tyson Foods can defend that earnings multiple as cattle supply tightness and beef margins evolve. The new Allied Beef partnership and the planned second shift reopening at Amarillo look already reflected in this richer P/E, so any reassessment from here will hinge on how those moves translate into consistent profits over time. Explore the numbers behind Tyson Foods's P/E valuation.
The Tyson Foods Narrative: What Would Justify Today's Price?
Narratives on Simply Wall St break down Tyson Foods' valuation puzzle and explain what would need to happen with future growth, margins and earnings for the stock to trade meaningfully higher or lower than it does today, all in a format that appears on the Community page. Rather than relying on a single multiple or model output, each narrative sets out the earnings assumptions that underpin its view of fair value so you can compare them with actual results over time.
Bulls and bears on Tyson Foods are looking at the same beef hit and chicken shift, then reaching very different conclusions about what is already in the price.
Bull case: 7% undervalued
The analyst consensus Narrative on Simply Wall St highlights Tyson Foods’ mix shift and branded portfolio as the key support.
"Continued mix shift at Tyson Foods toward branded and value-added Prepared Foods and Chicken, supported by multiple quarters of segment volume and sales growth and higher-margin pull-driven contracts…"
Discover why this Narrative puts Tyson Foods at 7% undervalued.
Bear case: 5% overvalued
The bearish analyst Narrative on Simply Wall St focuses on what happens if beef losses and execution issues keep affecting results.
"While Chicken and Prepared Foods currently provide solid support, the expectation for the Beef segment to record a full year operating loss of US$500m to US$650m…"
Explore why this Narrative puts Tyson Foods at 5% overvalued.
A final loose end for Tyson Foods valuation
All of this focuses on where Tyson Foods is priced today, yet analyst models sketch out where earnings and cash generation might land a few years from now and provide a very different lens on the stock. Explore where analysts expect Tyson Foods to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com