
Can Labcorp Holdings (LH) Hold Its Value After The $375 Million Deal?
Labcorp Holdings has put up a powerful share price run in recent years, which naturally raises the question of whether that move is backed up by its earnings power. With the stock now reflecting both market optimism and fresh deal activity, the key issue is how much of the company’s profit story is already baked into today’s price.
- Over the past 3 years, Labcorp Holdings has delivered a 80.6% share price return, so a lot now rides on whether its earnings performance can support that kind of rerating.
- The completed US$375m acquisition of Millennium Health adds toxicology testing scale and broader geographic reach, which may support expectations for future profit growth and cash generation once integration is digested.
- Your read on Labcorp Holdings is one view; the desks covering it have another. See what analysts think Labcorp Holdings's shares could be worth.
The issue now is whether the current share price of Labcorp Holdings is justified by the earnings it is generating and what investors reasonably expect it to produce in the years ahead.
If you are weighing Labcorp Holdings against other healthcare names where earnings quality is in focus, it can help to set it alongside solid balance sheet and fundamentals stocks screener (24 results).
Where Does Labcorp Holdings Sit on Earnings?
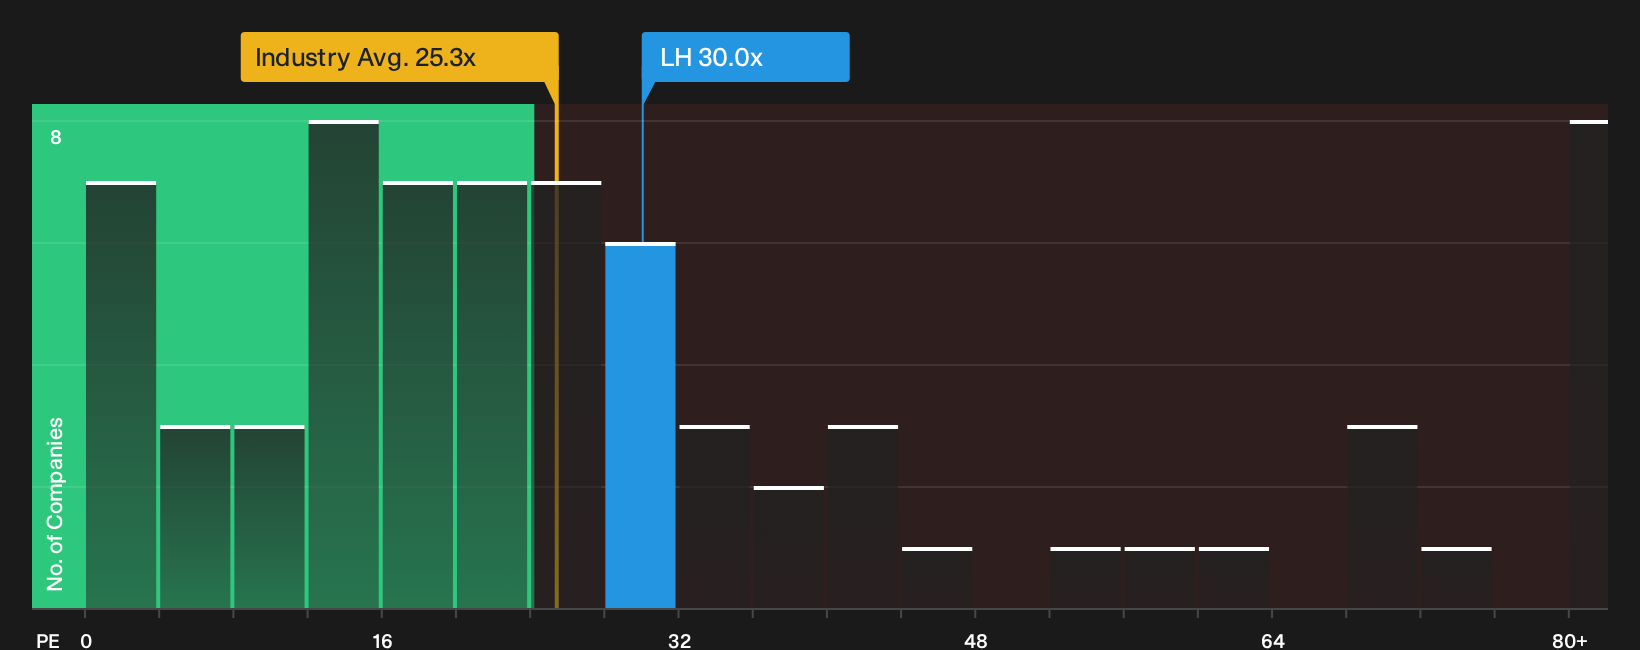
The P/E ratio is a useful lens for Labcorp Holdings because earnings remain a core reference point for how investors frame the business. Labcorp currently trades on a P/E of 30.0x, which is above the broader Healthcare sector average of 25.3x and above peers on roughly 24.6x. That gap means buyers today are paying a richer price for each dollar of net profit than they would for a typical laboratory or healthcare group.
Because the completed US$375m Millennium Health deal has sharpened interest in Labcorp’s toxicology footprint, the higher multiple appears consistent with what a tailored model might estimate for a company with its mix of growth drivers, margins and risk profile. The stock is therefore priced close to the level suggested by that fair-value P/E benchmark rather than at a clear discount or premium. Investors need to judge whether Labcorp’s earnings quality, acquisition execution and balance sheet make that outcome attractive for their own return targets. Explore the numbers behind Labcorp Holdings's P/E valuation.
The Labcorp Holdings Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Labcorp Holdings pick up where the valuation puzzle leaves off and spell out what would need to happen to revenue growth, profitability and earnings for the stock to be worth materially more or less than it is today, using Labcorp Holdings' Community page as the hub for those scenarios. Each narrative ties a single fair value estimate to a clear version of Labcorp Holdings' potential catalysts and risks so you can track over time which story seems closest to reality.
One of the top narratives on Labcorp Holdings: 5% undervalued
This Narrative is the analyst consensus Narrative on Simply Wall St, which compiles analysts' consensus price target and revenue and earnings forecasts, not one person's view.
"Labcorp Holdings continues to expand higher value specialty testing in oncology, neurology, autoimmune disease and women’s health, with this franchise now around US$2b in diagnostics revenue…"
Discover why this Narrative puts Labcorp Holdings at 5% undervalued.
One more Labcorp Holdings signal that could change how you read this story
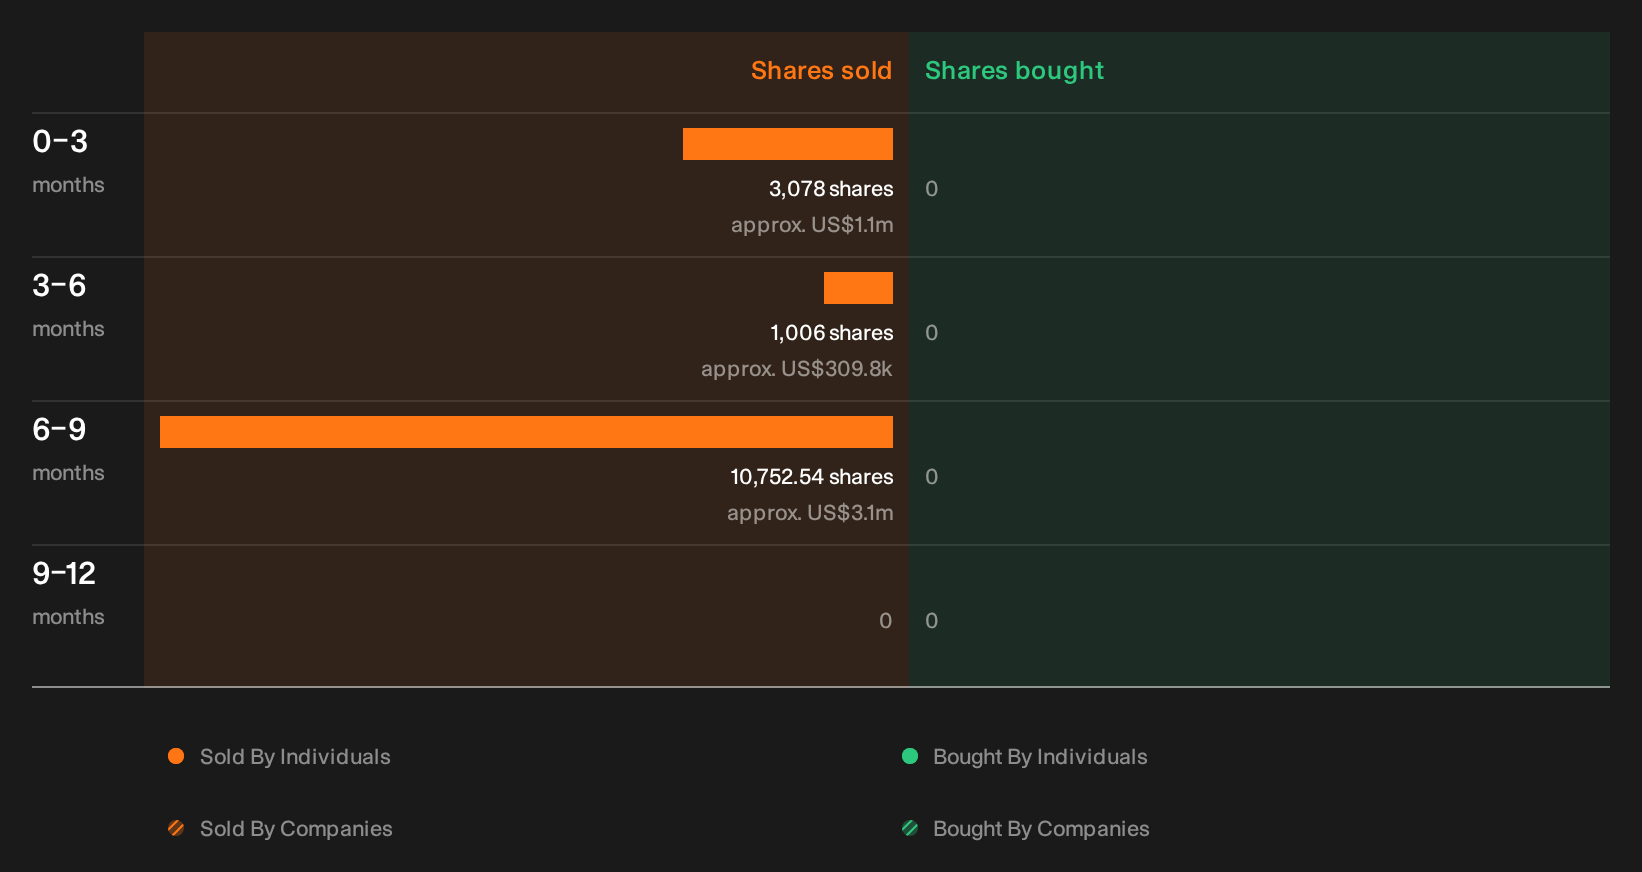
Valuation only tells part of the Labcorp Holdings picture, because recent trading disclosures show insider share sales that raise a fresh question about what management is doing with their own holdings. See the recent insider selling flagged for Labcorp Holdings.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com