
What Just Happened With Zensho Holdings (TSE:7550)?
Zensho Holdings (TSE:7550) came into focus after a November 12 board meeting on treasury share disposal for its performance-linked stock plan and a same-day upgrade to full-year earnings guidance supported by stronger half-year results.
The guidance upgrade landed on a stock that already had strong momentum, with a 1-day share price return of 5.69% and a 7-day gain of 8.82%, feeding into a 30-day share price return of 13.42% and a year-to-date share price return of 48.92%. Total shareholder return sits at 49.12% over one year and roughly 5x over five years, signalling that investors have been rewarding Zensho Holdings for its progress for some time rather than reacting only to the latest announcement.
Scan how Zensho Holdings fits into a broader watchlist by comparing its run with our hand-picked 72 high quality undiscovered gems, which also pair strong fundamentals with active investor interest.
Zensho Holdings now trades slightly above analyst targets and at a sizeable premium to some intrinsic estimates after this latest surge. That gap sets up the real test: Is the market being early or simply cautious for a reason?
Preferred P/E of 41.3x: Is it justified?
Valuation now leans heavily on how much investors are willing to pay for Zensho Holdings earnings, and the latest data points to a rich P/E of 41.3x that sits above both industry and peer benchmarks.
The P/E ratio compares the current share price to earnings per share. For a food service and hospitality group like Zensho Holdings, this metric gives a quick read on how much the market is willing to pay today for each unit of profit that the business generates.
Here, the market is assigning a 41.3x P/E while the estimated fair P/E ratio, based on regression analysis, sits lower at 37.2x. That signals investors are paying a premium to the level models suggest the valuation could move toward, even with earnings forecast to grow 15.6% per year and revenue projected to rise 9.2% per year.
The premium becomes even clearer when stacked against external benchmarks. The JP Hospitality industry average P/E is 21.3x, and the peer group average sits at 39.6x. Zensho Holdings trades richer than both. That combination of a higher multiple than sector, peers, and the 37.2x fair ratio implies the bar for future execution is set relatively high.
Explore the SWS fair ratio for Zensho Holdings.
Result: Price-to-earnings of 41.3x (OVERVALUED)
Still, a rich 41.3x P/E leaves little room for disappointment if Zensho Holdings stumbles on overseas expansion or faces weaker profitability across key restaurant formats.
Find out about the key risks to this Zensho Holdings narrative.
Another view on Zensho Holdings using cash flows
The P/E suggests Zensho Holdings is priced for strength, yet our DCF model points the other way. With the share price at ¥13,270 against an estimated future cash flow value of ¥9,552.08, the stock screens as expensive. Which signal do you trust more, earnings or cash flows?
Look into how the SWS DCF model arrives at its fair value.
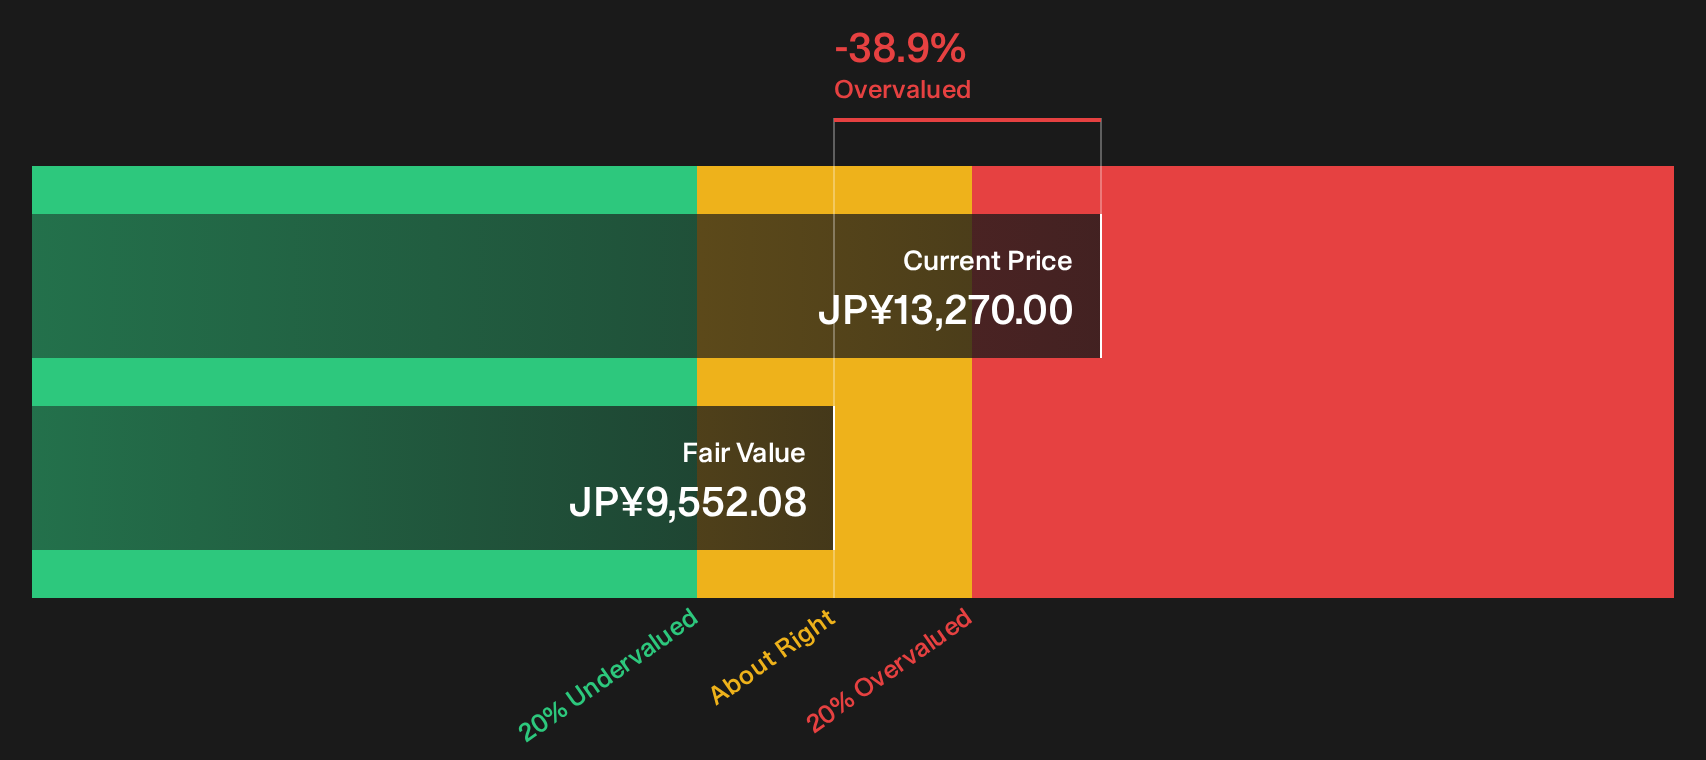
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Zensho Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 19 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Zensho Holdings valuation can feel confusing, so move quickly to review the underlying metrics, weigh both the upside and the red flags, and then benchmark your view against the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Zensho Holdings?
If Zensho Holdings feels fully priced, do not stop your research here. Fresh ideas often emerge where strong balance sheets, value, and resilience intersect.
- Pinpoint sturdier candidates by scanning companies with resilient finances using our list of solid balance sheet and fundamentals (24 results).
- Hunt for potential value opportunities that pair quality with attractive pricing through the 19 high quality undervalued stocks.
- Reduce unpleasant surprises by focusing on businesses that screen well for stability using the 20 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com