
Weibo (WB) Stock May Be Undervalued As Earnings Stay In Focus
Weibo has seen a steep share price slide in recent years, which puts a spotlight on whether the current US$6.16 quote is still in step with the earnings power of the business. With that kind of track record in the rear-view mirror, the key issue for you is whether the stock price now lines up with what the company actually earns.
- Weibo shares have declined 79.6% over the past 5 years, so the central question is whether that drop now reflects the underlying earnings profile or has moved away from it.
- The business model depends heavily on monetising user attention through advertising and related services, which can affect how consistently earnings convert into cash and how much profit is available to support the current valuation.
- Your read on Weibo is one view; the desks covering it have another. See what analysts think Weibo's shares could be worth.
The stock's next move may depend on whether today's valuation can be explained by Weibo's current and expected earnings stream.
If Weibo's slide has you reassessing this theme, it can help to compare it with other companies screened for 32 high quality undervalued stocks.
Is Weibo a Bargain on Earnings?
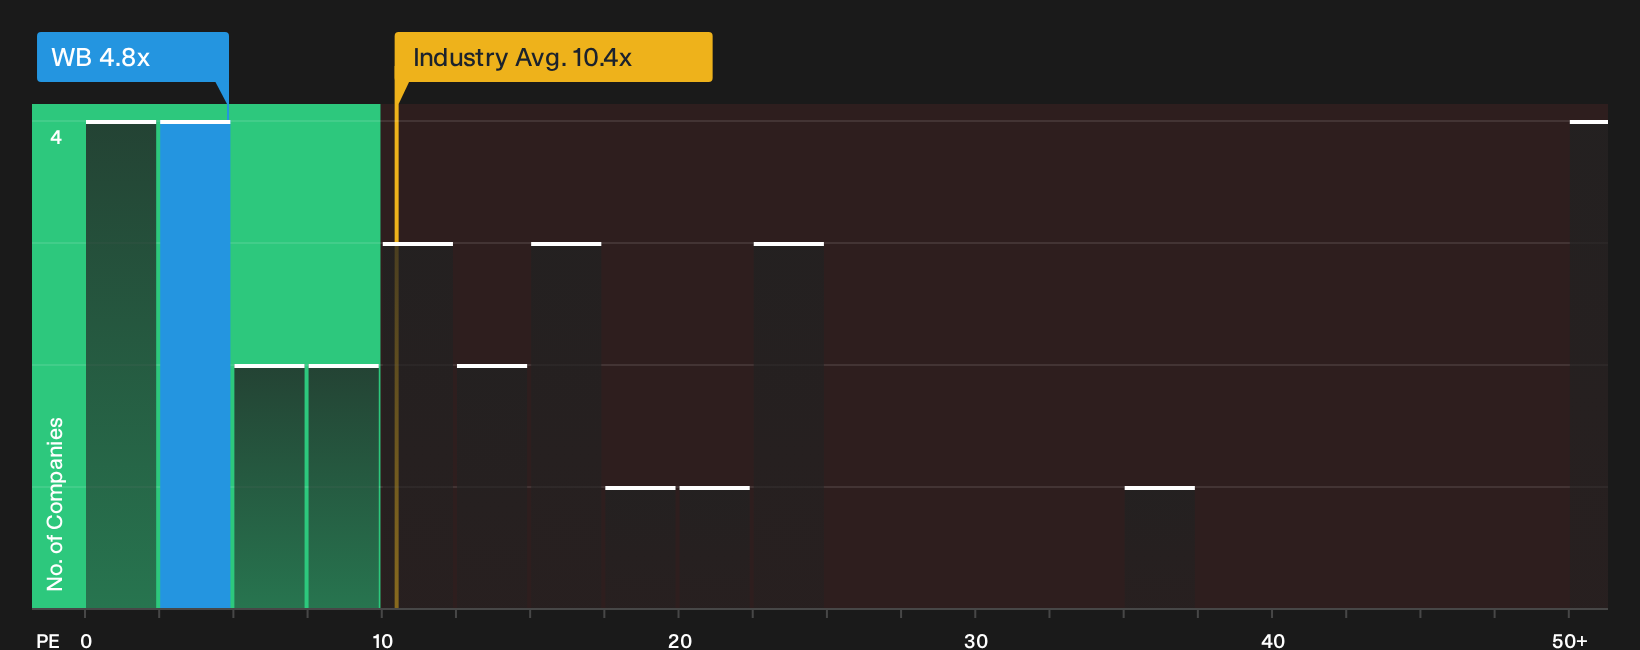
The P/E ratio suits Weibo because earnings remain a key yardstick for a mature advertising led platform. On this lens, the stock trades on a P/E of about 4.8x, which is well below the Interactive Media and Services industry average of roughly 10.4x and the peer group near 13.8x. That gap indicates the market is paying a much lower price for each dollar of Weibo's reported profit than for many comparable platforms.
The fair P/E level implied by a model that incorporates Weibo's growth profile, profitability, scale and risk points to a higher ratio than where the shares change hands today. As a result, the current multiple screens as undervalued on this framework. For an investor weighing up the situation, a key question is whether those earnings are durable enough to justify narrowing some of that gap over time, or whether the discount reflects concerns that will persist. Explore the numbers behind Weibo's P/E valuation.
The Weibo Narrative: What Would Justify Today's Price?
Weibo Narratives on Simply Wall St's Community page pick up where the valuation question leaves off by explaining which earnings, margin and growth paths would need to occur for the stock to be worth meaningfully more or less than it is today. Each narrative links its number to a clear view on how Weibo's growth, profitability and key risks might evolve, giving you a reference point you can return to as new information becomes available.
One of the top narratives on Weibo: 25% undervalued
This Narrative is the analyst consensus Narrative on Simply Wall St, which compiles analysts' consensus price target and revenue and earnings forecasts; it is not one person's view.
"The numbers imply that Weibo’s share price reflects a very low multiple on its free cash flow, so the market is pricing the operating business conservatively…"
Discover why this Narrative puts Weibo at 25% undervalued.
One more thing about Weibo that could change the picture
Valuation only tells part of the story, because recent checks on Weibo also flag specific concerns that could matter for anyone weighing up the stock's risk profile. Take a closer look at 1 warning sign before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com