
Okta (OKTA), What Is Behind The Fresh Attention?
Okta (OKTA) just rotated between two major indices, exiting the Russell Small Cap Comp Value Index and joining the S&P 500 Equal Weighted Index. This shift can prompt index-tracking funds to rebalance.
Okta’s recent index shuffle comes after a sharp run up, with the share price at US$182.87 and a year to date share price return of 118.64%. This is despite the 1 month share price return being down 13.71%, while the 1 year total shareholder return of 117.86% and 3 year total shareholder return of 160.42% suggest longer term momentum remains strong despite some pressure in the past month.
Scan how Okta’s index move compares with other fast moving software players by reviewing our curated list of 42 profitable AI stocks that aren't just burning cash in similar high attention niches.
After a sharp run and an index reshuffle, Okta now trades only slightly below both analyst targets and one intrinsic value estimate. Does that narrow gap still leave enough upside to justify today’s US$182.87 price?
Most Popular Narrative: 21% Overvalued
Okta’s most followed narrative on Simply Wall St pegs fair value at $151, below the last close at $182.87, so the story here is about whether investors are paying up for a strong identity franchise and an expanding AI angle. According to Tokyo, an investor in the Simply Wall St Community who built this valuation, the key question is how far today’s price runs ahead of that thesis.
For a long time, the market criticized Todd McKinnon because Okta, despite having an excellent technical solution, failed to become profitable. With the Q1 FY2027 results, that discussion appears to be over.
See why 105 investors see Okta as 21% overvalued.
Tokyo works off a discount rate of 7.47%, a projected 10.5% annual revenue growth rate and a 21% profit margin, then applies a 35x future P/E multiple to arrive at a fair value of $151 for Okta. That framework effectively says the current $182.87 quote already bakes in a lot of the profitability and growth that this model assumes over the next few years.
The narrative also leans on a bigger potential swing factor, which is identity and access management for AI agents. However, it treats that as upside that still needs proof points in Okta’s reported operating metrics. Until that AI identity layer shows up as things like managed agent counts or monetized events, this view treats the extra enthusiasm in the share price as investors paying a premium for optionality rather than cash flows already in hand.
Result: Fair Value of $151 (OVERVALUED)
Still, this storyline can change if Okta’s AI agent opportunity materializes more slowly or if profit margins fall short of the 21% assumption.
Find out about the key risks to this Okta narrative.
Another View: DCF Says Slightly Undervalued
Okta looks expensive on Tokyo’s fair value narrative, yet the SWS DCF model paints a softer picture. At $182.87, the stock trades about 3.1% below an estimated future cash flow value of $188.71, which frames the shares as slightly undervalued instead of stretched. Which story appears more realistic to you?
To understand how this cash flow view is built and what would need to change before it flips the verdict the other way, Look into how the SWS DCF model arrives at its fair value.
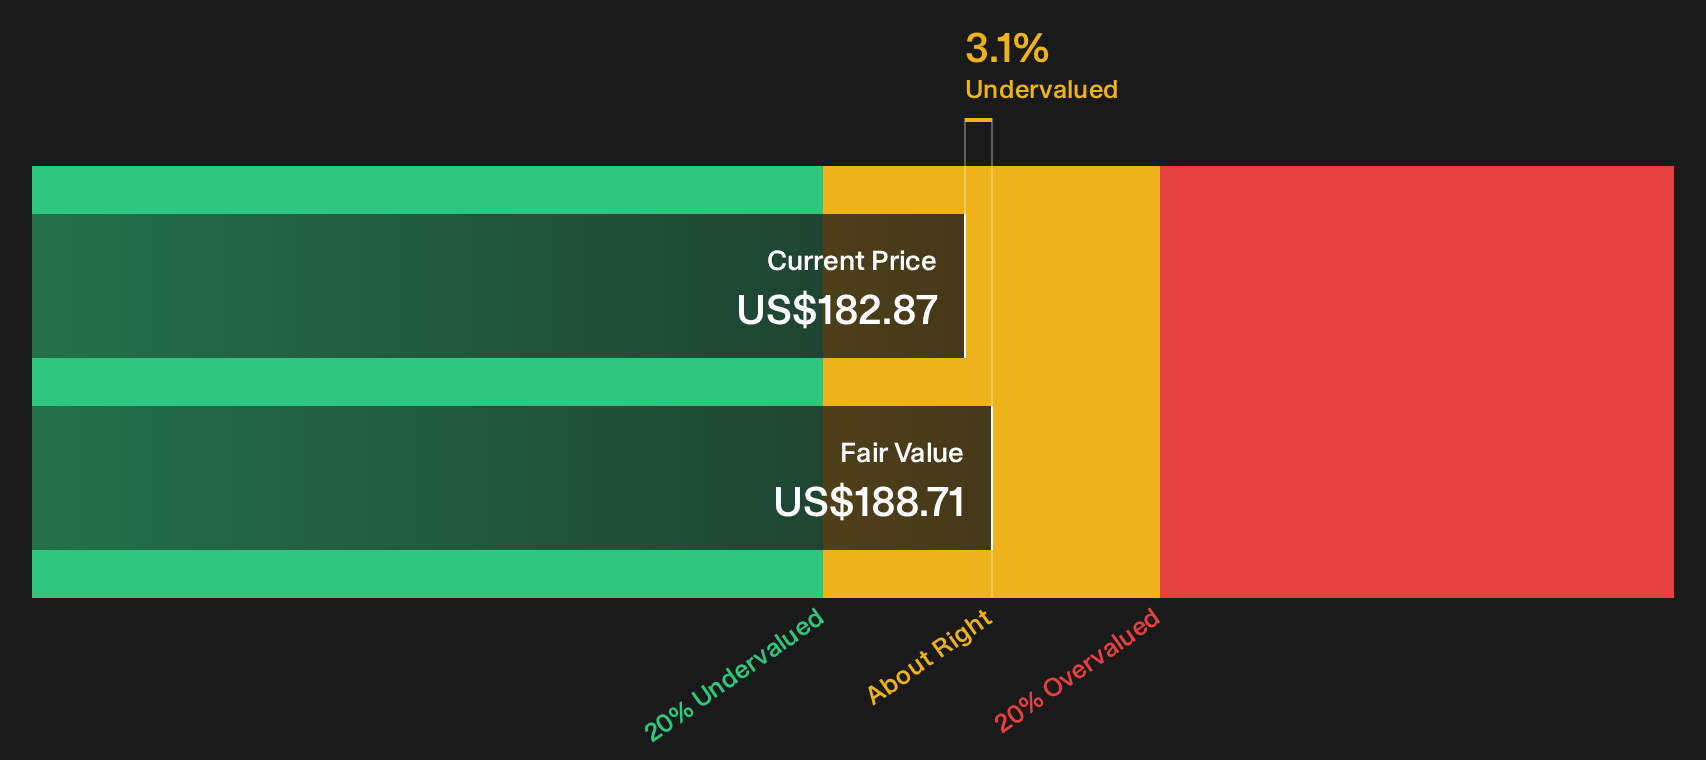
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Okta for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Okta so far. If you want to move fast and still think for yourself, consider both sides of the story through 3 key rewards and 1 important warning sign.
Looking for more ideas beyond Okta?
If Okta has your attention, do not stop here. Broaden your watchlist so you are not relying on a single story when opportunities shift.
- Target potential mispricings by scanning a curated pool of quality companies trading below their estimated worth through 32 high quality undervalued stocks.
- Build a steadier foundation for your portfolio with companies that pair durable finances with healthy balance sheets using the list of solid balance sheet and fundamentals (24 results).
- Hunt for underfollowed opportunities where strong fundamentals have not yet been fully recognized by the market by checking the 20 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com