
How Investors May Respond To Amphastar Pharmaceuticals (AMPH) Strong Earnings Guidance
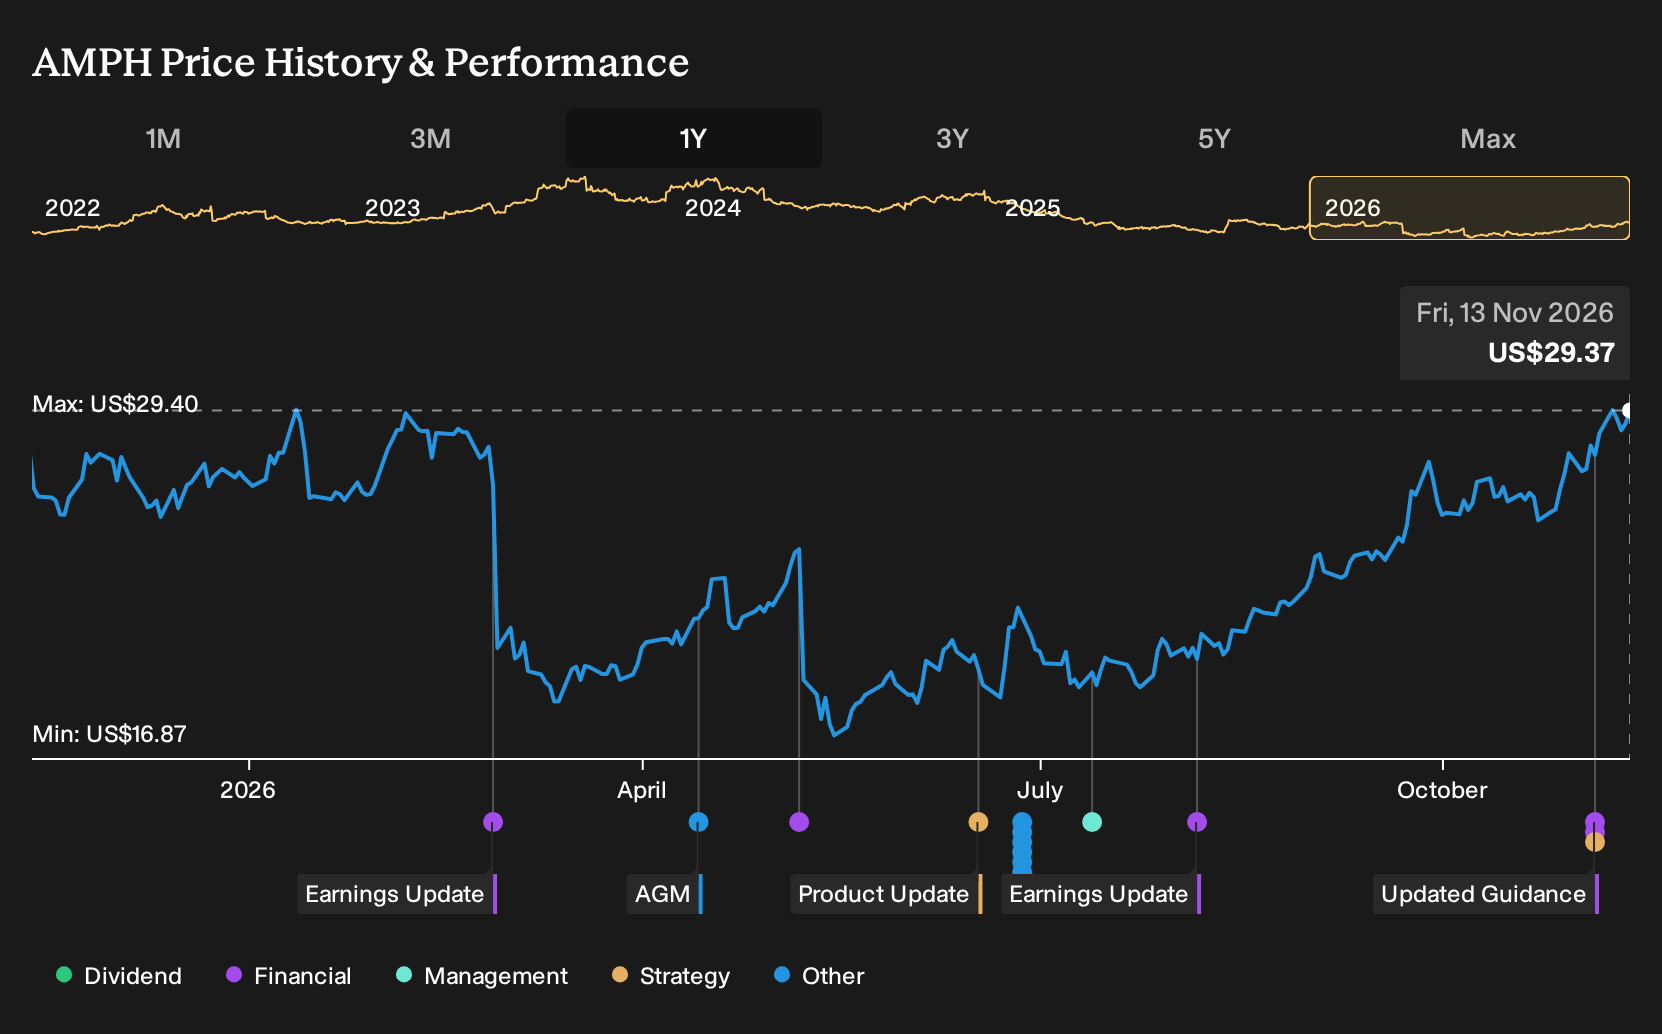
- Amphastar Pharmaceuticals reported third quarter 2026 sales of US$207.61 million and net income of US$37.76 million, alongside fourth quarter guidance calling for high single digit sales growth compared with the prior year period.
- The sharp year on year jump in earnings per share from continuing operations, with diluted EPS moving to US$0.87 from US$0.37, highlights how recent product mix and cost choices are feeding into profitability.
- Next is an examination of how Amphastar Pharmaceuticals' stronger third quarter profitability and high single digit sales guidance could influence its investment narrative.
Scan how Amphastar Pharmaceuticals' latest guidance compares with other companies showing resilient earnings power through our hand picked 32 high quality undervalued stocks screener.
Amphastar Pharmaceuticals Investment Narrative Recap
To own Amphastar Pharmaceuticals, you need to be comfortable with a story built on complex generics, respiratory therapies and a developing pipeline that is gradually absorbing pressure in older glucagon and epinephrine lines. The third quarter jump in earnings and solid sales looks supportive, although the high single digit fourth quarter sales outlook does not materially change the near term debate on margin pressure.
The main short term swing factor remains how long higher margin respiratory and injectable products can offset payer pushback and rising rebates, especially around BAQSIMI and related diabetes treatments described in the analyst consensus Narrative on Simply Wall St. The biggest risk is that capital spending and R&D keep lifting the cost base faster than new launches and price actions replenish profitability.
The clearest operational datapoint to focus on right now is Amphastar Pharmaceuticals' third quarter and nine month earnings release on 5 November 2026. Management reported US$207.61 million in quarterly sales and US$37.76 million in net income, alongside a move in diluted EPS from continuing operations to US$0.87 from US$0.37 a year earlier.
This result ties directly into the current catalyst discussion. It shows how the existing respiratory and injectable portfolio is supporting earnings even as analysts remain concerned about pricing pressure, higher rebates and exposure to a concentrated product mix. Your assessment comes down to whether this profitability level can be sustained while capacity investments, insulin aspart and proprietary programs move closer to commercial contribution.
What The Current Forecasts Assume For Amphastar Pharmaceuticals
Amphastar Pharmaceuticals' current analyst narrative rests on a modest 4.8% yearly increase in revenue over the next few years, paired with only a small expected squeeze in profit margins from 13.3% today to 13.2% over a three year window.
Analysts are working off earnings today of US$99.0 million and a consensus view that Amphastar Pharmaceuticals could reach US$113.4 million of earnings and US$858.5 million of revenue by 2029. That implies an earnings increase of about US$14.4 million from current levels.
Amphastar Pharmaceuticals' narrative projects US$858.5 million revenue and US$113.4 million earnings by 2029. This requires 4.8% yearly revenue growth and an earnings increase of about US$14.4 million from US$99.0 million.
Uncover why Amphastar Pharmaceuticals' fair value points to a 17% potential downside to its current price. This suggests a premium that may not hold.
Exploring Other Perspectives
One worry from the more bearish Amphastar Pharmaceuticals narrative is the risk that BAQSIMI rebates and 340B discounts keep eating into glucagon profitability. Those analysts were only pencilling in roughly US$767.5 million of revenue and US$108.8 million of earnings by 2029, so they read today’s guidance very cautiously. Use that gap in expectations as a prompt to compare several viewpoints before deciding how this new quarter changes your own story for the stock.
Explore 4 other Amphastar Pharmaceuticals fair value estimates, including one that suggests as much as 17% downside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment outcomes rarely come from following the herd, so go with your instincts.
- A great starting point for your Amphastar Pharmaceuticals research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Amphastar Pharmaceuticals. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Amphastar Pharmaceuticals' overall financial health at a glance.
Looking For More Amphastar Pharmaceuticals Sized Ideas?
If the Amphastar Pharmaceuticals story has sharpened your thinking but you want a wider bench of candidates, the Simply Wall St Screener can help you quickly filter the market by quality, balance sheet strength and income potential so you are not relying on a single stock.
- For investors who care most about resilient balance sheets and solid fundamentals, the list of solid balance sheet and fundamentals (24 results) can surface businesses that match those priorities.
- If your focus is on stability first, the 31 resilient stocks with low risk scores can help you narrow in on companies with lower overall risk profiles.
- For readers hunting for underappreciated quality, the 20 high quality undiscovered gems can point you toward less crowded opportunities that still meet strict financial filters.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com