
What Certara (CERT) Narrowed Guidance Means For Shareholders
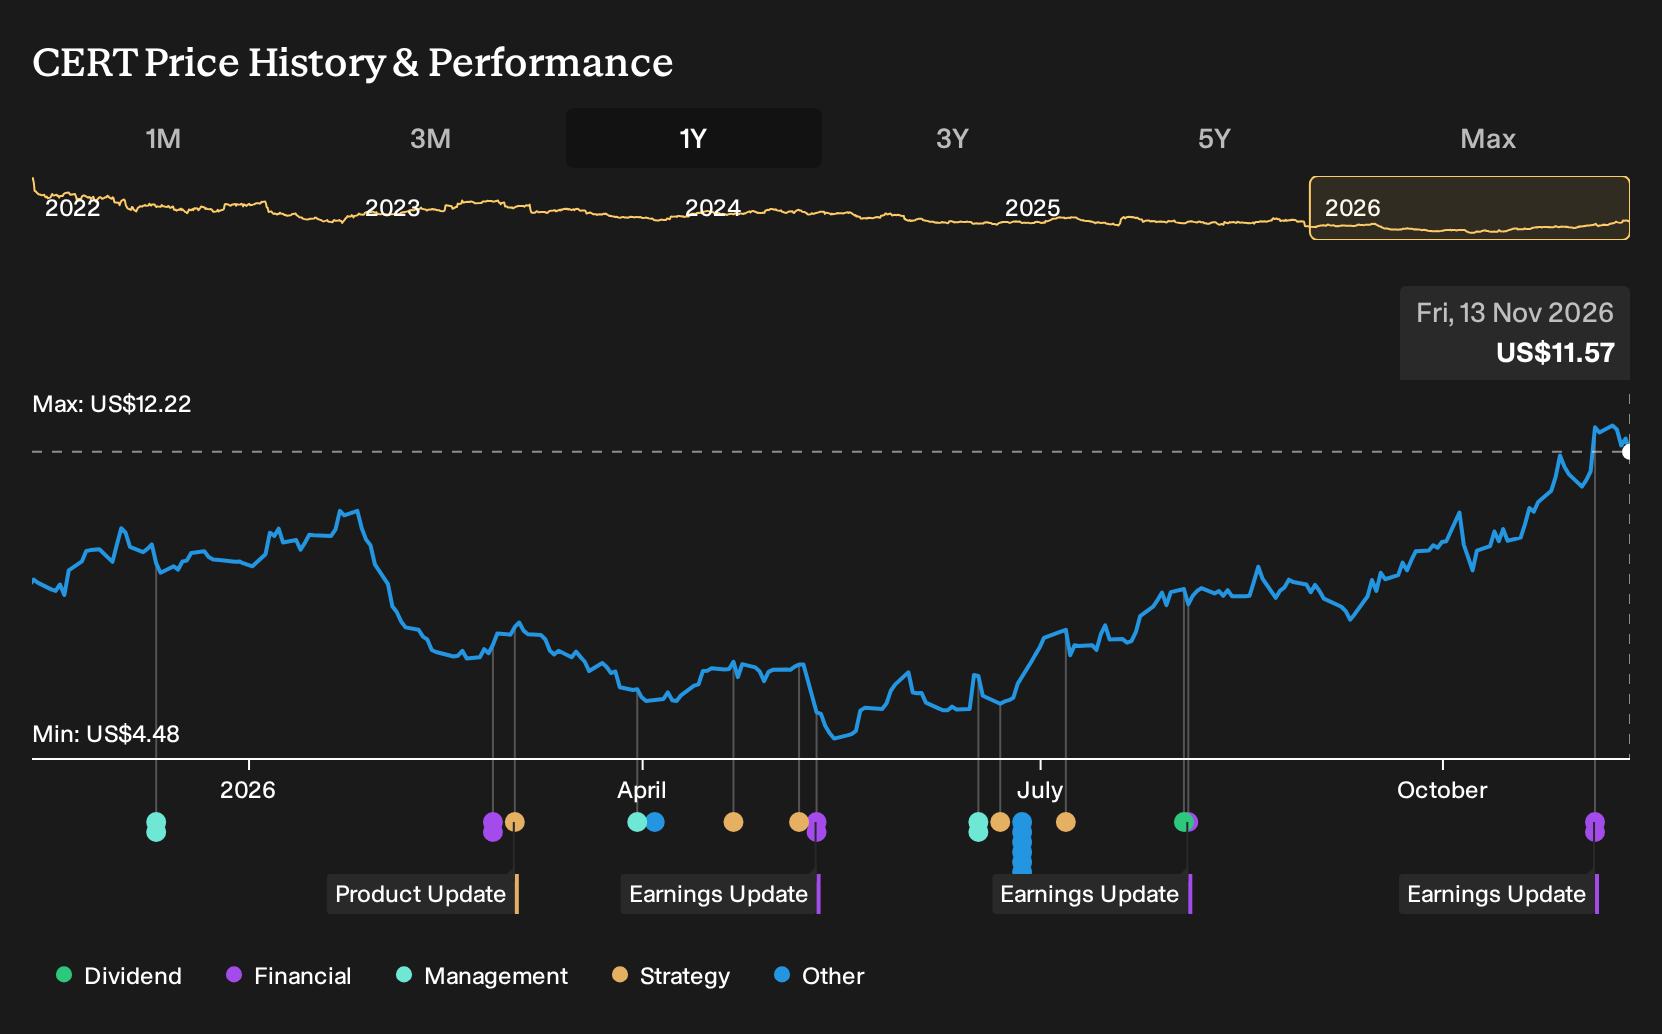
- Certara reported third quarter 2026 sales of US$94.9 million and net income of US$5.59 million, while the first nine months showed sales of US$282.26 million and a net loss of US$58.44 million. Management narrowed full year 2026 revenue growth guidance to a range of 2% to 3%.
- The combination of a profitable quarter, a loss over the nine month period, and a tighter revenue outlook highlights the pressure on Certara to manage costs and convert regulatory and product momentum into more consistent earnings performance.
- Next, the focus turns to how Certara's narrowed 2026 revenue growth range could reshape the existing investment narrative around its biosimulation business.
Compare Certara's tighter 2026 guidance with peers by scanning for biosimulation and healthcare software companies showing steadier top line trends in the 36 healthcare AI stocks.
Certara Investment Narrative Recap
To own Certara, you need to believe its biosimulation platforms can turn regulatory traction and software adoption into consistent profit, not just patchy quarters. The latest results show a profitable Q3 but a loss over nine months, with full year 2026 revenue expected to grow only 2% to 3%. That combination keeps the short term focus on execution rather than narrative.
The most important near term catalyst is Certara converting its regulatory wins and cloud products into steadier bookings and higher margin software revenue. The biggest risk is that rising investment in R&D, AI tools, and acquisitions keeps expenses high while pharma customers remain cautious, which would prolong losses without a clear payoff.
The analyst consensus narrative on Simply Wall St leans heavily on catalysts such as the EMA qualification for Simcyp and the upcoming AI enabled MIDD and CertaraIQ QSP platforms. The tightened 2026 revenue range places a brighter spotlight on whether these products can support more predictable top line trends while the business is still absorbing higher operating costs.
Slow pharma adoption, customer concentration, and pressure on R&D budgets already feature as key risks in that narrative. With nine month figures showing a net loss of US$58.44 million, investors now have fresher evidence to test whether the promised earnings improvement and operating leverage are keeping pace with spending or whether expectations need to be reset.
Certara's narrative projects US$428.5 million revenue and US$42.7 million earnings by 2029. This reflects analyst expectations for fairly flat yearly revenue trends over the next few years and an earnings swing of about US$63.9 million from current earnings of a US$21.2 million loss.
Discover how Certara's fair value indicates a 4% potential downside to its current price, which leaves little room for error.
Exploring Other Perspectives
The sharpest contrast in the bearish Certara narrative concerns services weakness. The lowest analysts were already modeling revenue drifting to about US$409.0 million by 2029 with earnings near US$31.2 million. You can see how the new 2% to 3% growth range might push those already cautious views even further, so it helps to compare several viewpoints rather than rely on a single story.
Explore 2 other Certara fair value estimates, including one that suggests there could be as much as 27% downside from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis.
- A great starting point for your Certara research is our analysis highlighting 1 key reward that could impact your investment decision.
- See our latest analysis for Certara. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Certara's overall financial health at a glance.
Looking For More Ideas Beyond Certara?
If the Certara story leaves you wanting a broader watchlist, it can help to line it up against other opportunities that match your risk appetite, income needs, or balance sheet preferences.
- For investors hunting for mispriced quality, compare Certara with companies that score well on fundamentals by scanning a 32 high quality undervalued stocks.
- If capital preservation and stability sit higher on your list, weigh Certara against businesses with stronger finances using a list of solid balance sheet and fundamentals (24 results).
- Those looking for potential income alternatives can contrast Certara with high yielding payers by reviewing a set of 6 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com