
Rambus (RMBS) Could Be 42% Undervalued As AI Driven Growth Lifts Revenue
Rambus (RMBS) just reported third quarter 2026 results, with revenue up 22% year over year on demand for AI focused memory solutions and data center products.
Rambus shares closed at $82.23, and despite the strong third quarter update and new PCIe IP partnership showcase with Silicon Creations, the stock is down 17.17% on a year-to-date share price basis while the 1-year total shareholder return is down 13.67%. However, the 3-year and 5-year total shareholder returns of 24.18% and 201.98% suggest longer term holders have still seen meaningful gains even as near-term momentum has softened.Scan Rambus alongside other AI infrastructure plays by reviewing the hand picked 53 AI infrastructure stocks that are also tied to data center and memory demand.
Rambus now trades well below published analyst targets after a sharp pullback, yet recent AI driven momentum is fresh in investors’ minds. Is that discount caution well placed, or is it mispricing the story ahead of valuation work?
Most Popular Narrative: 41.9% Undervalued
The latest fair value from the analyst consensus Narrative on Simply Wall St sits at $141.57 for Rambus, well above the $82.23 last close. This frames the current pullback as a sizeable discount if those assumptions hold.
The upcoming industry transition to MRDIMM technology is now framed around a modeled US$600 million market by around 2028 and a shift in meaningful Rambus MRDIMM revenue into 2027 as next generation Intel and AMD platforms ramp. This extends the potential for higher content per module and supports a longer multi year runway for product revenue and cash from operations.
See why 37 investors see Rambus as 42% undervalued.
Result: Fair Value of $141.57 (UNDERVALUED)
Still, the Rambus story only holds if margin pressure eases and the antitrust subpoena does not translate into costly or distracting legal fallout.
Find out about the key risks to this Rambus narrative.
Another View: Rambus On Earnings-Based Value
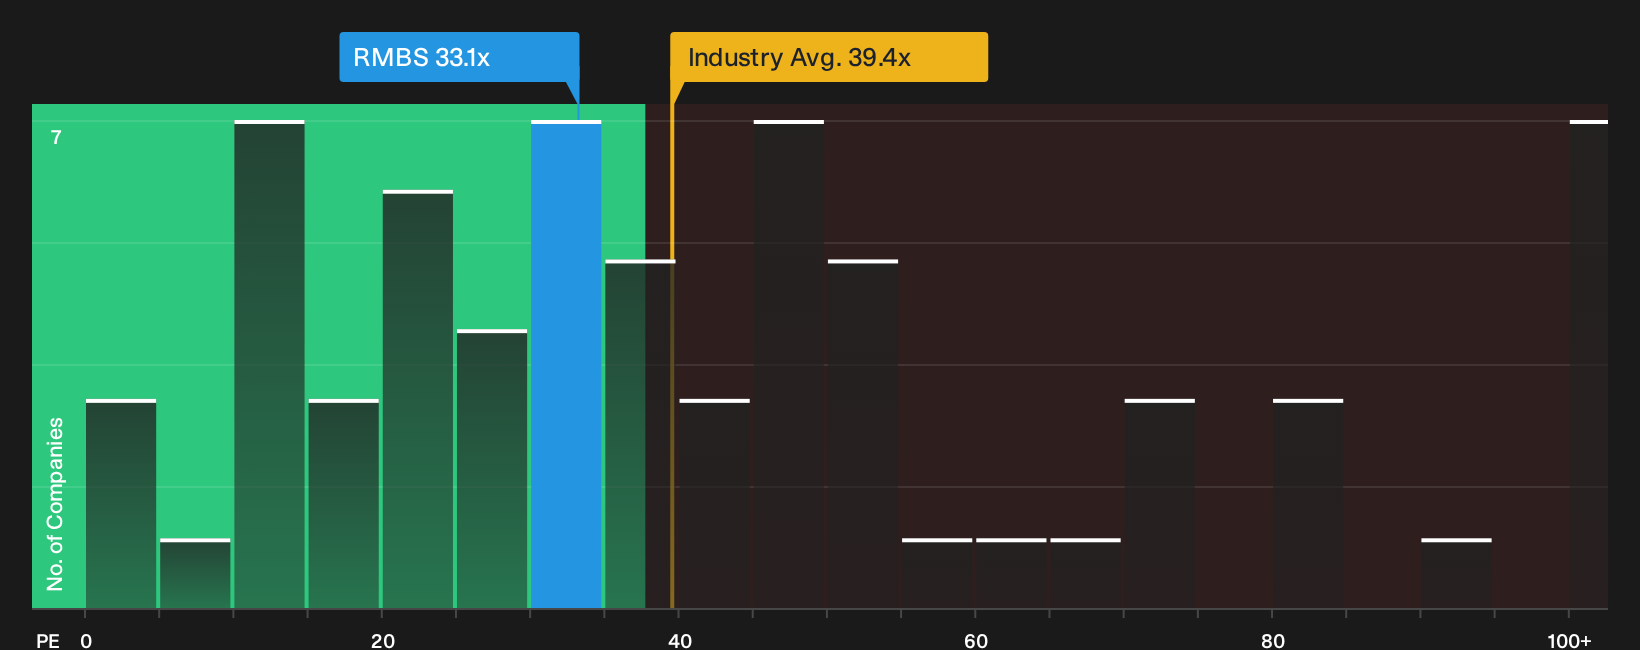
The first narrative leans heavily on long range earnings forecasts and a $141.57 fair value. A simpler check looks at Rambus through its current P/E of 33.1x versus a fair ratio of 34.1x and a peer average of 38.8x. That points to only a modest discount. Does that narrower gap change how you frame the upside story?
For investors weighing these conflicting valuation signals, it can help to see how the P/E relationship to peers and the fair ratio has shifted over time, and what that implies for future rerating risk or room for multiple expansion. See what the numbers say about this price — find out in our valuation breakdown.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Rambus for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment across Rambus is split, which is exactly why it helps to press into the underlying data yourself and decide quickly where you land. To ground that view in concrete positives, start with the 4 key rewards
Looking for more Rambus-like investment ideas?
Rambus may be front of mind today, but your next strong idea probably sits somewhere you have not checked yet. Use the Simply Wall St screener to widen your field of vision and avoid relying on just one story.
- Target quality at a discount by scanning the 32 high quality undervalued stocks that pair solid fundamentals with prices that have not fully reflected them yet.
- Prioritise resilience by running through a 31 resilient stocks with low risk scores that filters for sturdier balance sheets and lower overall risk scores.
- Get ahead of the crowd by reviewing a 20 high quality undiscovered gems that focuses on under-the-radar businesses with stronger financial profiles than their visibility suggests.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com