
Has Hamilton Lane (HLNE) Fallen Far Enough To Match Its Earnings?
Hamilton Lane has seen its share price fall 31.4% year to date even as the business reports growing assets under management and a higher dividend. This puts the spotlight squarely on whether the current valuation is in line with its earnings power. With the stock now trading at US$93.73, the key issue is how much of the recent news is already reflected in that price.
- The stock is down 31.4% so far in 2026. Any view on Hamilton Lane today hinges on whether that drop has moved the price closer to or further away from what its earnings support.
- Management has lifted the quarterly dividend to US$0.60 per share and highlighted fee related earnings and recurring revenue as support for the payout. This can influence how investors think about the durability and valuation of those earnings.
- There is a second opinion on Hamilton Lane worth weighing. See what analysts think Hamilton Lane's shares could be worth.
The issue now is whether Hamilton Lane's current share price is justified by the earnings it is generating today and is expected to produce over time.
If you are comparing Hamilton Lane with other income-focused stocks that offer sizeable yields, it can be useful to evaluate it alongside companies in the 6 dividend fortresses.
Does Hamilton Lane Look Fairly Valued on Earnings?
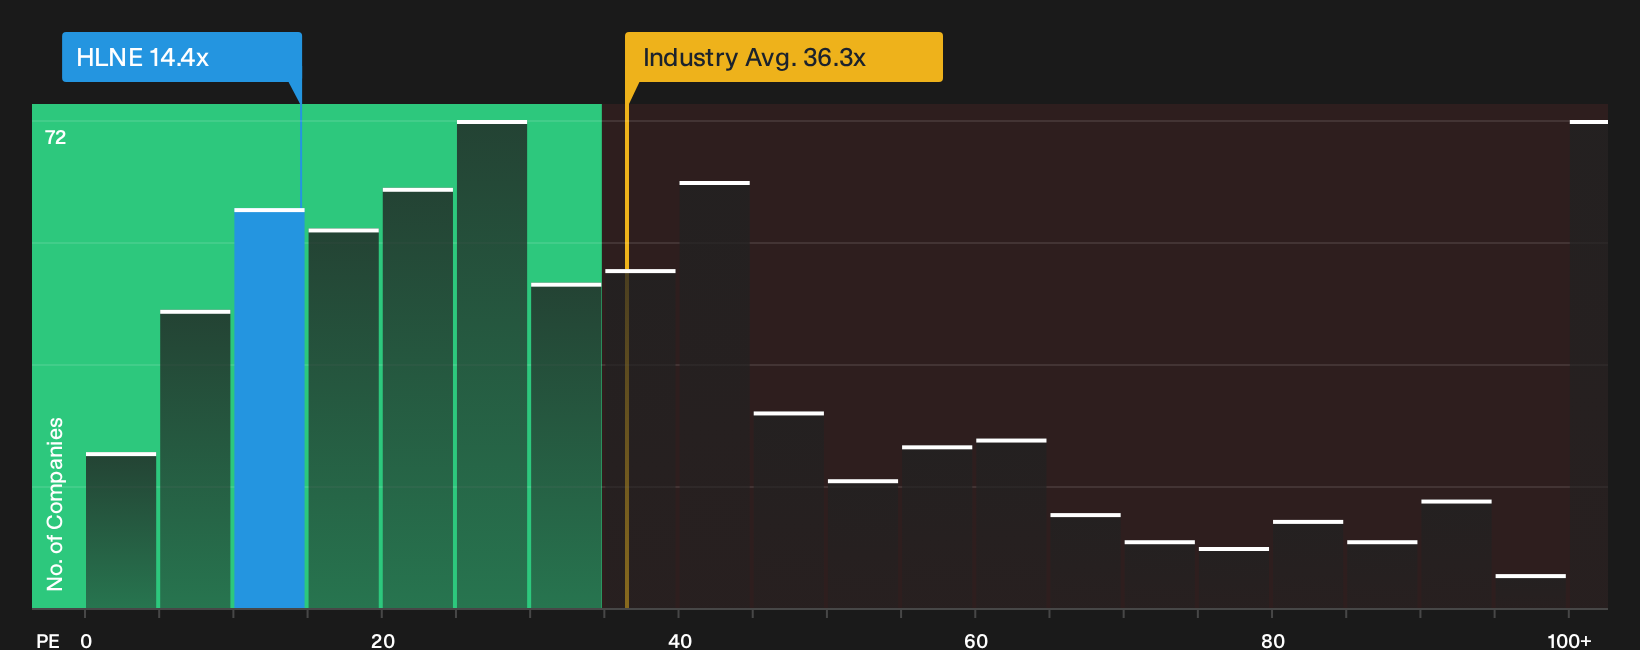
P/E is usually a useful lens for Hamilton Lane because earnings and fee income matter more to equity holders than asset values on the balance sheet. On this yardstick, the stock trades on a P/E of 14.4x, compared with about 18.1x for close peers and roughly 36.3x for the wider Capital Markets industry. The current level also sits close to what a tailored model suggests might be appropriate given Hamilton Lane’s mix of growth, margins, size and risk. As a result, the ratio does not signal a glaring discount or a stretched premium on earnings alone.
Because the dividend increase announced in the Q2 2027 results leans on fee related earnings, the present P/E of 14.4x effectively prices that earnings base at a slight markdown to similar companies despite the income focus. For anyone weighing the recent share price pullback against those earnings, the multiple points to a stock that is roughly in line with what the company specific model would imply rather than one that looks clearly mispriced on the headline ratio. Explore the numbers behind Hamilton Lane's P/E valuation.
The Hamilton Lane Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Hamilton Lane take the valuation puzzle a step further and spell out what kind of future path for Hamilton Lane's growth, margins and earnings would justify a much higher or much lower share price than today. Instead of stopping at a single P/E or model output, Narratives unpack the specific expectations that number relies on so you can track how the actual business performance aligns with those assumptions over time on the Community page.
One of the top community narratives on Hamilton Lane: 47% undervalued
According to John_Eric, a Simply Wall St Community investor who wrote the Narrative, the key question is what recent insider and institutional buying might signal.
"While analysts were lowering estimates and investors were heading for the exits, Executive Co Chairwoman Hartley Rogers repeatedly bought shares in the open market..."
Discover why this Narrative puts Hamilton Lane at 47% undervalued.
Hamilton Lane's valuation still hinges on who is steering the ship
The next issue to check is who actually drives Hamilton Lane's decisions and how their pay is structured, because incentives can shape outcomes in ways a P/E ratio never shows. See who runs Hamilton Lane and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com