
Cleveland Cliffs (CLF) Stock May Be Discounted After Fresh Labor Deal News
Cleveland-Cliffs has seen its stock move around over the past few years, and the latest bounce puts fresh focus on what investors are really paying for in terms of its sales base. With the share price at US$12.65 as of the last close, the key issue is how that market value lines up against the revenue the business generates.
- Over 5 years the stock has fallen 42.4%, which puts sharper pressure on the question of whether the current valuation still matches the strength of Cleveland-Cliffs' sales.
- Fresh four-year labor agreements with the United Steelworkers covering around 12,000 employees may support more predictable production and costs, which can shape how reliably future sales turn into earnings and cash.
- The analysts covering Cleveland-Cliffs have run their own numbers. See what analysts think Cleveland-Cliffs's shares could be worth.
The stock's next move may depend on whether the current share price is well supported by the level and quality of Cleveland-Cliffs' sales.
If you want to stress test this same sales question against a wider set of steel and materials stocks, compare Cleveland-Cliffs with solid balance sheet and fundamentals stocks screener (24 results).
Is Cleveland-Cliffs a Bargain on Sales?
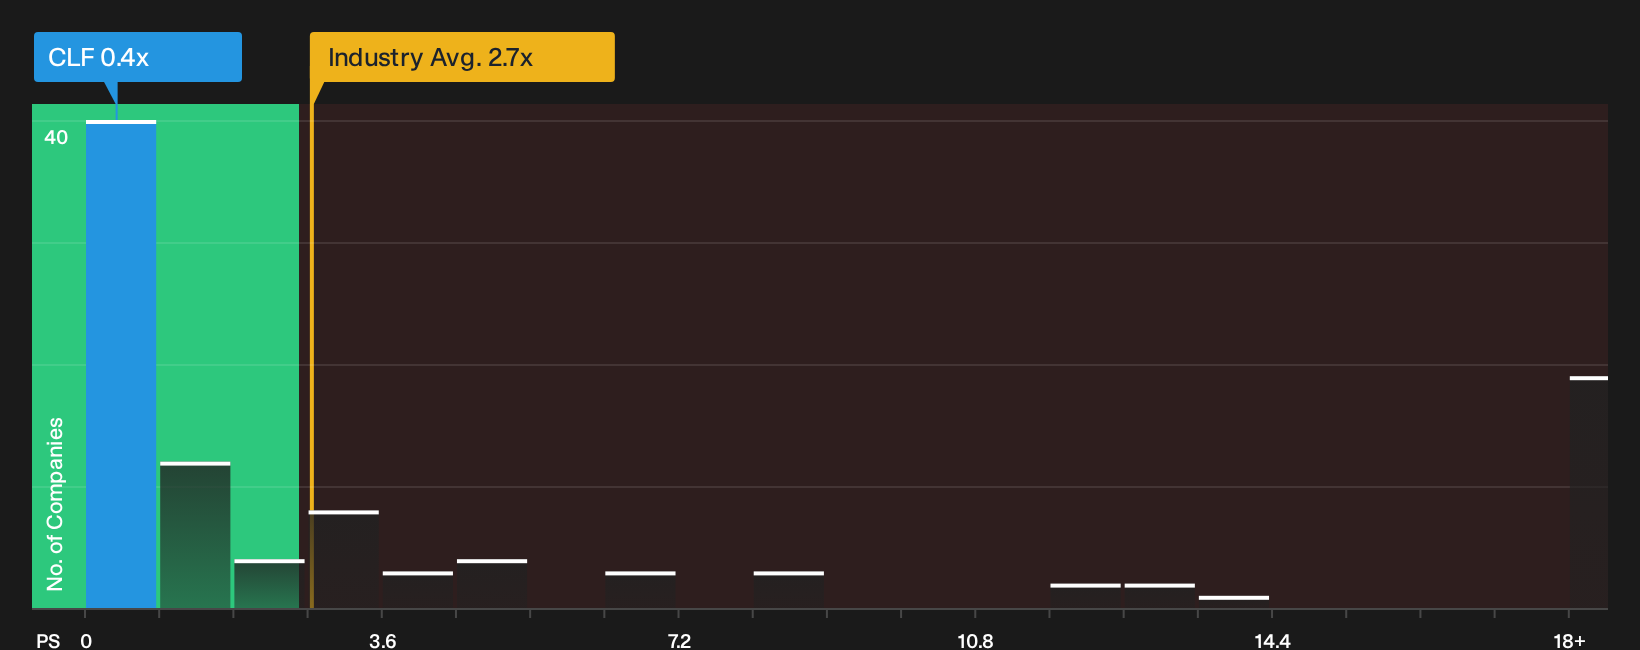
P/S is a useful lens for Cleveland-Cliffs because investors are often weighing what they pay for each dollar of steel revenue in a sector where earnings can swing sharply. At a P/S ratio of 0.4x, the stock changes hands at a fraction of the 2.7x industry average and the 1.5x level seen across closer peers in metals and mining. That is a wide gap for a business with a large, established sales base.
Because the current multiple sits well below the level suggested by a fair-value P/S framework that incorporates Cleveland-Cliffs' size, risk profile and sector economics, the shares screen as undervalued on this metric. The recent four year labor agreements that cover around 12,000 workers help frame that discount, because more labor stability provides a clearer line of sight on how existing contracts might translate into future revenue. Yet the valuation still reflects a steep markdown against peers. Explore the numbers behind Cleveland-Cliffs's P/S valuation.
The Cleveland-Cliffs Narrative: What Would Justify Today's Price?
Narratives pick up where that P/S puzzle leaves off for Cleveland-Cliffs' stock. They outline which potential paths for future growth, margins and earnings would need to occur for the current valuation to appear too low or too high. These narratives are available on Simply Wall St's Community page, where you can see the specific future that any single ratio or model figure quietly relies on, and then judge over time whether reality is matching that script.
The bullish and bearish Narratives on Cleveland-Cliffs are not far apart, yet they focus on very different pressure points for the business.
Bull case: 11% undervalued
This is drawn from the analyst consensus Narrative on Simply Wall St. It leans on trade support and cost work.
"Sustained enforcement of U.S. steel tariffs together with melted and poured rules is keeping imports around multi year lows. This supports higher utilization for Cleveland-Cliffs and can feed into firmer average selling prices and revenue…"
Discover why this Narrative puts Cleveland-Cliffs at 11% undervalued.
Bear case: 5% overvalued
This view comes from the bearish analyst Narrative on Simply Wall St. It leans heavily on energy and fuel risk.
"Although Cleveland-Cliffs highlights ongoing unit cost reductions and integration benefits, the first quarter 2026 energy spike that added about US$80 million to costs shows how volatile natural gas, electricity and industrial gases can quickly erode EBITDA and net margins if similar events recur…"
Explore why this Narrative puts Cleveland-Cliffs at 5% overvalued.
One more side of Cleveland-Cliffs that could change your view
Cleveland-Cliffs is not just about its P/S gap and labor deals, because internal checks have also surfaced potential pressure points that investors often overlook until they matter most. Take a closer look at 1 major warning sign before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com