
Webull (BULL) Shares Just Moved, So What Is Going On?
Recent earnings from Institutional Financial Markets, Inc. put trading platforms in focus again, and Webull (BULL) is drawing attention as investors weigh its role in a shifting brokerage ecosystem.
Webull has caught a short term bid, with a 1 day share price return of 4.44% and a 7 day gain of 5.28%. However, the stock is still down 14.66% over 30 days, and the 1 year total shareholder return has fallen 39.98%. This suggests recent momentum is more of a bounce than a sustained trend, as investors reassess risk around online brokerages after weaker results from peers like Institutional Financial Markets.
Scan beyond Webull and evaluate other broker and fintech names under pressure by benchmarking them against our curated list of 32 high quality undervalued stocks.
Webull is building a broad digital brokerage and wealth platform, yet the share price has fallen hard over the past year before this recent bounce. Is investors’ caution now overdone, or still too generous for what you get at today’s valuation?
Most Popular Narrative: 54% Undervalued
Webull last closed at $5.18, while the analyst consensus Narrative on Simply Wall St points to a fair value of $11.25. This frames a wide gap that hinges on aggressive growth and margin assumptions discounted at 7.89%.
Ongoing expansion into new international markets, including recent launches in Canada, Latin America, and Europe, is rapidly diversifying Webull's customer base and driving robust growth in assets under management (AUM), which supports future revenue and top-line growth.
The successful launch and acceleration of subscription-based offerings such as Webull Premium and paid analytics products are already exceeding targets, combining higher daily trading activity and increased average revenue per user (ARPU) to boost net margins and recurring revenue stability.
See why 40 investors see Webull as 54% undervalued.
That fair value of $11.25 comes from analysts modelling revenue growth of roughly 24% a year, profit margins moving from 6.3% to about 22.7%, and applying a future P/E of around 30x while using a 7.89% discount rate to translate those forecasts into today’s dollars.
Under those inputs, the current share price sits well below the $11 analyst target cited in the company data. However, the model also assumes earnings rising from $42.6 million today to almost $293.3 million by 2029, which is a steep climb that investors need to judge against their own expectations for Webull’s brokerage and wealth platform.
Result: Fair Value of $11.25 (UNDERVALUED)
Still, that story can break if China related regulatory scrutiny tightens further or if heavier competition in low fee brokerage erodes Webull’s pricing power.
Find out about the key risks to this Webull narrative.
Another View: Webull Looks Expensive On Earnings Today
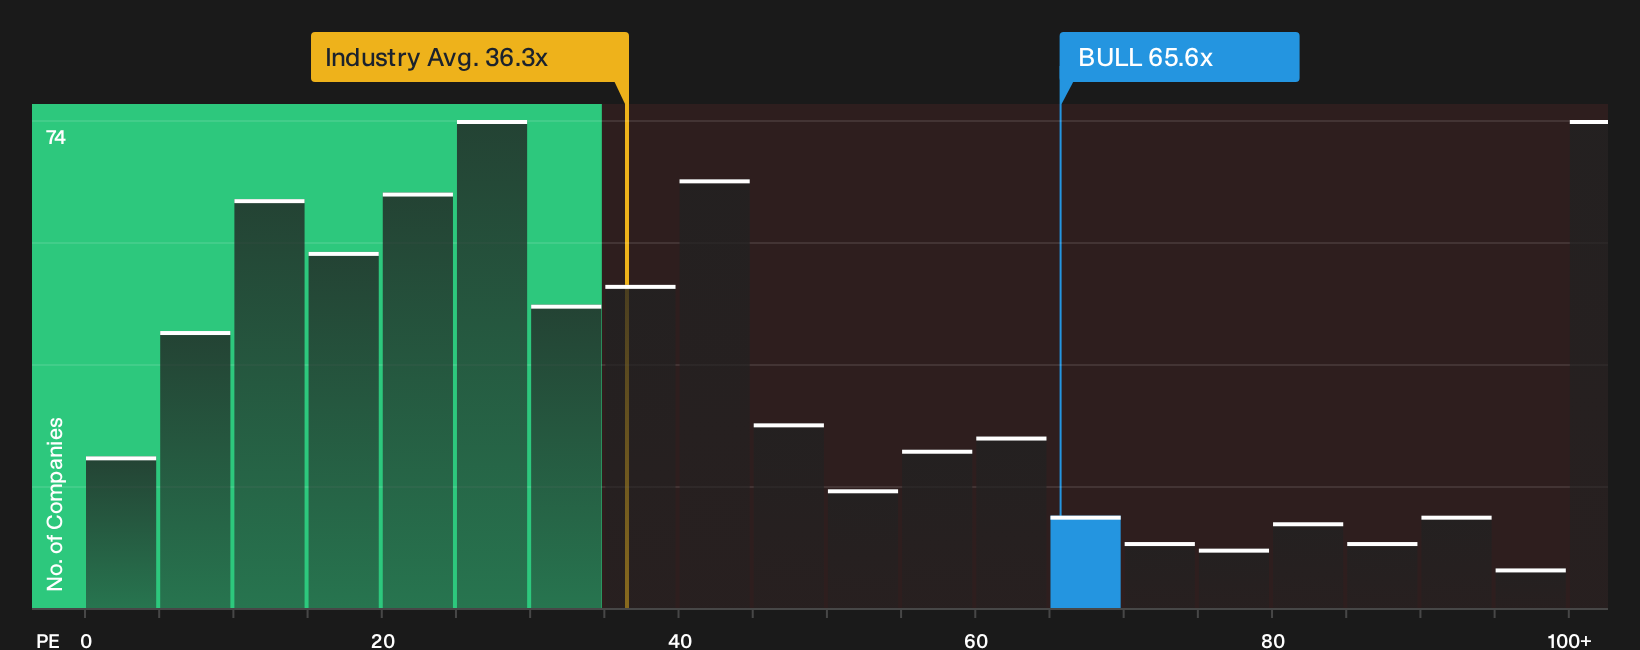
On current numbers, Webull screens as pricey. The stock trades on a P/E of 65.6x, compared with about 36.3x for the US Capital Markets sector and 13.4x for closer peers. The fair ratio sits at 37.6x, which points to valuation risk if sentiment cools before earnings catch up.
That spread means investors are already paying a premium multiple that could compress toward the fair ratio or peer levels if growth expectations change. The question is whether the analyst upside story is strong enough for you to stay comfortable with that kind of gap.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Webull clearly splits opinion. This is exactly why the next move should be yours. Weigh the upside story against the red flags and review the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Webull?
If Webull has you thinking harder about risk and reward, broaden your watchlist now so you are not left reacting after the next big move.
- Target potential mispricing by scanning companies that screen as high quality yet undervalued through our dedicated 32 high quality undervalued stocks.
- Strengthen your income stream by reviewing a curated set of higher yielding businesses in the 6 dividend fortresses.
- Prioritise resilience by focusing on companies with healthier finances and fundamentals using the list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com