
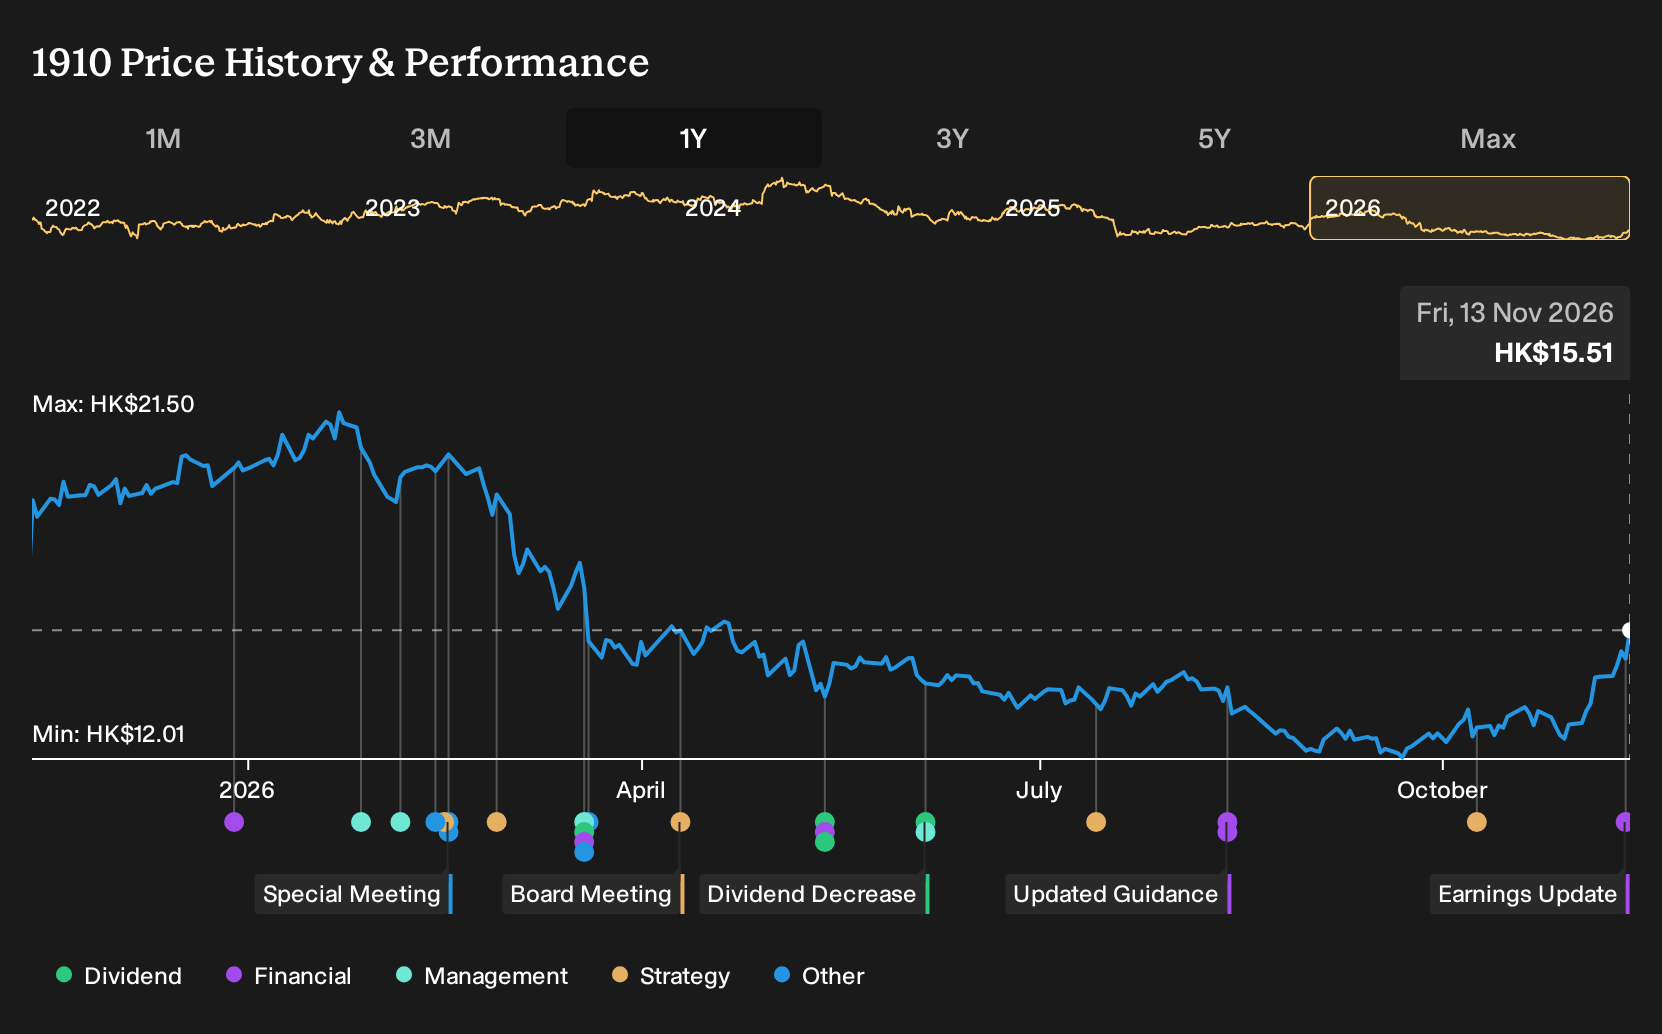
Why Samsonite Stock Is Up 5.3% And What's Next
- Samsonite Group reported Q3 2026 sales of US$872.7 million, flat year on year, while net income fell to US$58.1 million and earnings per share from continuing operations softened.
- The business paired modest constant currency net sales growth with the completion of the BÉIS acquisition and a US$50 million share repurchase plan, signaling a sharper focus on brand mix and capital deployment.
- We will now consider how Samsonite Group's buyback announcement could reshape its investment narrative around cash generation and capital priorities.
Scan how Samsonite Group's capital return story compares with other companies buying back shares and tightening cash discipline by reviewing the 210 resilient stocks with low risk scores in this space.
Samsonite Group Investment Narrative Recap
To own Samsonite Group, you need to be comfortable with a travel and lifestyle business that is leaning on brand mix, premium products and direct to consumer channels while earnings are under pressure. Q3 2026 kept sales steady at US$872.7 million but net income and EPS weakened, so profit momentum is not the near term support.
The analyst consensus Narrative on Simply Wall St leans on gradual earnings growth and cash generation, yet the latest nine month numbers show net income down to US$149 million from US$191.7 million. That keeps the main near term risk firmly on margins and cost inflation rather than demand recovery, so the Q3 print looks incrementally negative but not thesis breaking.
The most relevant fresh announcement is the US$50 million share repurchase plan alongside the BÉIS acquisition. This capital return step arrives as diluted EPS from continuing operations in Q3 moved from US$0.053 to US$0.042, so the timing puts more attention on how reliably Samsonite Group can generate free cash to fund buybacks while servicing its debt.
For catalysts, BÉIS and lifestyle bags, plus ongoing DTC and e commerce mix shift, still align with the drivers flagged in the analyst consensus Narrative on Simply Wall St. The repurchase plan now sits beside those operational levers as a test of execution discipline. If cost pressures, regional weakness or higher distribution expenses persist, investors will likely focus more on balance sheet flexibility than on incremental capital returns.
Samsonite Group's narrative projects US$3.8b revenue and US$268.3 million earnings by 2029. This implies 3.0% yearly revenue growth and an earnings increase of about US$6.6 million from US$261.7 million today.
Uncover why Samsonite Group's fair value indicates a 22% potential upside to its current price, a gap that could narrow quickly if sentiment improves.
Exploring Other Perspectives
Lowest analysts put more weight on execution risk around BÉIS. They were only projecting US$3.8b of revenue and about US$255 million of earnings by 2029, below consensus, before this Samsonite Group update. You can treat that as a more cautious script and compare it with your own view on the new buyback and recent results.
Explore 2 other Samsonite Group fair value estimates, including one that suggests it could be worth just HK$19.00!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Samsonite Group research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Samsonite Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Samsonite Group's overall financial health at a glance.
Looking for more Samsonite Group style investment ideas?
Once you have a handle on Samsonite Group and its buyback story, you can compare it with other listed businesses that have clear balance sheets, income streams, or valuation hooks using the Simply Wall St Screener.
- If capital protection matters most to you, scan a 210 resilient stocks with low risk scores that aims to pair steadier fundamentals with lower risk profiles.
- For investors who care about income, check out a 220 dividend fortresses that currently offers higher yields while still passing basic quality checks.
- If you want ideas that are not heavily followed, widen your watchlist with a 559 high quality undiscovered gems that combines solid financials with quieter ownership and coverage.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com