
Verisk Analytics (VRSK) Could Be 170% Overvalued On Reaffirmed Revenue And Dividend Guidance
Verisk Analytics (VRSK) just released third quarter results, reaffirmed full year revenue guidance of US$3.19b to US$3.24b, and confirmed its 2026 dividend outlook, giving investors a fresh snapshot of earnings quality and cash returns.
Verisk Analytics shares have climbed sharply in recent weeks, with a 30 day share price return of 15.1% and a 90 day gain of 14.4%. This comes even though the year to date share price return is down 6.0% and the 1 year total shareholder return is down 2.8%, suggesting momentum has picked up recently as investors weigh the reaffirmed revenue and dividend guidance against a weaker multi year total shareholder return profile.
Spot fresh momentum in Verisk Analytics, and then widen your hunting ground by scanning a curated set of 31 resilient stocks with low risk scores that balance resilience with return potential.After a sharp short term rebound in Verisk Analytics on the back of steady guidance and dividends, the central question now is simple: Does the current price still leave enough upside to justify the risk?
Most Popular Narrative: 170% Overvalued
Verisk Analytics last closed at $207.82, while the leading narrative pegs fair value near $76.85. This implies a steep valuation gap at today’s price.
According to Esteban, an investor in the Simply Wall St Community who wrote the narrative, the appeal of Verisk Analytics sits in the stability of its insurance data franchise rather than rapid expansion.
Verisk Analytics is a regulatory-grade data toll on the US property & casualty insurance industry, monetized through ~83% subscription revenue with ~92% client retention. VRSK's narrow-moat franchise produces FCF with an unusually high degree of predictability, durable enough to justify a 15× exit multiple at a 35% margin of safety.
See why 7 investors see Verisk Analytics as 170% overvalued.
Result: Fair Value of $76.85 (OVERVALUED)
Still, the story around Verisk Analytics could shift if regulatory rules change for US insurance data or if insurers push back on pricing for its analytics services.
Find out about the key risks to this Verisk Analytics narrative.
Another View: Cash Flow Signals For Verisk Analytics
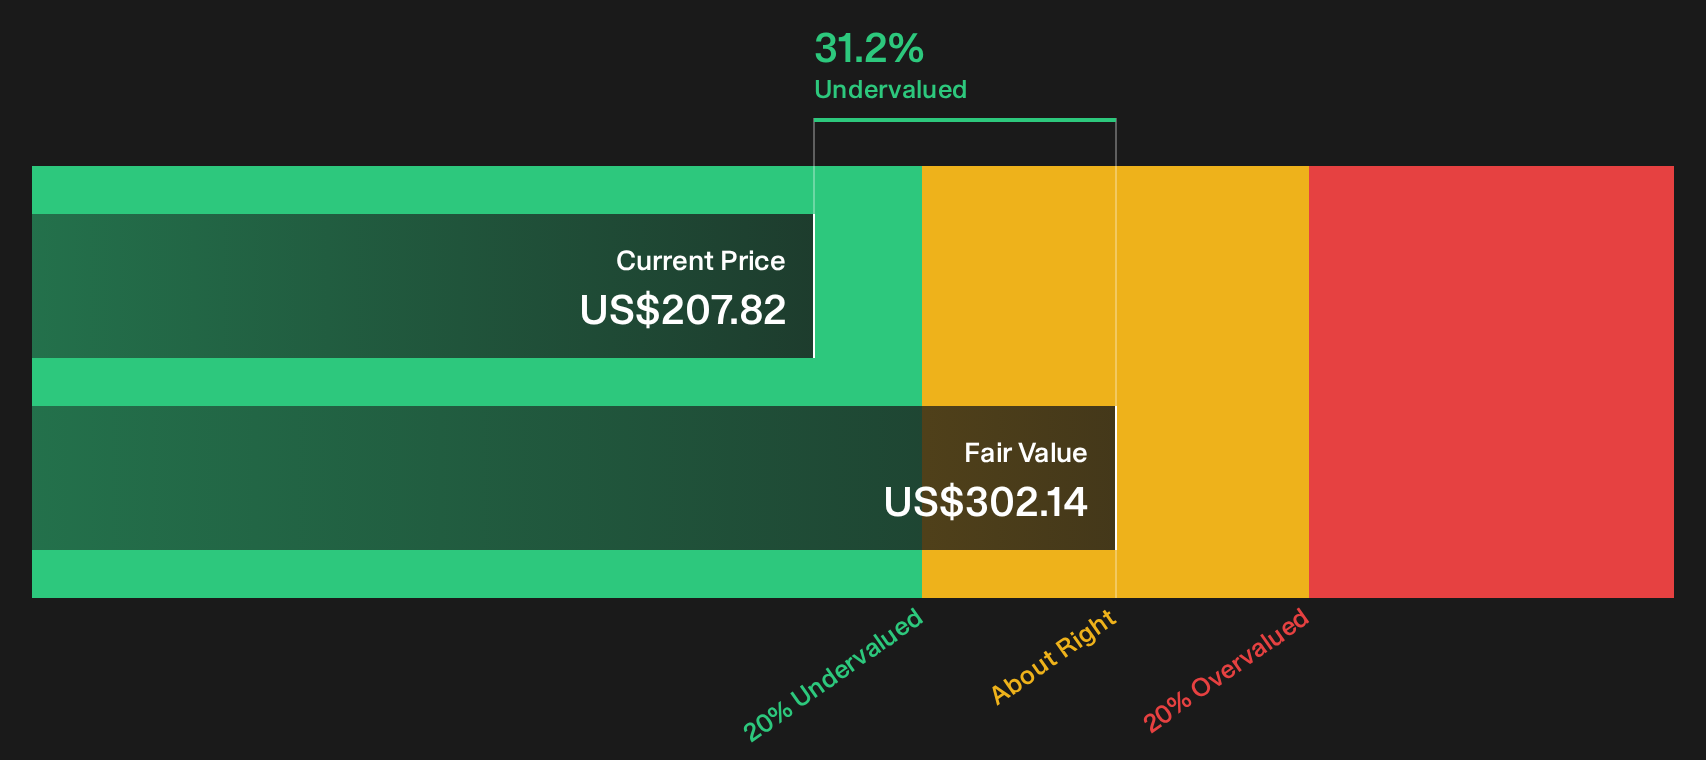
That 170% overvaluation call is based on a fair value of $76.85. A different tool, the Simply Wall St DCF model, points in the opposite direction and estimates Verisk Analytics future cash flows at $302.14 per share, which suggests the current $207.82 level may be undervalued instead.
The split is stark. One approach leans on a 15x exit multiple and a margin of safety; the other models cash flows directly and lands far above today’s quote. As an investor you are left asking which set of assumptions feels more realistic for your own risk tolerance.
Look into how the SWS DCF model arrives at its fair value.
Next Steps
With both caution and optimism in the Verisk Analytics story, act while the data is fresh and test the bullish and bearish angles against your own thesis with 2 key rewards and 1 important warning sign
Looking for more investment ideas beyond Verisk Analytics?
If Verisk Analytics has sharpened your thinking, do not stop here. Broaden your watchlist with fresh ideas sourced from focused screeners built around clear fundamentals.
- Target stability first by scanning a list of solid balance sheet and fundamentals (24 results) that can help anchor your portfolio when conditions feel unpredictable.
- Seek value on your terms with a 32 high quality undervalued stocks that highlights strong businesses trading below their estimated worth.
- Hunt for early-stage potential through a 13 elite penny stocks with strong financials that filters for smaller companies where the story is still taking shape.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com