
How Investors Are Reacting To Southwest Gas Holdings (SWX) Weak Quarterly Earnings
- Southwest Gas Holdings released third quarter 2026 results, with sales of US$298.18 million and net income of US$12.78 million, and reported basic and diluted earnings per share from continuing operations of US$0.18.
- The sharp year over year gap between third quarter net income of US$12.78 million and the prior period’s US$262.63 million highlights how current earnings compare with the longer term growth profile analysts had been expecting.
- We will look at how Southwest Gas Holdings' investment narrative is affected when current earnings sit far below last year’s profit levels.
Scan beyond Southwest Gas Holdings and compare this earnings reset with hand-picked utilities showing stronger consistency and balance sheet support through the list of solid balance sheet and fundamentals (24 results).
Southwest Gas Holdings Investment Narrative Recap
To stay invested in Southwest Gas Holdings, you need to be comfortable with a regulated utility that leans heavily on rate cases and long duration capital projects like the US$2.3b Great Basin 2028 Expansion Project. The sharp reset in third quarter profit and softer nine month sales of US$1,241.46 million versus US$1,459.65 million a year ago puts more weight on execution and regulatory timing as the near term swing factors.
The key short term catalyst remains progress on approvals and cost recovery for the larger US$6.3b, five year utility capital program highlighted in the analyst consensus Narrative on Simply Wall St. The biggest current risk is that weaker earnings reduce flexibility around debt funded spend, in a business where debt is already not well covered by operating cash flow and customer demand faces long run decarbonization pressure.
The most relevant data point is the nine month earnings line. Southwest Gas Holdings posted net income of US$193.28 million for the period, compared with US$336.35 million a year earlier, with basic EPS from continuing operations at US$2.67. That shift matters because a lot of the long term story rests on stable utility style earnings and regulatory support.
For you as a shareholder, this makes execution on capital projects and regulatory frameworks less theoretical and more of a live test. Earnings volatility can feed back into balance sheet metrics, which already include debt that is not well covered by operating cash flow, and into how commissions view future rate requests that support the Great Basin expansion and broader capital plan.
Southwest Gas Holdings' narrative projects US$2.3b revenue and US$470.7 million earnings by 2029. This assumes 10.5% yearly revenue growth and an earnings increase of about US$186.4 million from US$284.3 million today.
Discover why Southwest Gas Holdings' fair value indicates a 7% potential upside to its current price that may not last much longer.
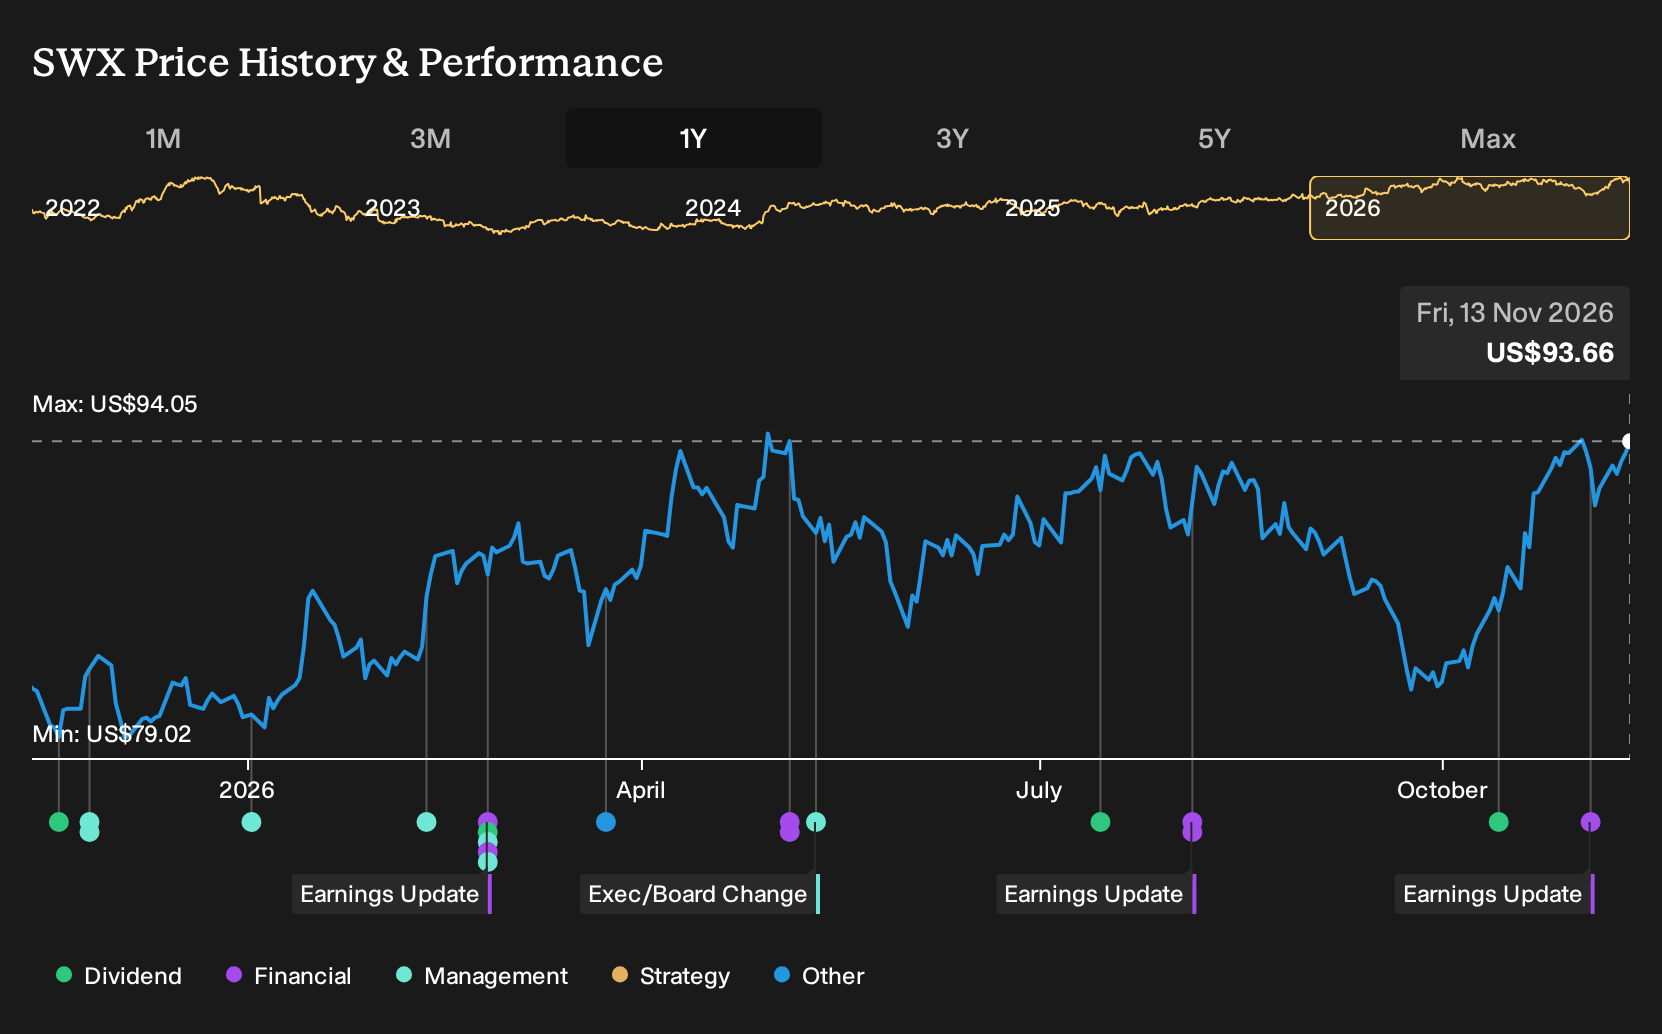
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community span roughly US$32 to just over US$100, so private investors there are clearly split on Southwest Gas Holdings. You see that dispersion set against fresh earnings pressure and regulatory dependence, which makes it worth exploring multiple viewpoints before relying on any single forecast.
Explore 2 other Southwest Gas Holdings fair value estimates, including one that suggests as much as 66% downside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Southwest Gas Holdings research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Southwest Gas Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Southwest Gas Holdings' overall financial health at a glance.
Looking for more investment ideas beyond Southwest Gas Holdings?
If this quarter's reset at Southwest Gas Holdings has you rethinking concentration risk, it can help to line it up against other businesses with very different profiles in terms of growth, balance sheet strength, and income potential.
- For investors who want potential upside without paying up for quality, scan through 20 high quality undiscovered gems that pair fundamental strength with limited market attention.
- If capital preservation and smoother portfolio swings matter more to you right now, filter the market for 31 resilient stocks with low risk scores that rank strongly on resilience metrics.
- Income focused investors can zero in on 6 dividend fortresses that combine higher yields with fundamentals that help support those payouts.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com