
How A $1 Billion Quarter At BioMarin Pharmaceutical (BMRN) Has Changed Its Investment Story
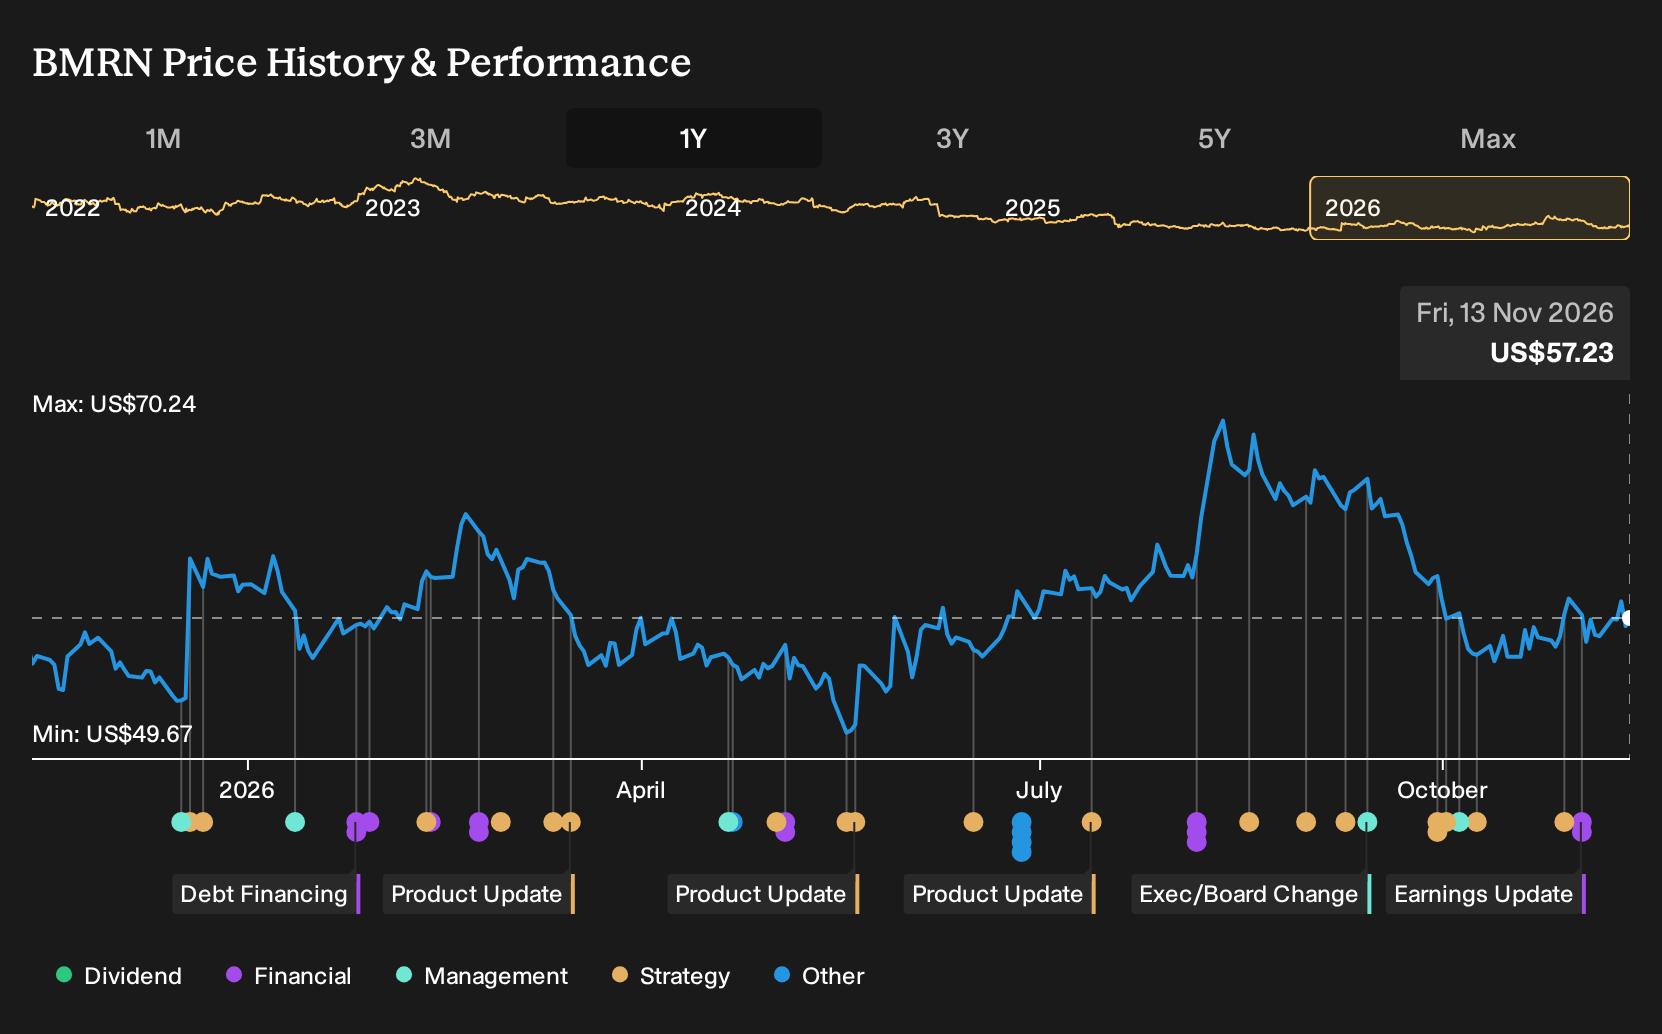
- BioMarin Pharmaceutical reported third quarter 2026 revenue of US$1,024.65 million and a wider net loss of US$122.83 million, and modestly lowered full year revenue guidance to a range of US$3.8 billion to US$3.9 billion.
- The business crossed the US$1 billion quarterly revenue threshold while its loss widened, highlighting the trade off between rare disease portfolio expansion and current profitability.
- The focus now turns to how BioMarin Pharmaceutical's rare disease investment narrative aligns with this first US$1 billion quarter and the reduced guidance.
BioMarin Pharmaceutical Investment Narrative Recap
To own BioMarin Pharmaceutical, you need to be comfortable with a rare disease model where each therapy serves a small group of patients and where R&D and manufacturing remain heavy. According to PKU, an investor in the Simply Wall St Community, the appeal is in specialised know how, global distribution and orphan drug protection. The widened quarterly loss and slightly lower 2026 revenue range keep the near term focus on expense discipline, integration of Amicus and how quickly new assets can offset higher costs.
The key catalyst many investors watch is clinical and commercial execution around the rare disease pipeline, including BMN 333 and other programs, alongside progress on extracting Amicus synergies. The biggest operational risk right now is that operating cash flow lags behind debt and integration needs, especially with guidance trimmed and recent net income volatility. If you believe BioMarin can convert its broader portfolio into steadier earnings while absorbing Amicus cleanly, these numbers look more like a timing question than a broken thesis.
The most relevant update is BioMarin Pharmaceutical’s third quarter 2026 earnings release, which confirmed US$1,024.65 million in quarterly revenue and a loss of US$122.83 million, plus a full year revenue range of US$3.8b to US$3.9b. That print ties directly into PKU’s focus on a rare disease business that carries high fixed costs and complex production but aims for long treatment durations and pricing power.
For catalysts, that report sits alongside management’s expectation of US$220 million in annual operating expense synergies from the Amicus acquisition by 2028, with integration planned to complete by mid 2027. Execution on those savings, together with upcoming data readouts from programs like BMN 440, BMN 333 and BMN 820, will likely shape how investors weigh BioMarin’s current loss making profile against its stated path to stronger cash generation and debt coverage.
PKU anchors a fair value of US$73.10 on a rare disease model that, in their view, can reach 15.0% annual revenue growth and a 15.0% future profit margin, supported by orphan drug protection, complex manufacturing know how, and long duration treatment use.
Uncover why BioMarin Pharmaceutical's fair value indicates a 28% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts lean hard into a single catalyst for BioMarin Pharmaceutical. They focus on margin expansion, with forecasts before this quarter that revenue could reach about US$5.6b and earnings about US$2.4b by 2029. That is far more upbeat than PKU’s framing. You can compare these competing stories and decide which assumptions feel realistic after the latest guidance cut and the upcoming Stifel conference appearance.
Explore 5 other BioMarin Pharmaceutical fair value estimates, including one that suggests as much as 287% upside from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your BioMarin Pharmaceutical research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for BioMarin Pharmaceutical. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate BioMarin Pharmaceutical's overall financial health at a glance.
Looking for more investment ideas beyond BioMarin Pharmaceutical?
Once you have a view on BioMarin Pharmaceutical, it often helps to compare it with other opportunities that fit different risk and income profiles. The Simply Wall St Screener can help you quickly filter for stocks that match the kind of portfolio you are trying to build.
- If you want potential upside at the smaller end of the market, scan for higher quality candidates using our 13 elite penny stocks with strong financials.
- If capital preservation and balance sheet strength matter most to you, start with a list of solid balance sheet and fundamentals (24 results) to see which businesses might better handle tougher conditions.
- If you are hunting for mispriced quality, sort for companies that look attractively priced on fundamentals through our 32 high quality undervalued stocks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com