
Why Seadrill (SDRL) Is Getting Attention Again
Seadrill (SDRL) put fresh numbers on the table with its third quarter 2026 earnings release, reporting higher sales and revenue along with a deeper quarterly net loss and a smaller loss over the nine-month period.
Recent trading reflects that push and pull. Seadrill’s share price has gained 30.07% year to date and the total shareholder return over the past year is 51.18%. However, the 90 day share price return fell 5.25%, hinting that momentum has cooled after a strong run.
Scan how Seadrill stacks up against other offshore and energy plays by checking the hand picked 43 power grid technology and infrastructure stocks in the same wider infrastructure theme.
Seadrill has rallied strongly on improving top line figures, while losses linger and short term momentum has cooled. Has most of the rerating already played out, or does the current valuation still leave meaningful upside on the table?
Most Popular Narrative: 16% Undervalued
On Simply Wall St, the analyst consensus Narrative pegs Seadrill’s fair value at $54.00 per share, compared with a last close of $45.46. That framework leans heavily on contract visibility, capital spending rolling off, and what that could mean for future cash generation under a 7.81% discount rate.
The shift from heavy project spending on reactivations and reacceptances toward lower capital expenditure guidance of US$200 to US$240m, along with refinancing at lower coupons and an extended share repurchase authorization, points to an inflection toward stronger free cash flow and potential improvement in net margins and per share earnings.
See why 11 investors see Seadrill as 16% undervalued.
Result: Fair Value of $54.00 (UNDERVALUED)
Still, the Seadrill story depends heavily on high dayrate contracts and a tight rig market, so weaker oil company spending or softer pricing could quickly challenge this upside view.
Find out about the key risks to this Seadrill narrative.
Another View: Seadrill Through The Sales Multiple
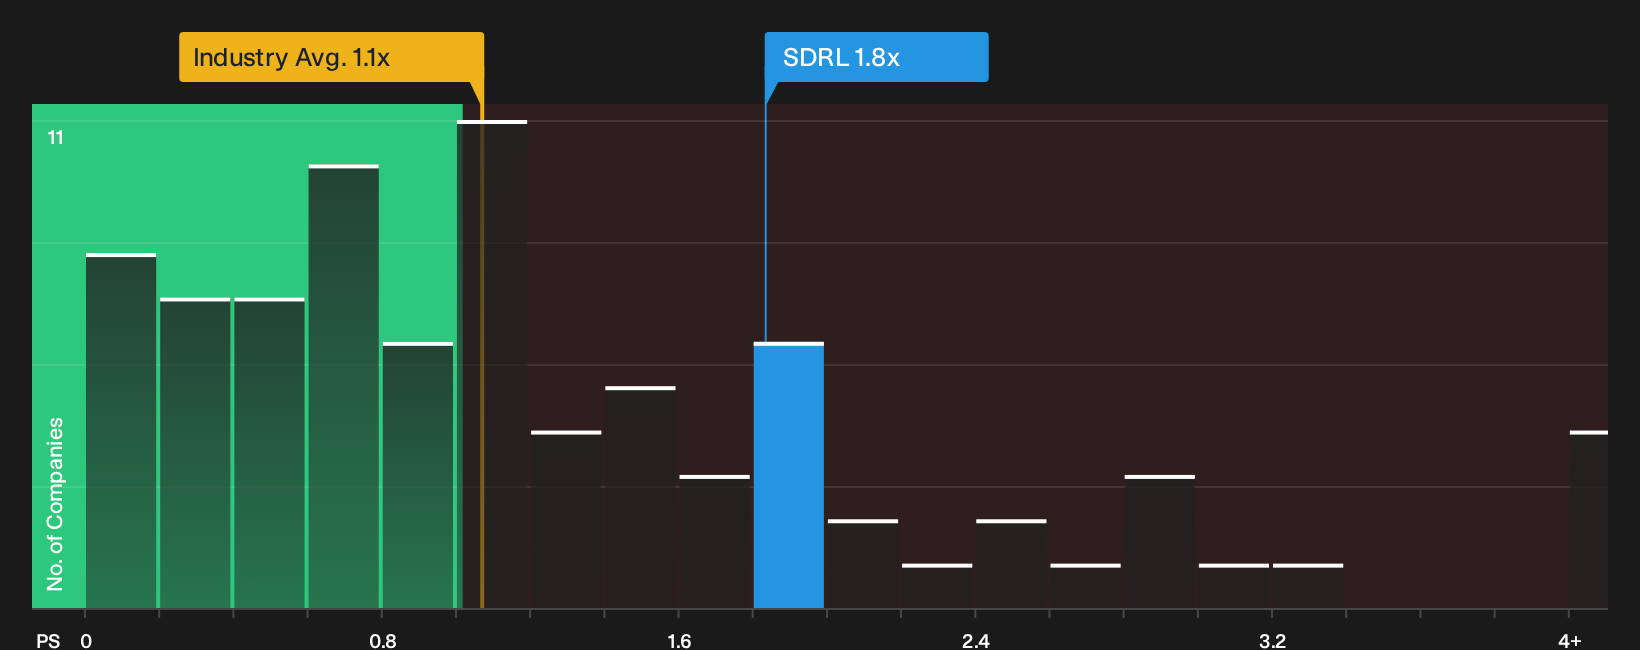
The SWS DCF work paints Seadrill as 16% undervalued, yet the simple sales multiple sends a different signal. The stock trades on a P/S of 1.8x, compared with a fair ratio of 1.2x and a US Energy Services average of 1.1x. That pricing leans more towards execution risk than clear upside. Which lens do you trust more for sizing position risk?
To see how those revenue based signals line up with the broader numbers, review the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
That tug of war between upside potential and execution risk is exactly what makes Seadrill interesting right now, especially with at least one reward on investors’ radar. If you want to judge the balance for yourself, start by weighing those positives alongside the 2 key rewards
Looking for more investment ideas beyond Seadrill?
If Seadrill has sharpened your focus on quality and risk, do not stop here. Better options rarely wait around for investors who hesitate.
- Target value opportunities that pair strong fundamentals with appealing pricing by scanning the 32 high quality undervalued stocks before the crowd catches on.
- Prioritize resilience and balance sheet strength by working through the list of solid balance sheet and fundamentals (24 results) so your shortlist can handle tougher conditions.
- Hunt for fresh stories with room to grow by running the 20 high quality undiscovered gems and flagging companies that are still off most investors' radar.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com