
3 Oil Stocks Retail Investors May Be Watching As Supply Risk Lifts Crude
Oil markets are being reshaped in real time as a prolonged U.S. naval blockade on Iran squeezes a key source of seaborne crude and keeps geopolitical risk high. That kind of supply shock can quickly reshuffle winners and laggards, which is where investors who react early often get an edge. This piece explains how that backdrop relates to three global integrated oil and gas stocks that appear positively exposed to the current news flow.
The stocks covered below are just a first pass on this theme, and the full screen surfaced 10 more integrated producers with equally detailed stories that are not unpacked in this article. To go straight to the source and identify which global majors best fit your own thesis right now, analyze the Global Integrated Oil & Gas Producers screener.
Murphy Oil (MUR)
Murphy Oil slots neatly into this global producers theme because it is a pure exploration and production player whose cash flows move directly with crude prices, and the bearish analyst Narrative on Simply Wall St captures how that leverage cuts both ways when big projects are on the table.
"Although the Bubale discovery offshore Côte d’Ivoire points to a sizeable new oil resource, the planned 18 to 24 month appraisal program with several wells and future development spending in the billions risks locking Murphy Oil into a capital heavy project where weaker appraisal results or cost creep could dilute returns and pressure future free cash flow."
What happens if a single assumption about future project spending and execution proves too optimistic is where your thesis on Murphy Oil really lives.
Murphy Oil is a Houston based exploration and production group focused on crude oil, natural gas and liquids that fits this screener as a leveraged play on tighter global supply, with about US$2.5b of revenue coming from U.S. exploration and production, roughly US$0.6b from Canada and a market value near US$5.2b.
That inflection point is exactly where your edge can come from. Read the full narrative for Murphy Oil to see how Murphy Oil’s risk profile could be quietly decoupling from headline oil volatility.

Capricorn Energy (LSE:CNE)
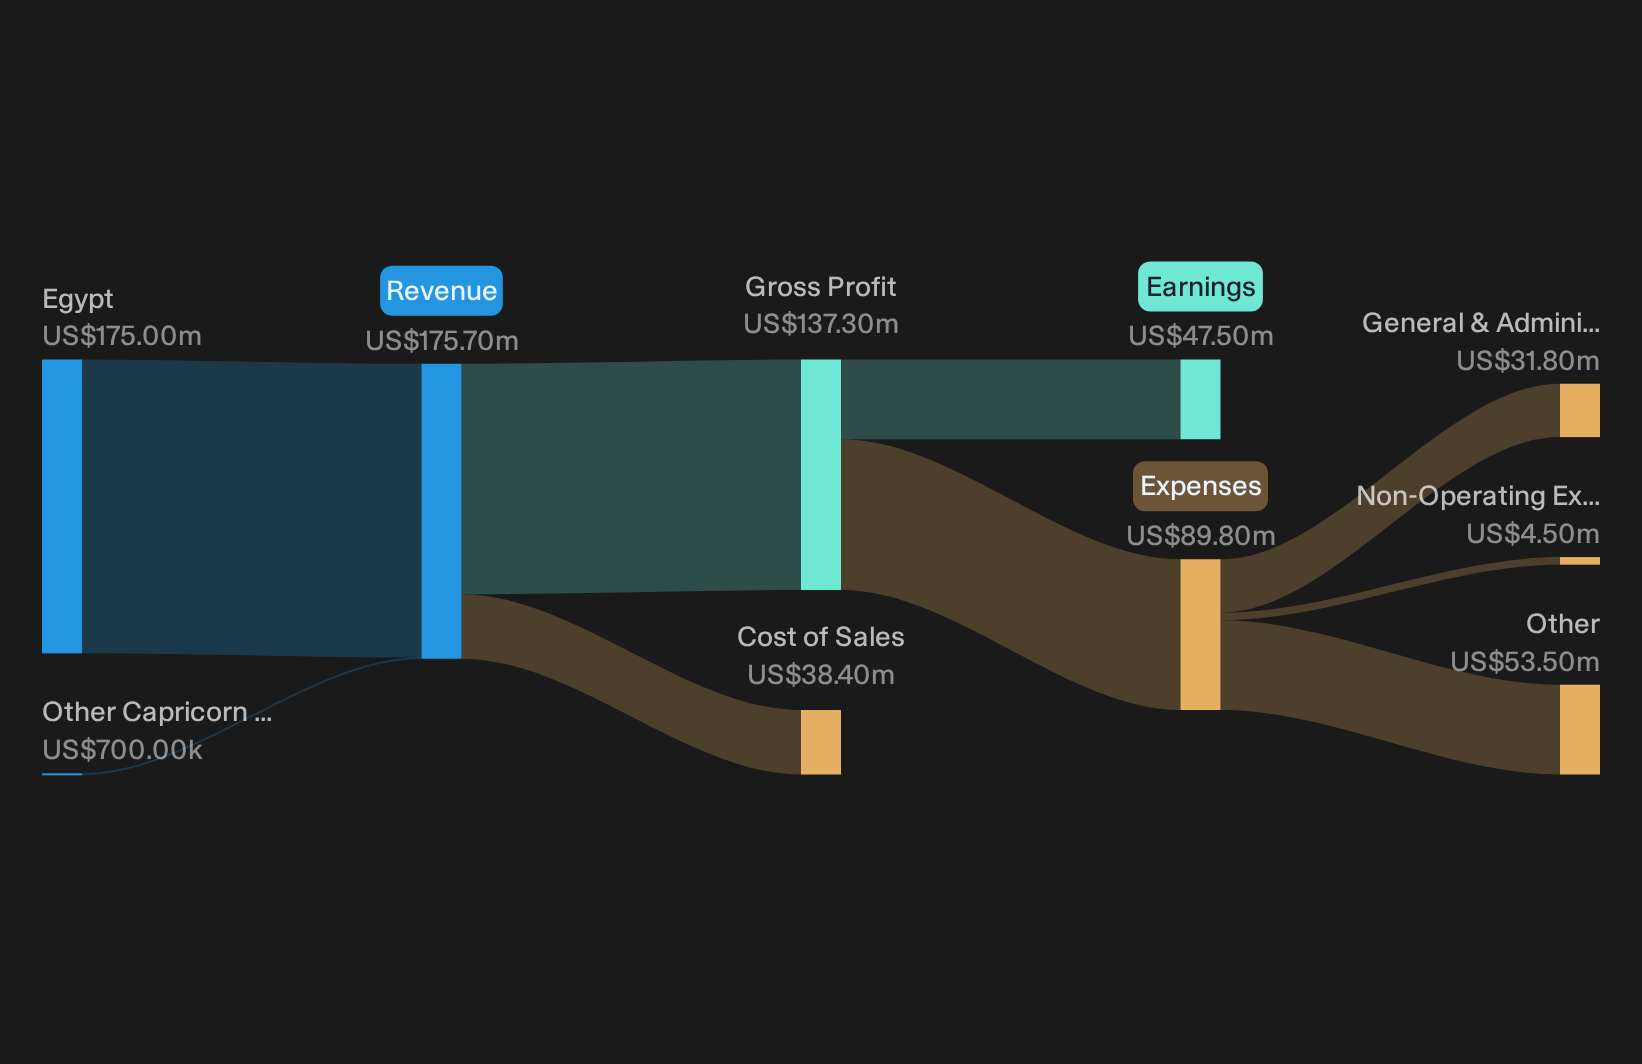
Capricorn Energy fits into the global integrated producers theme as a pure upstream player whose fortunes move with crude and gas prices. The bearish analyst Narrative on Simply Wall St highlights how that leverage runs directly through its Egyptian cash flows.
"Although the anticipated ratification of improved concession agreements in Egypt could provide Capricorn with an extended production horizon and better fiscal terms, unlocking significant resources and supporting future revenue growth, persistent challenges in government payment reliability and a rise in trade receivables threaten cash flow stability and may force the company to constrain investment, limiting the realization of long-term revenue and earnings gains."
The impact of a single assumption about how quickly cash arrives from Egypt could be the swing factor for margins and growth.
That cash timing question is exactly where your edge on Capricorn Energy could start to build, and the full narrative for Capricorn Energy shows how payment risk might be masking future upside.
Saudi Arabian Oil (SASE:2222)
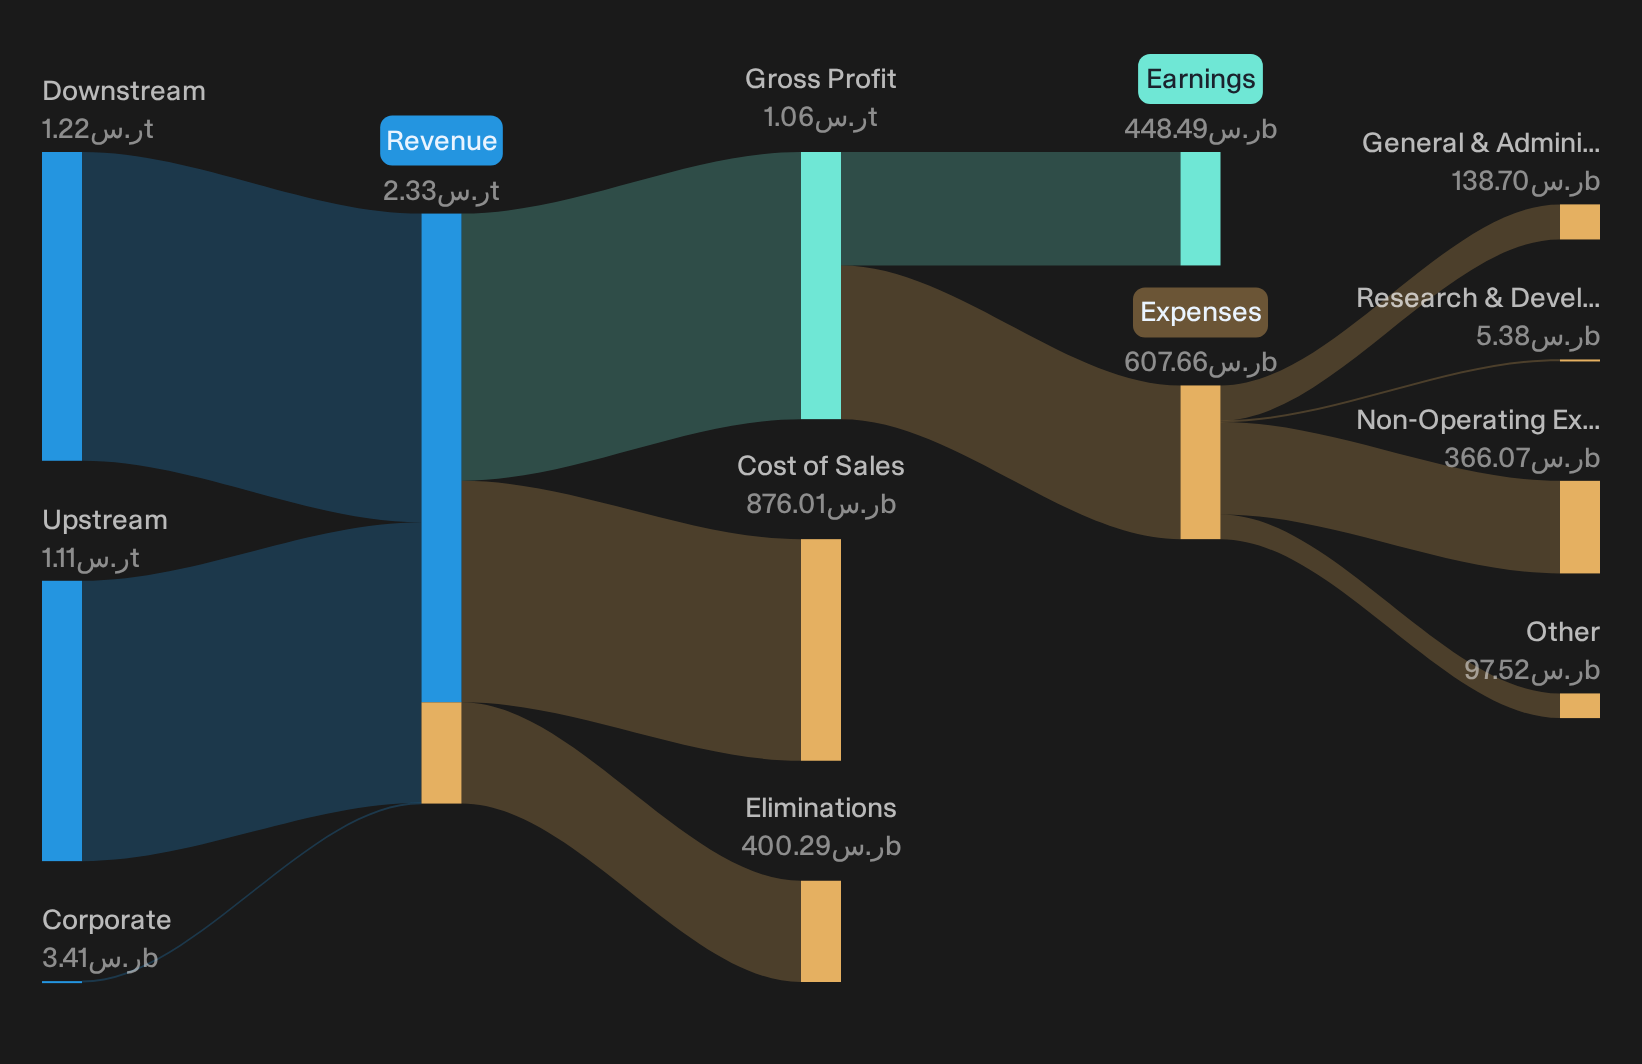
Saudi Arabian Oil is the flagship example of this Global Integrated Oil & Gas Producers theme, combining one of the largest upstream crude bases with extensive refining and chemicals operations. The group generated about SAR 1.1t from Upstream and SAR 1.2t from Downstream, and its market value is roughly SAR 6.4t.
For investors focused on how tighter crude supply can filter through a fully integrated system, Saudi Arabian Oil shows how a national champion with global reach absorbs that shock, according to Alhabib, an investor in the Simply Wall St Community who set out a detailed view of its economics.
"The severe gap between the operating and net margins exposes a heavy tax burden (an effective tax rate of 45.06%)."
What that tax drag ultimately means for Saudi Arabian Oil’s payout ambitions and reinvestment plans hinges on how one pressure point in the cycle resolves.
That tax overhang is only one piece of the puzzle, and the full narrative for Saudi Arabian Oil shows how Saudi Arabian Oil’s cycle exposure and payout ambitions could be quietly decoupling from it.
Seeking Alternatives Before The Crowd
Fresh opportunities do not wait. Breakout moves, fading laggards and under the radar stories can get away quickly. Scan what others miss while it matters and get in early.
- Spot resilient income ideas and track companies that keep paying up even when conditions are tough with the 6 dividend fortresses.
- Hunt for potential mispricings and target financially solid businesses that the crowd has not fully caught yet using the 32 high quality undervalued stocks.
- Zero in on structural change and ride the build out of next generation infrastructure through the 53 AI infrastructure stocks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com