
Herc Holdings (HRI) And The Valuation Debate Around Its Rental Growth Story
Recent commentary on Herc Holdings (HRI) has focused on its potential to scale a specialized rental platform, supported by mega project demand and a wider national account base, while investors weigh this against margin and leverage risks.
Herc Holdings’ share price has climbed 34.34% over the past 30 days and 8.56% year to date, while the 1-year total shareholder return of 26.27% suggests momentum has been building, even as the 90-day share price return declined 4.68% from earlier highs.
Scan a curated set of equipment and infrastructure rental peers that are showing similar project-driven momentum through the 43 power grid technology and infrastructure stocks linked to this Herc Holdings story.
After a 34% surge in a month and a 26% 1-year total return, Herc Holdings now asks a simple question of investors: Does the risk still justify paying up from here as the valuation math gets tighter?
Most Popular Narrative: 17% Undervalued
On the analyst consensus Narrative on Simply Wall St, Herc Holdings screens as undervalued, with a fair value of $199.25 against the recent $165.39 close. This puts the focus squarely on how much of the mega project story is already in the price.
Acceleration in mega project activity, with projected 2026 starts of over US$800b and Herc Holdings now aiming for a 20% share of the implied rental opportunity, could lift equipment rental revenue and support earnings over the next several years.
Realization of identified H&E integration synergies, including about US$380m to US$390m of gross revenue synergies over three years and US$125m of cost synergies targeted by year end 2026, is set to support higher EBITDA and operating margin as the larger platform matures.
See why 5 investors see Herc Holdings as 17% undervalued.
Result: Fair Value of $199.25 (UNDERVALUED)
Still, the Herc Holdings story can break if fuel and transport costs continue to pressure margins or if integration spending continues to dilute earnings per share.
Find out about the key risks to this Herc Holdings narrative.
Another View: What Herc Holdings’ P/E Is Telling You
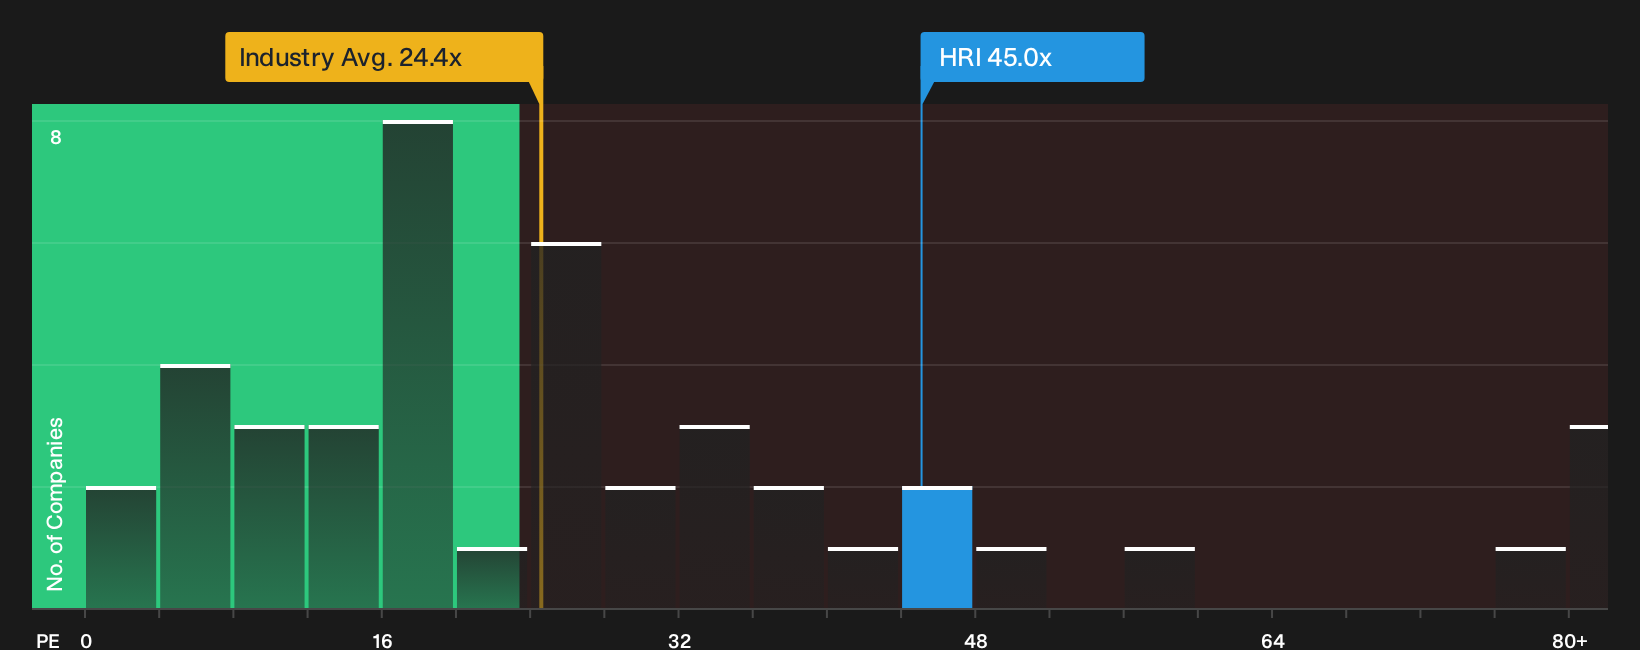
The first narrative leans on future cash flows and analyst targets. A different lens looks at what investors are paying today. On a P/E of about 45x, Herc Holdings trades above the US Trade Distributors sector at 24.4x and sits slightly richer than peer levels near 43.5x.
Simply Wall St’s fair ratio for Herc Holdings is 42.1x P/E, a touch below where the shares trade now. That gap suggests less room for error if growth or margins slip, since the market could drift toward the fair ratio rather than keep paying a premium.
For anyone weighing which signal to trust more, the question becomes simple. Is this premium a reasonable price for the mega project and synergy story, or is it asking too much before those results fully show up in the numbers?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages can be a useful signal, especially when Herc Holdings carries both flagged issues and potential upsides that investors are watching closely. Move early and review the full picture through 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Herc Holdings?
If Herc Holdings has sharpened your focus on quality, use the Simply Wall St screener to explore other opportunities.
- Target resilient returns by scanning a curated universe of low-volatility businesses through the 31 resilient stocks with low risk scores.
- Look for pricing gaps where fundamentals and market expectations differ using the 32 high quality undervalued stocks.
- Focus on financially disciplined operators with cleaner balance sheets through the list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com