
Missed NV Bekaert's Rally? Here's What Holders Backed
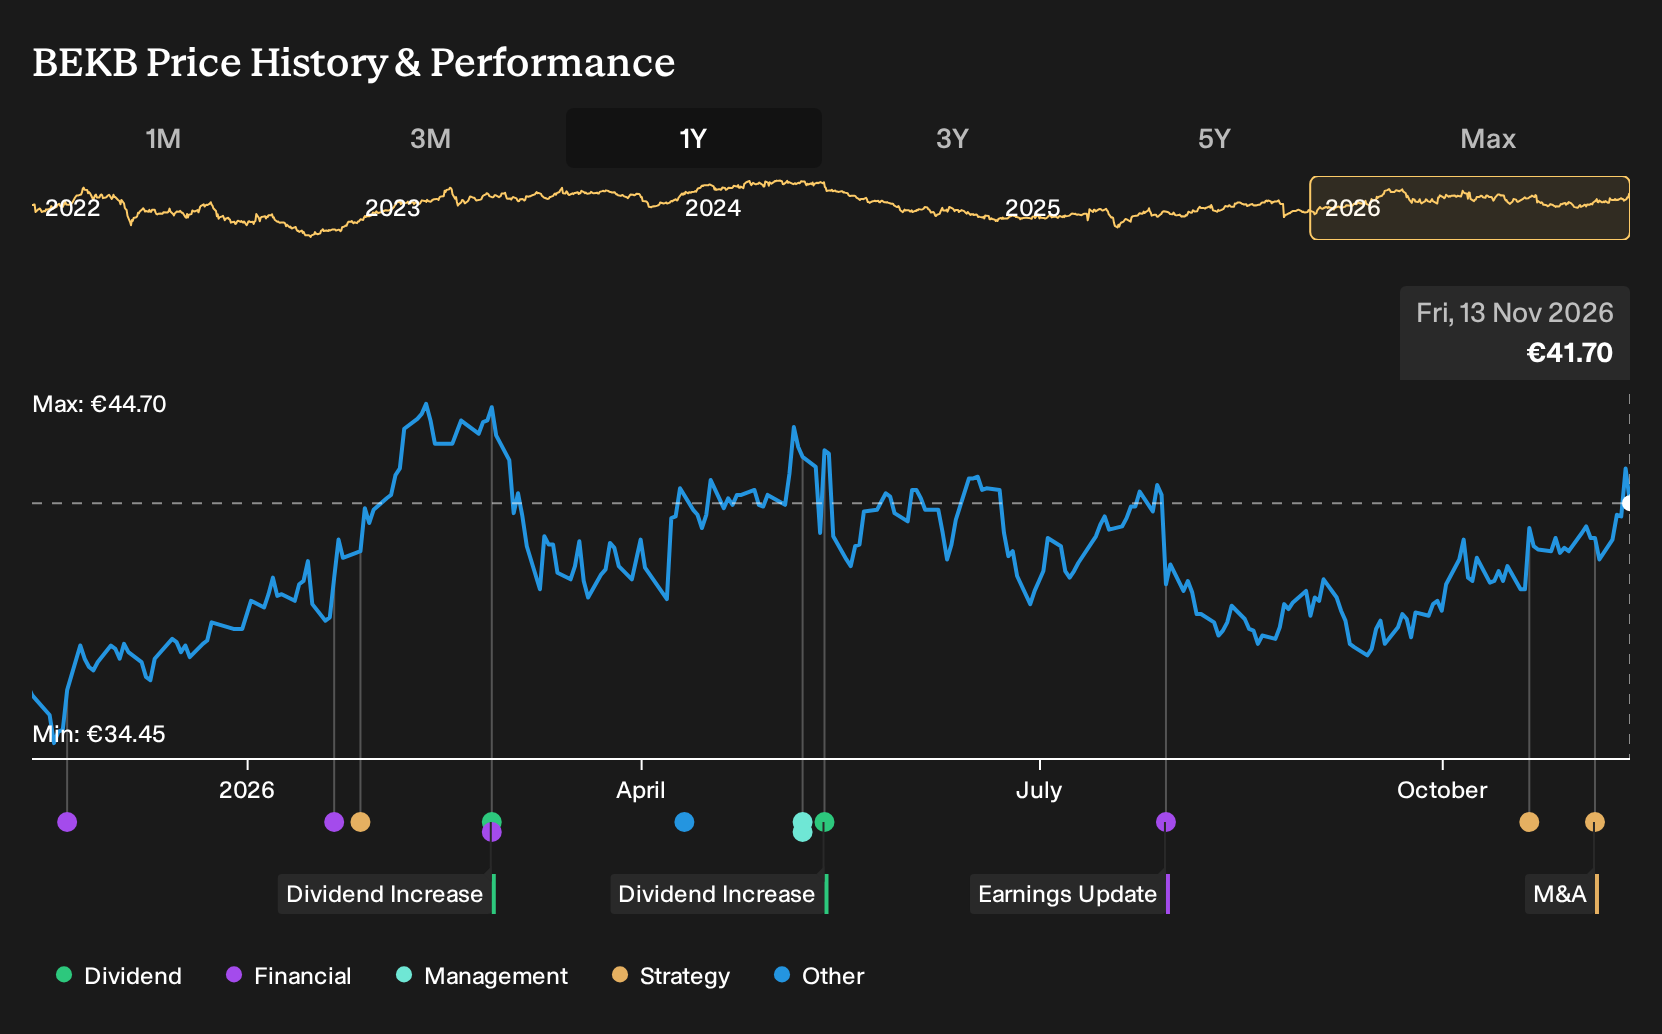
Investors who held NV Bekaert over the past year are up 20.4%, including dividends. If you had been weighing a position on 13 November 2025, you were looking at duelling analyst cases that framed the same steel wire group in very different lights. With earnings initiatives and a share buyback plan set against worries about overcapacity and regulation, which parts of Bekaert’s story would you have trusted most at the time?
The move put NV Bekaert in the middle of this trade. Scan 86 robotics and automation stocks for other companies exposed to it.
The Two NV Bekaert Stories Investors Had To Balance
The shares cost €35.9 at the start of the period, and NV Bekaert sat between two very different stories about what might come next.
On the optimistic side, one group of analysts saw a fair value of €43.7, a price implied by assumptions about revenue growth, fatter profit margins, and a steady share count reduction from the buyback program. That view leaned on demand for renewable energy and infrastructure projects, as well as on efficiency gains from cost cuts and digitalisation.
The cautious camp anchored on a fair value of €32, again a price implied by its own set of expectations. That lens focused on structural overcapacity in steel wire markets, rising regulatory costs tied to decarbonisation rules, and the risk that composite materials and stricter standards would squeeze long term industry margins.
What The Results Changed For NV Bekaert
H1 2026 results gave NV Bekaert bulls some backup. Revenue moved from €1,953.082m in H1 2025 to €1,863.274m in H1 2026, yet net income excluding extra items rose from €81.719m to €94.311m and net margin edged up from 4.2% to 5.1%. That mix of softer sales and higher profitability affected both sides of the original debate.
The key assumption tested here was margin resilience in a tougher volume setting. For any other industrial group, it would be important to track whether net margin trends align with the narrative about efficiency programs and product mix, rather than focusing only on headline revenue.
What NV Bekaert’s 20% Gain Already Prices In
NV Bekaert now trades at €41.7 after a 20.4% move over the past year. The bearish analyst Narrative on Simply Wall St places its Fair Value below that price and argues the recent run already bakes in confident execution rather than deep pessimism.
The Narrative centers on whether portfolio reshaping toward higher value engineered solutions can counter pressure in more commoditised activities. Anyone paying today’s price is assuming that mix shift and margin resilience hold up, so the question is how that squares with the execution and project risks the Narrative flags.
"The current valuation implies that Bekaert’s share price already reflects strong delivery on portfolio reshaping, resilient margins and capital returns, despite operational setbacks and only flat guidance for like-for-like sales and EBIT margins versus 2025."
One Narrative disagrees with today's price. → See where this Narrative says NV Bekaert should trade
Go Straight To The Source
By the time a rally makes headlines, you are reading about returns someone else has already earned. Why not go straight to the source and look for your own contrarian opportunity? These three companies trade below our estimated value.
- Company 1 - 32% below our estimate - builds a bank funded digital lending model using low cost deposits and automation tools.
- Company 2 - 47% below our estimate - shifts monetisation toward AI targeted advertising and value added services around long form content.
- Company 3 - 40% below our estimate - rolls out AI agents across a large digital client base to tighten costs and loan processes.
That is three of the list. See the full list of 197 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com