
How Strong Earnings And A Dividend Increase Will Impact Fortis Stock Investors
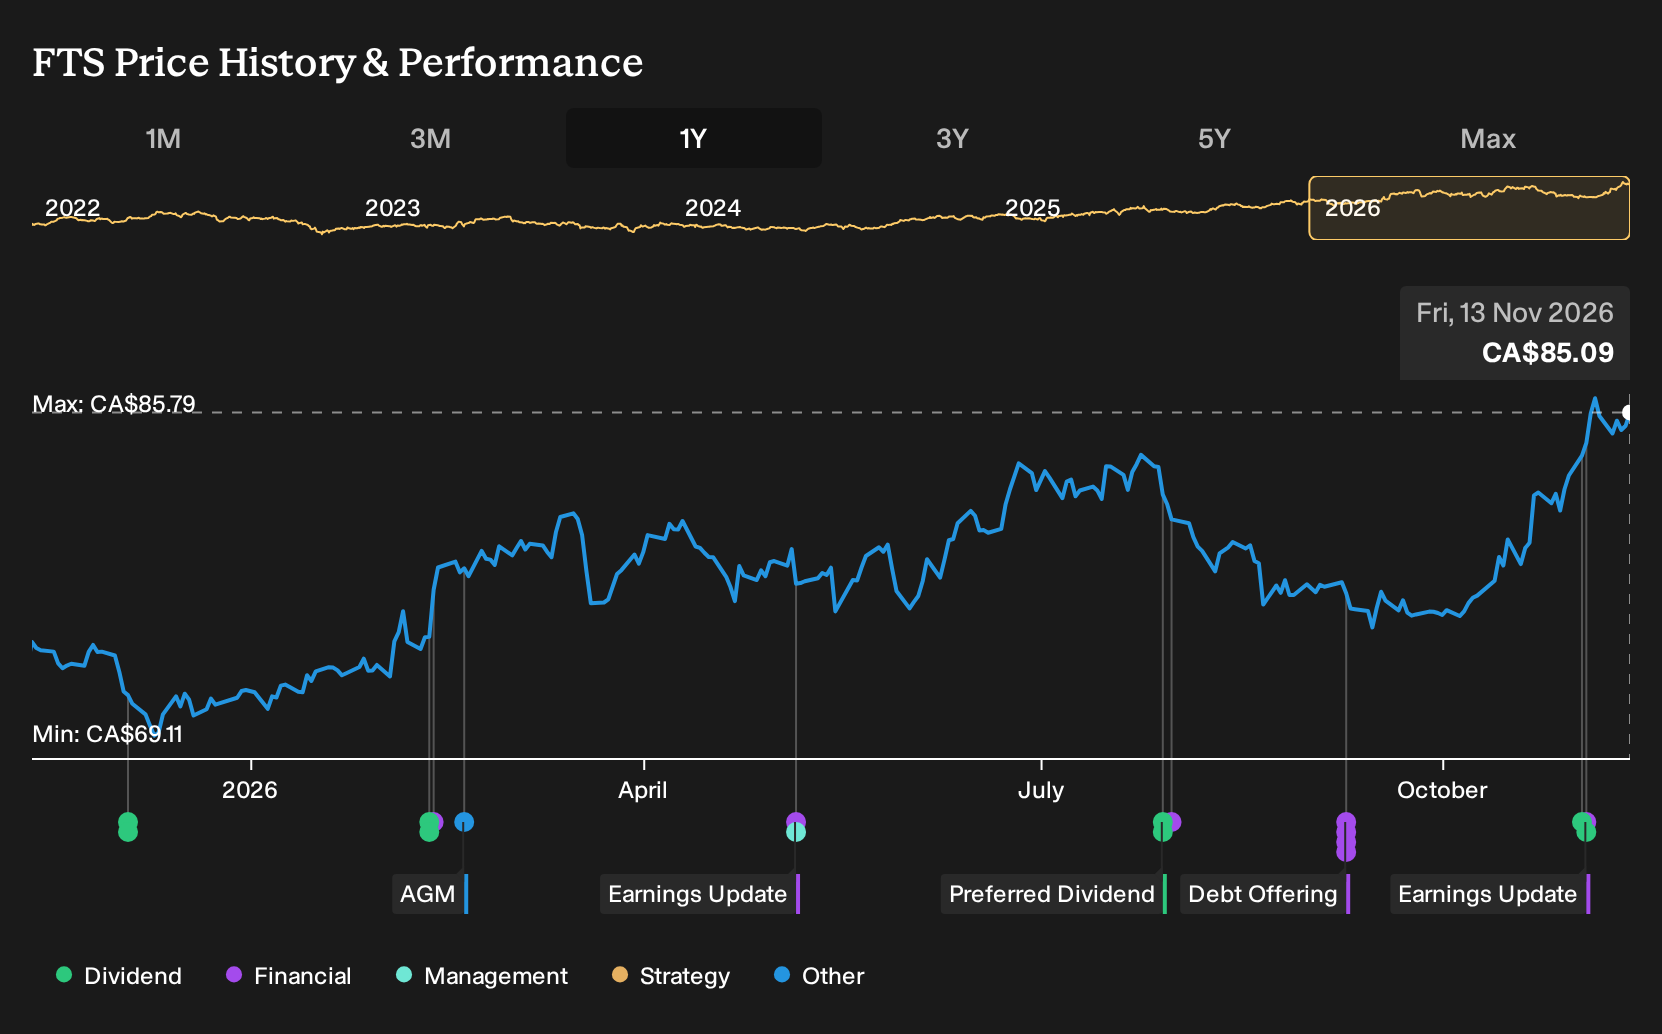
- Fortis reported third quarter 2026 sales of C$3,115 million and net income of C$496 million, with basic earnings per share from continuing operations of C$0.92. The company also detailed higher year-to-date figures for revenue and profit through the first nine months.
- The board paired those results with a higher quarterly dividend of C$0.6650 per share and detailed preferred share payouts. This highlights how Fortis is returning cash across its capital structure while running a capital intensive regulated utility model.
- We will now look at how Fortis's investment narrative could be affected by this stronger quarterly earnings print and higher dividend.
Scan beyond Fortis and line up other regulated utilities that combine material earnings and dividend profiles with our curated list of 3 dividend fortresses.
Fortis Investment Narrative Recap
To own Fortis, you need to be comfortable with a slow burn utility story where regulated assets, a long capital plan and predictable cash flows matter more than rapid growth. The analyst consensus narrative on Simply Wall St leans heavily on Fortis executing its C$28.8b program and converting data center and LNG projects into rate base.
The latest quarter showed higher earnings and revenue versus last year, which supports that execution story in the near term. The key short term swing factor still appears to be regulatory lag at UNS Energy, while the biggest risk remains heavy capital spending funded by debt and the related pressure from interest costs.
The most relevant update for that picture is the higher quarterly dividend of C$0.6650 per share. It sits alongside preferred share dividends and reflects how Fortis is currently allocating cash while it runs a capital intensive model that already relies on external borrowing.
For you as a shareholder, that payout increase links directly to two moving parts. On one side, the business is reporting higher net income and earnings per share, which supports ongoing distributions. On the other side, there is already commentary that free cash flow and interest coverage are tight, so future dividend decisions will likely track how Fortis funds and delivers its long term projects.
Fortis' current earnings of CA$1.8b sit against analyst projections for revenue of CA$14.8b and earnings of CA$2.4b by 2029, which implies forecast revenue growth of 5.6% per year and an earnings increase of about CA$0.6b from today's level.
Uncover why Fortis' fair value indicates a 3% potential downside to its current price, leaving little room for error.
Exploring Other Perspectives
The Simply Wall St Community only includes two fair value views on Fortis, with estimates spread widely from C$24.66 to C$82.82 per share. That gap already shows how far opinions can stretch before factoring in the latest earnings beat and dividend moves. Treat it as a prompt to compare several alternative viewpoints yourself.
Explore another Fortis fair value estimate, including one that suggests it could be worth as much as CA$82.82.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Fortis research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Fortis. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Fortis' overall financial health at a glance.
Looking For More Investment Ideas Beyond Fortis?
Once you have a view on Fortis, it can help to compare it with other companies that share similar qualities or offer a different balance of risk and return. The Simply Wall St Screener gives you a structured way to do that without getting lost in thousands of tickers.
- If capital preservation and steadier profiles appeal to you, start with companies that appear more resilient by using the 9 resilient stocks with low risk scores.
- If you want stronger balance sheets alongside earnings support, search for businesses that pair low leverage with solid fundamentals through the list of solid balance sheet and fundamentals (6 results).
- If you are hunting for potential future leaders that are not widely followed yet, scan for under-the-radar opportunities with the 9 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com