
NuScale Power (SMR) Stock Could Be Undervalued Despite Legal Uncertainty
NuScale Power has seen its share price move sharply in recent years, and after a steep pullback the puzzle for investors is whether the current US$4.66 level lines up with what the company’s book value can reasonably support. With fresh legal and commercial headlines in play, the question now is how much of the balance sheet story is already reflected in the stock.
- Over the past 3 years, NuScale Power has delivered a share price gain of 86.4%. This puts real weight on whether the balance sheet can underpin that kind of long run move.
- A class action over alleged misstatements around competitive edge, revenue potential and cash runway, together with a key but still uncertain agreement with the Tennessee Valley Authority, can influence how much value investors are comfortable assigning to NuScale Power’s equity relative to its recorded net assets.
- There is a second opinion on NuScale Power worth weighing. See what analysts think NuScale Power's shares could be worth.
The stock’s next move may depend on whether NuScale Power’s current market value lines up with, or departs from, what its book value might justify.
If you want a broader starting point while you weigh NuScale Power’s book value story, run the same test across 16 nuclear energy infrastructure stocks.
Is NuScale Power Still Cheap on Book Value?
For a business like NuScale Power that is still working toward commercial scale, investors often focus on price to book because it anchors the share price to the net assets already recorded on the balance sheet.
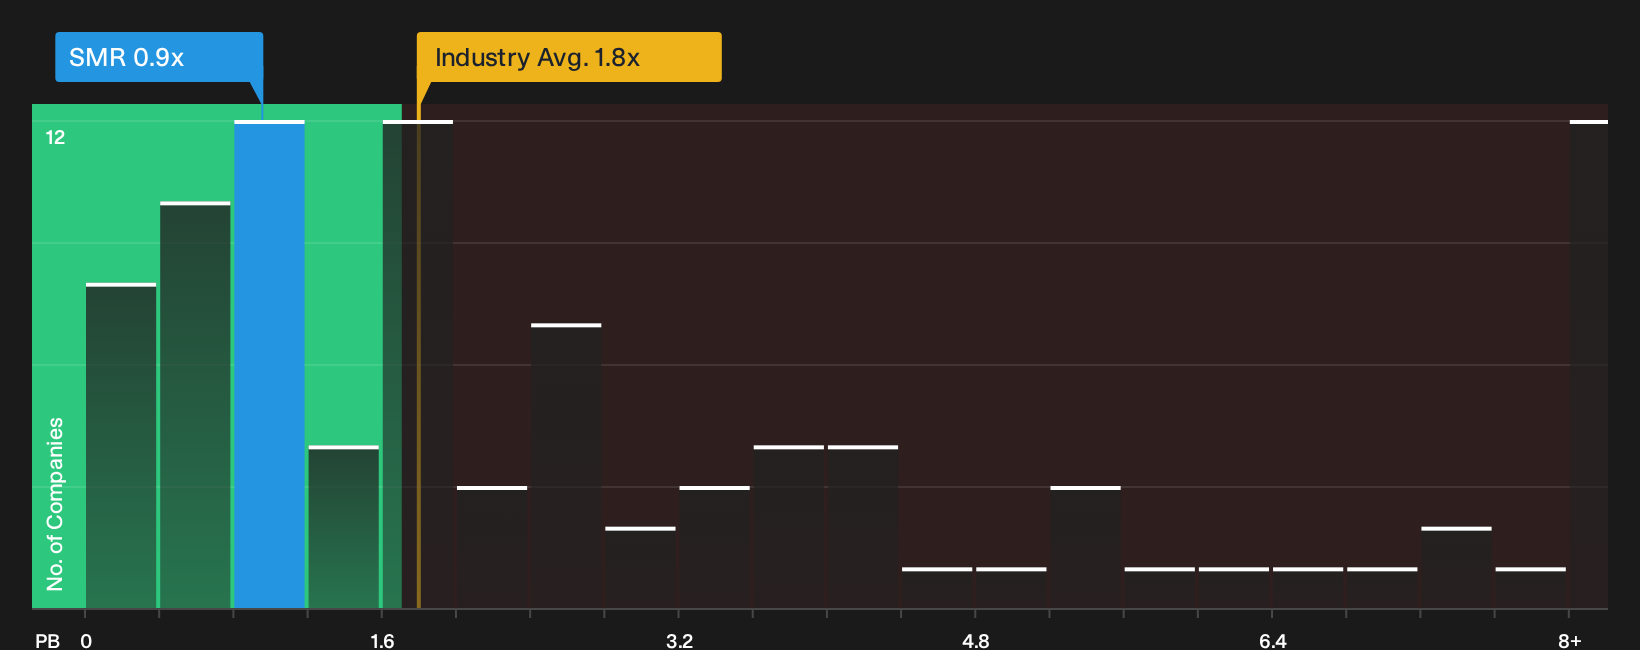
On this lens, NuScale Power trades on a P/B of about 0.9x, compared with an Electrical industry average near 1.8x and a peer group closer to 4.9x. That means the market is valuing the equity at a discount to both the sector and to similar companies, even though book value reflects assets that are already in place rather than hoped for future projects. The recent class action lawsuit over alleged misstatements around competitive advantage and cash runway helps explain why investors might be hesitant, because legal and execution risks can keep a lid on how much of that asset base the market is willing to pay for.
For anyone weighing whether this discount signals opportunity or just higher risk, it is worth lining up the P/B against NuScale Power’s cash burn, contract visibility and regulatory milestones. Explore the numbers behind NuScale Power's P/B valuation.
The NuScale Power Narrative: What Would Justify Today's Price?
Simply Wall St Narratives continue from the book value question for NuScale Power by explaining which paths for growth, margins and future earnings would need to occur for the stock to be worth materially more or less than it is today. Each scenario links a fair value estimate to a particular mix of potential catalysts and pressure points so you can track over time which version of NuScale Power's story appears closer to reality on the Community page.
The bullish and bearish narratives on NuScale Power are far apart, with each side reading the same cash pile and contracts pipeline very differently.
Bull case: 55% undervalued
This view comes from the analyst consensus Narrative on Simply Wall St, which pulls together forecasts and targets into one framework.
"The main requirement for this view is converting regulatory progress, liquidity of about US$1.9b and advanced supplier manufacturing into firm long-term power purchase and project contracts…"
Discover why this Narrative puts NuScale Power at 55% undervalued.
Bear case: 475% overvalued
According to PTrain, a Simply Wall St Community investor who wrote the Narrative, the concern starts with who NuScale Power chose to partner with.
"ENTRA1 Controversy: Class action exists against NuScale for securities fraud following allegations that it misrepresented the experience of ENTRA1 as it's partner when it was a three-year-old entity…"
Explore why this Narrative puts NuScale Power at 475% overvalued.
One more angle on NuScale Power that could change how you see it
Balance sheet metrics and competing narratives tell only part of NuScale Power's story, because broker expectations a few years out offer a separate reference point for where this business might be heading. Explore where analysts expect NuScale Power to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com