
Emera (TSX:EMA) Earnings Reset Puts Valuation Back In Focus
Emera earnings and what changed in the latest quarter
Emera (TSX:EMA) just reported third quarter 2026 results that showed lower revenue and net income compared with the same period last year, putting fresh focus on how the utility is earning its returns.
Emera’s latest quarterly update landed alongside a sharp pickup in trading interest, with the share price at CA$72.98 and a 30 day share price return of 8.97% that builds on a 7.96% year to date move and a 13.32% one year total shareholder return. This suggests that investors are reassessing both near term earnings risk and the longer term income story despite softer revenue and profit in the quarter.
Scan how Emera’s earnings reset compares with other regulated utilities by reviewing a hand picked group of 44 power grid technology and infrastructure stocks.
Emera’s share price is now close to both intrinsic value estimates and analyst targets after the post-earnings jump. Is that a sign the market is too cautious, or already about right on the risk?
Most Popular Narrative: 1% Undervalued
Emera’s last close at CA$72.98 sits slightly below the analyst consensus Narrative fair value of CA$74, which points to a small discount and a tight margin of safety that hinges on execution. The analyst consensus Narrative on Simply Wall St frames that gap around rate base expansion, capital spending discipline and a long runway of regulated earnings.
The main factor that has to go right is that Emera successfully executes the all-share merger with Canadian Utilities, delivers the planned 7% to 8% annual rate base growth, and maintains investment-grade credit metrics while funding roughly $4b of annual capital spending.
See why 37 investors see Emera as 1% undervalued.
The analyst framework also leans on a 6.44% discount rate for Emera, which is relatively moderate for a regulated utility with CA$22.3b in market value and mostly contracted or regulated cash flows. That rate shapes how much weight the Narrative gives to earnings beyond the next few years and helps explain why a fair value of CA$74 only sits about 1% above the current share price after the recent rally.
The same Narrative assumes future revenue and profit margin forecasts, along with a specific P/E multiple in 2029, so readers may want to stress test those inputs against their own expectations for regulation, capital intensity and rate decisions across Florida, Atlantic Canada and the gas utility portfolio. Small changes to long term earnings growth or the assumed valuation multiple can move fair value estimates meaningfully even when the starting point looks close to market pricing.
Result: Fair Value of CA$74 (UNDERVALUED)
Still, higher share issuance that weighs on EPS, and any shortfall against the projected margin lift, could quickly erode confidence in the Emera narrative.
Find out about the key risks to this Emera narrative.
Another view on Emera valuation
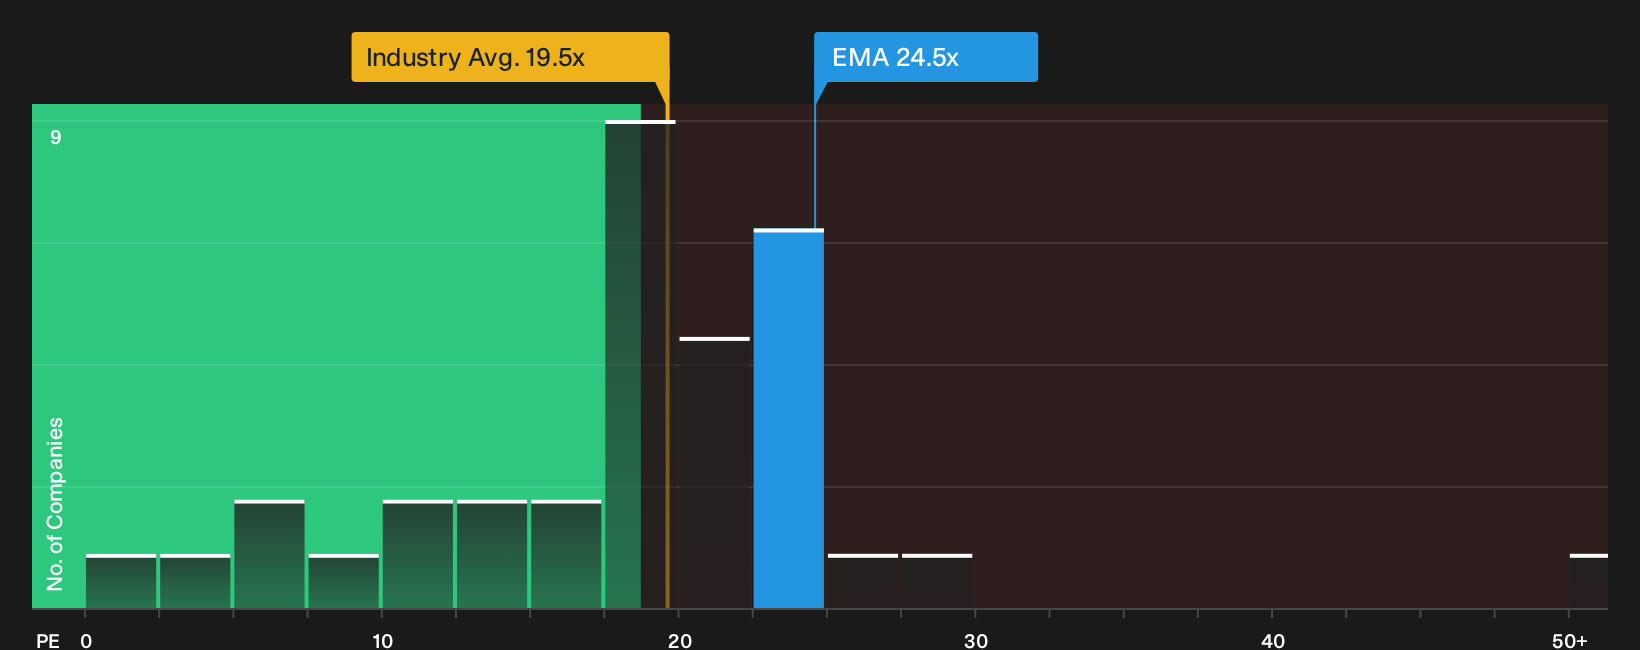
Emera may look modestly undervalued on the Simply Wall St fair value estimate, yet the P/E picture tells a tougher story. The stock trades at 24.5x earnings versus 19.5x for the North American Electric Utilities group and 22.3x for peers, while the fair ratio is 32.8x. That mix points to meaningful valuation risk if sentiment cools, but also potential for the market to further expand the multiple. Which side of that tradeoff do you think becomes more influential as new data is released?
For a closer look at how this earnings multiple compares with both the sector and Emera’s own fair ratio, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals like this rarely stay ambiguous for long. Move quickly, review the underlying data, and weigh both sides of Emera’s story using 2 key rewards and 2 important warning signs.
Looking for more Emera-sized investment ideas?
If Emera has your attention, do not stop here. Broaden your playbook now with other opportunities that line up with the kind of portfolio you actually want.
- Target resilient balance sheets by scanning a list of solid balance sheet and fundamentals (6 results) that can help anchor your portfolio when conditions get choppy.
- Hunt for mispriced quality by reviewing a 6 high quality undervalued stocks that filters for fundamentals first instead of hype.
- Stack income potential by focusing on a 3 dividend fortresses built for investors who want yield without ignoring financial strength.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com