
Is CT Real Estate Investment Trust (TSX:CRT.UN) Undervalued As Strong Q3 Earnings Lift Sentiment?
CT Real Estate Investment Trust (TSX:CRT.UN) is back in focus after its third quarter update, with occupancy at 99.5% and rental increases alongside active development and leasing, giving investors fresh data to assess the units.
CT Real Estate Investment Trust has seen its unit price grind higher in recent months, with a 1 month share price return of 6.28% and a year to date share price gain of 12.35% at a last close of CA$18.28. That steady climb sits alongside a stronger income story for long term holders, with a 1 year total shareholder return of 20.53% and a 3 year total shareholder return of 59.30%, suggesting recent operational updates are feeding into firmer momentum.
Scan beyond CT Real Estate Investment Trust and line up other income-focused plays with resilient profiles using our curated list of 9 resilient stocks with low risk scores.
For CT Real Estate Investment Trust, that steady climb in the unit price could be the market finally catching up to the earnings and leasing story, or just enthusiasm running ahead of itself. How far do the current fundamentals actually take you on valuation?
Price-to-Earnings of 17.3x: Is it justified?
On a simple snapshot, CT Real Estate Investment Trust trades on a P/E of 17.3x at a unit price of CA$18.28, with that earnings multiple sitting between cheaper direct peers and a more expensive wider Retail REITs group.
The P/E ratio compares what investors pay for each dollar of current profit, which is particularly relevant for a mature landlord where earnings and distributions tend to move closely together over time. For a REIT like CT Real Estate Investment Trust, the multiple effectively signals how much the market is willing to pay for its current income profile and earnings trajectory.
Earnings have grown 18.4% over the past year against an 8.7% per year figure over five years, and net profit margins sit at 40% compared with 35.6% previously, which helps explain why the P/E of 17.3x screens as good value against the North American Retail REITs industry average of 22.4x. At the same time, that ratio looks expensive relative to a 15.5x peer average and Return on Equity of 11.8% is described as low, so the market is not clearly mispricing CRT.UN on this metric in one direction.
Relative to the sector, the 17.3x P/E is materially lower than the broader Retail REITs cohort at 22.4x, yet sits above immediate peers at 15.5x. This points to the market assigning CT Real Estate Investment Trust a middle of the road earnings valuation that acknowledges its growth record while still keeping a discount to the industry as a whole.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-Earnings of 17.3x (ABOUT RIGHT)
Still, the CT Real Estate Investment Trust story leans heavily on a single anchor tenant and a concentrated Canadian retail footprint, so any vacancy shock could quickly challenge that earnings multiple.
Find out about the key risks to this CT Real Estate Investment Trust narrative.
Another View: CT Real Estate Investment Trust Through Cash Flows
There is a very different message coming from the cash flow work. Our DCF model points to a future cash flow value of CA$30.78 per unit, compared with a current CT Real Estate Investment Trust price of CA$18.28. That 40.6% gap suggests the market is heavily discounting its long lease income stream. Is that prudence or an opening for patient income investors?
Look into how the SWS DCF model arrives at its fair value.
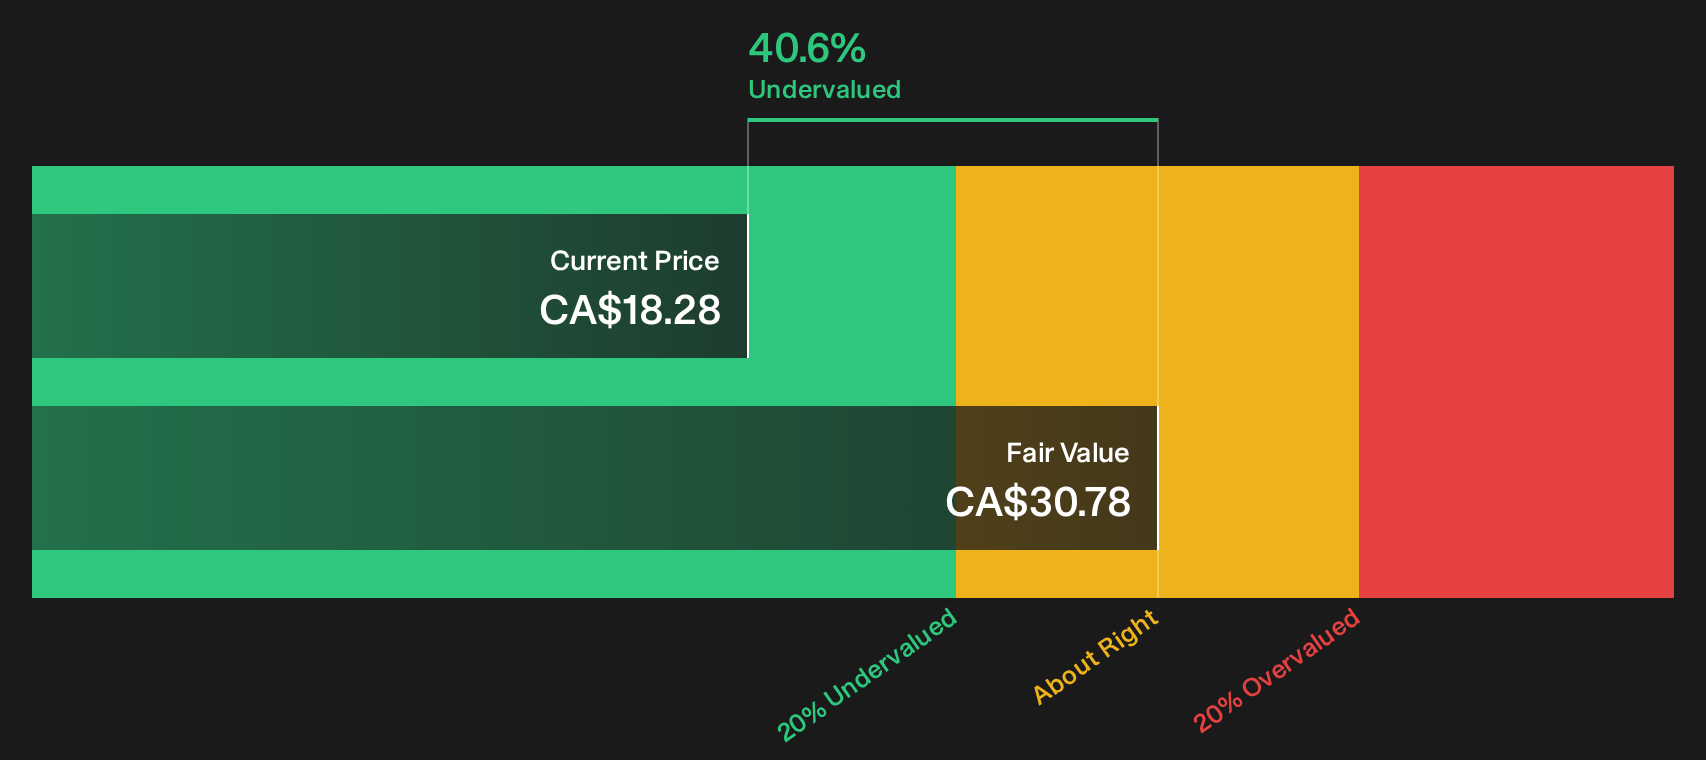
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out CT Real Estate Investment Trust for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 6 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
That tension between an apparently cheap cash flow profile and a fair looking earnings multiple leaves CT Real Estate Investment Trust sitting in a grey zone. If you want to move quickly and build your own take grounded in data, start by weighing the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond CT Real Estate Investment Trust?
Do not stop at CT Real Estate Investment Trust. The market offers a wide range of opportunities, and missing the right mix of income and growth could mean forgoing meaningful long term gains.
- Target income resilience by scanning a 3 dividend fortresses that can help you focus on payouts supported by stronger balance sheets.
- Hunt for value opportunities that the crowd may be overlooking by running a 9 high quality undiscovered gems with solid fundamentals at the core.
- Protect the downside first by filtering for a list of solid balance sheet and fundamentals (6 results) so potential ideas begin with financial strength rather than speculation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com