
Magnite (MGNI) After The Gracenote Deal Is The CTV Story Still Undervalued
Magnite (MGNI) has moved back into focus after Gracenote expanded its collaboration with the company, giving advertisers more precise connected TV targeting through Magnite’s SpringServe platform and Gracenote’s content graph driven custom deals.
Recent trading reflects building momentum in Magnite, with a 1 month share price return of 15.88%, an 82.69% year to date share price gain and a 106.18% total shareholder return over 1 year. This suggests investors are pricing in stronger connected TV potential and a different risk profile after the Gracenote partnership and early November earnings release.
Scan beyond Magnite and see which other ad tech players are showing similar momentum in connected TV by checking our curated list of 20 high quality undiscovered gems.
After a 1 year total return above 100% and fresh enthusiasm around connected TV deals, the next step is simple: Does Magnite’s current valuation still leave enough upside to justify new money going in now?
Most Popular Narrative: 7.9% Undervalued
Magnite’s last close at $29.34 sits below the analyst consensus Narrative fair value of $31.87. The analyst consensus Narrative on Simply Wall St builds this value from detailed forecasts for revenue, earnings and margins, all discounted back at 9.91%.
The numbers imply a share price that treats Magnite’s raised 2026 guidance for contribution ex-TAC growth, adjusted EBITDA margins, and free cash flow growth, alongside its low net leverage and ongoing buybacks, as not fully reflecting the company’s long-term earnings power.
See why 13 investors see Magnite as 8% undervalued.
Result: Fair Value of $31.87 (UNDERVALUED)
Still, the Magnite story can break if major CTV partners push more ads into closed ecosystems, or if web display weakness in DV+ drags harder on contribution ex TAC.
Find out about the key risks to this Magnite narrative.
Another View: Magnite’s P/E Sends A Different Signal
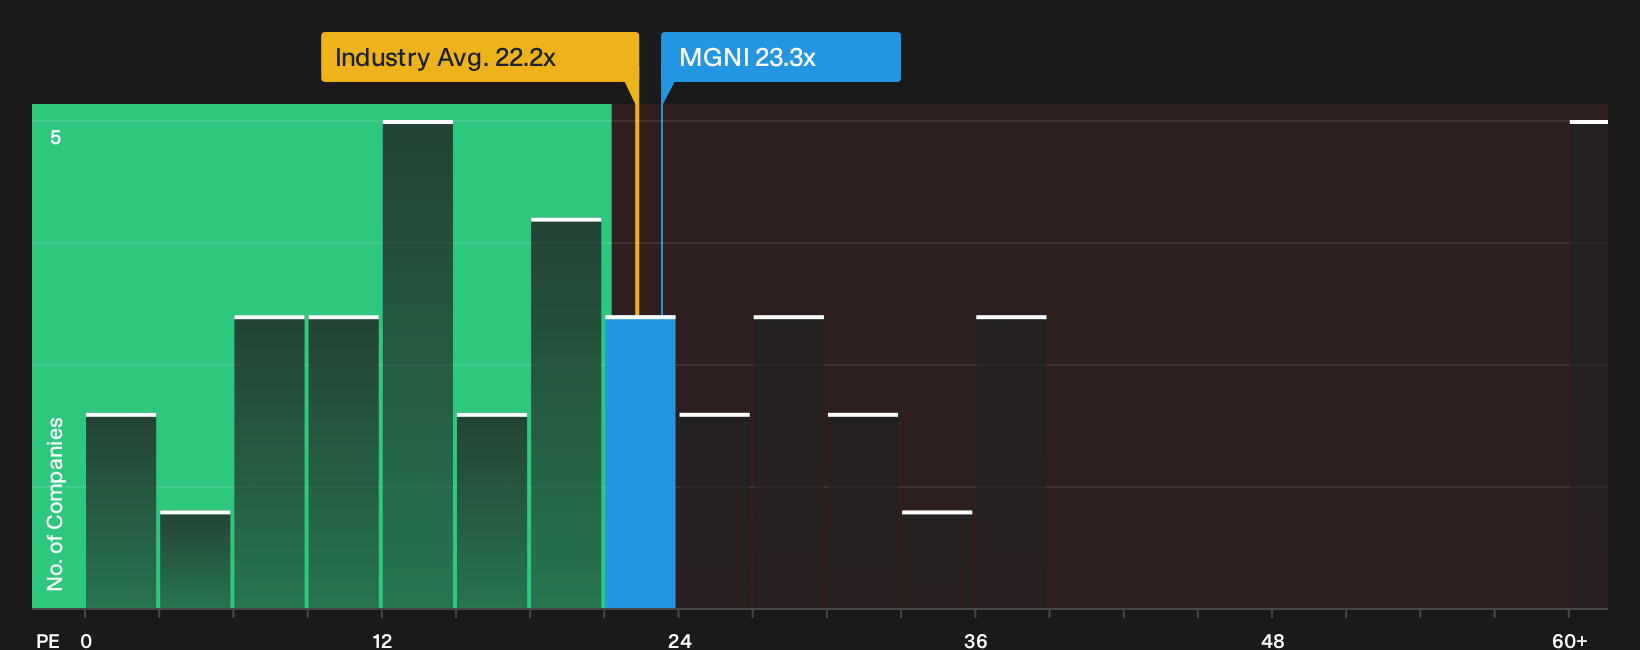
The analyst fair value of $31.87 paints Magnite as 7.9% undervalued, yet the simple P/E check tells a cooler story. At 23.3x earnings, the stock trades above its own fair ratio of 15.1x, even though it sits below a 38.9x peer average. That mix points to real valuation risk if expectations reset.
For a closer look at how this pricing gap could close in either direction, have a look at See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Big questions hang over whether this upbeat Magnite story really matches your own risk tolerance and return expectations, so consider reviewing the details and evaluating the numbers yourself. To see the specific upside factors that current holders are focusing on, walk through the 1 key reward
Looking for more investment ideas beyond Magnite?
If Magnite has sharpened your thinking, do not stop here. Broader idea hunting can help you balance risk, diversify returns, and find fresh opportunities.
- Target potential mispricings by running through the 32 high quality undervalued stocks that blend quality fundamentals with attractive entry points.
- Strengthen your portfolio’s foundation by tracking companies in the list of solid balance sheet and fundamentals (23 results) that aim to pair financial resilience with durable business models.
- Dial back portfolio stress and focus on stability by filtering opportunities inside the 29 resilient stocks with low risk scores before market sentiment shifts.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com