
GLOBALFOUNDRIES (GFS) On Earnings And Guidance Has Investors Rethinking Its Valuation
GLOBALFOUNDRIES (GFS) is back in focus after third quarter results showed sales of US$1,899 million alongside a net loss of US$271 million, paired with fresh fourth quarter revenue and earnings guidance.
GLOBALFOUNDRIES shares trade at US$42.62, and the recent third quarter update and fresh guidance have come after a choppy stretch where the 7 day share price return of 17.22% follows a 90 day share price decline of 21.91% and a 1 year total shareholder return of 30.77%. This suggests that shorter term momentum is rebuilding after a weak few months, while longer term holders still face a 3 year total shareholder return decline of 24.16%.
Scan how GLOBALFOUNDRIES stacks up against other chip manufacturers reacting to fresh earnings and guidance by reviewing our curated list of 53 AI infrastructure stocks.
The share price rebound after a year of mixed returns sets a clear fork in the road for GLOBALFOUNDRIES investors. Does the current valuation still offer enough upside potential to justify the fresh earnings risk?
Most Popular Narrative: 34% Undervalued
GLOBALFOUNDRIES last traded at $42.62, while the analyst consensus Narrative on Simply Wall St points to a fair value of $64.77 based on discounted future cash flows using an 11.71% discount rate and detailed revenue and earnings forecasts.
The main thing that has to go right is that GlobalFoundries converts its CHIPS Act backed investments, customer co funding and capacity buildout in silicon photonics, SiGe, power and quantum into sustained demand and pricing power that justify higher capital intensity.
The current valuation implies the share price does not fully reflect GlobalFoundries exposure to faster growing communications infrastructure and data center, automotive and IoT segments or the cash returns signaled by its dividend and buyback framework.
See why 49 investors see GLOBALFOUNDRIES as 34% undervalued.
Result: Fair Value of $64.77 (UNDERVALUED)
Still, GLOBALFOUNDRIES relies heavily on smart mobile demand and elevated 2027 capex plans. Any slowdown in new capacity payback could quickly challenge this undervaluation thesis.
Find out about the key risks to this GLOBALFOUNDRIES narrative.
Another View on GLOBALFOUNDRIES Valuation
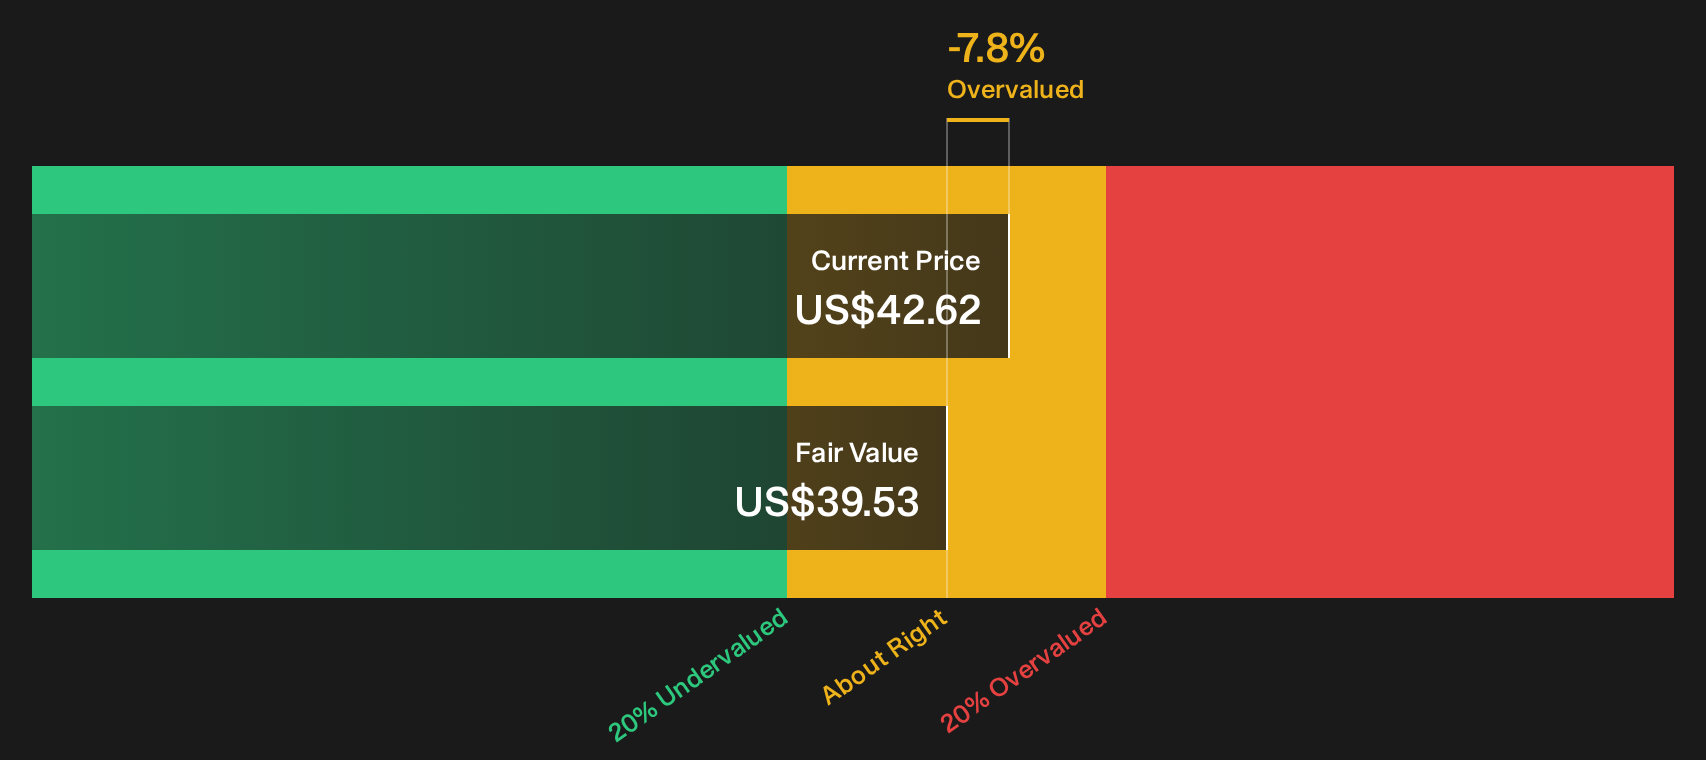
The Simply Wall St DCF model presents a very different picture compared to the analyst fair value of $64.77. According to that framework, GLOBALFOUNDRIES at $42.62 is trading above an estimated future cash flow value of $39.53, which suggests an overvalued outcome instead of a discount.
For anyone weighing these two signals, the key question is which set of assumptions on growth, margins and required return appears more realistic for GLOBALFOUNDRIES over the next decade.
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Sentiment in this GLOBALFOUNDRIES update runs mixed, so move fast, study the key drivers yourself, and pressure test every assumption against the numbers. To see what optimists are focusing on, review 2 key rewards
Want more ideas beyond GLOBALFOUNDRIES?
If GLOBALFOUNDRIES has sharpened your curiosity, now is the time to widen your opportunity set before the next wave of earnings resets expectations again.
- Target quality at a discount by scanning companies that screen well on value and fundamentals using our 32 high quality undervalued stocks.
- Prioritise resilience by filtering for businesses with strong balance sheets and solid financial footing through the list of solid balance sheet and fundamentals (23 results).
- Spot potential early movers by reviewing a curated pool of strong fundamental stories that the market has not fully focused on yet in the 20 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com