
Raised Revenue Guidance Might Change The Case For Investing In Sarepta Stock (SRPT)
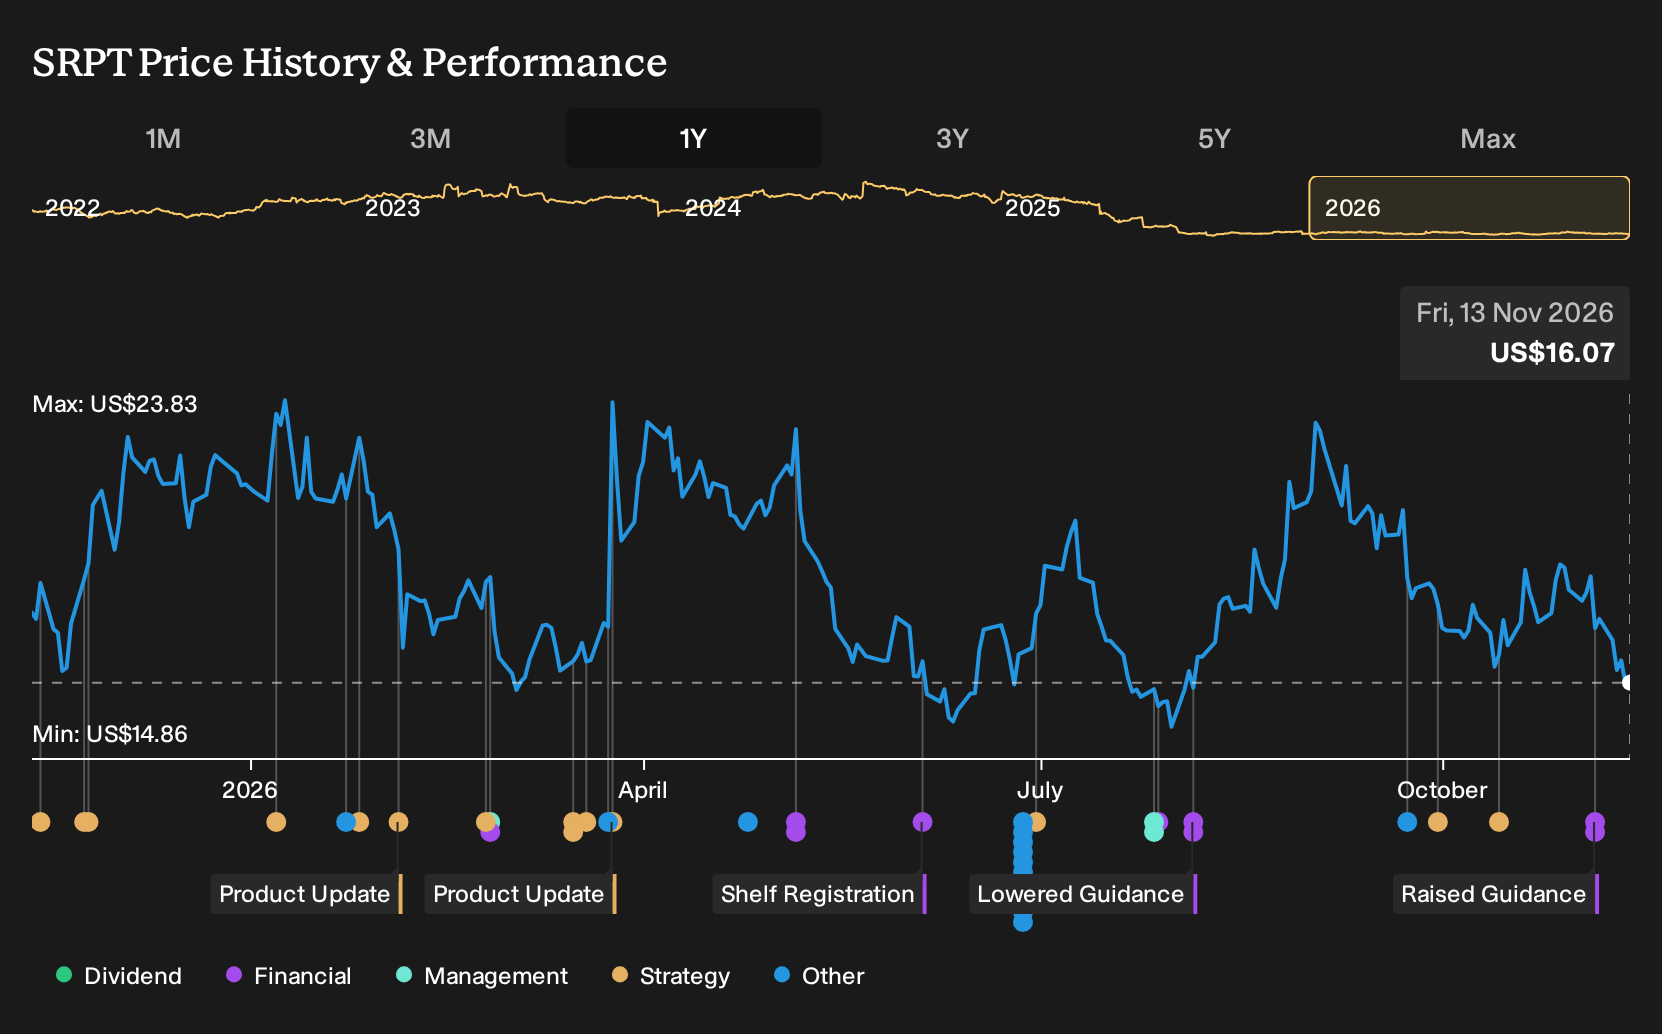
- In early November, Sarepta Therapeutics raised its 2026 total net product revenue guidance, lifting the low end by US$50 million to a range of US$1.25b to US$1.3b. The company also reported third quarter 2026 revenue of US$381.35 million and a quarterly net loss of US$28.46 million.
- Across the first nine months of 2026, Sarepta Therapeutics reported revenue of US$1.513b and moved from a loss to net income of US$297.61 million, with earnings per share turning positive on both a basic and diluted basis.
- We will now explore how Sarepta Therapeutics’ improved nine month profitability could shape the existing investment narrative around funding its pipeline.
Scan how Sarepta Therapeutics compares with other potential breakout opportunities by reviewing our curated list of 20 high quality undiscovered gems across the market.
Sarepta Therapeutics Investment Narrative Recap
To hold Sarepta Therapeutics, you need to believe its Duchenne portfolio and early siRNA programs can sustain enough cash generation to keep funding research without constant new equity. The raised 2026 revenue guidance points to management seeing a more supportive commercial backdrop, even though the third quarter still carried a net loss.
The analyst consensus Narrative on Simply Wall St highlights ELEVIDYS risk management and siRNA progress as key to the story. Recent nine month profitability gives Sarepta more flexibility to absorb any bumps from safety scrutiny, infusion bottlenecks or rising R&D, but those operational frictions around gene therapy access and competitive exon skipping pressure remain very real.
The most relevant recent announcement is the uplift to 2026 total net product revenue guidance to US$1.25b to US$1.3b. That sits against third quarter revenue of US$381.35 million and a quarterly net loss of US$28.46 million, so near term execution still looks uneven even as the full year view tightens.
For catalysts, investors are watching whether this higher guidance translates into consistent cash flow that can support ELEVIDYS safety work and siRNA programs in FSHD and DM1 without squeezing margins too hard. The flip side is clear. Any renewed safety event, fresh administrative delays, or competitive erosion in the PMO franchise could quickly test the confidence implied by that revised outlook.
Sarepta Therapeutics' current earnings are a loss of $136.7 million, while analysts collectively expect earnings to reach $36.4 million by 2029, which implies an earnings increase of about $173 million. This outlook also assumes revenue will be $1.3b in 2029 and that top line performance will decline by 13.0% each year over the next three years.
Uncover why Sarepta Therapeutics' fair value indicates a 36% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Some of the most optimistic Sarepta Therapeutics analysts focus less on near term ELEVIDYS bottlenecks and more on earnings power. Before this guidance lift, the bullish group was already modeling about US$1.4b of revenue and US$159.6 million of earnings by 2029. That is far more upbeat than consensus, so this new information could push their narrative even further apart. Readers can use that gap to stress test their own view.
Explore 3 other Sarepta Therapeutics fair value estimates, including one that suggests as much as 129% upside from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis.
- A useful starting point for your Sarepta Therapeutics research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Sarepta Therapeutics. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to review Sarepta Therapeutics' overall financial position at a glance.
Looking For More Sarepta Therapeutics Investment Ideas?
If Sarepta Therapeutics has sharpened your focus on where risk and reward might line up next, it can help to compare it with a wider field of potential opportunities using the Simply Wall St Screener.
- If you are hunting for mispriced quality, scan a curated set of 32 high quality undervalued stocks that combine stronger fundamentals with more modest expectations baked into current prices.
- If capital preservation is higher on your list than aggressive upside, focus on a group of 29 resilient stocks with low risk scores that score well on balance sheet strength and volatility.
- If you want cleaner finances and fewer funding surprises, line Sarepta up against a list of solid balance sheet and fundamentals (23 results) and see which businesses maintain sturdier financial footing.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com