
Wizz Air Holdings (LSE:WIZZ) Faces A 10% Fair Value Gap Following Mixed Earnings
Wizz Air Holdings (LSE:WIZZ) has just released second quarter and half year earnings, putting fresh detail around revenue trends, profitability and per share performance that many investors will watch closely.
Recent trading suggests investors are reacting to the fresh earnings detail. The 1 month share price return of 16.37% and 7 day share price gain of 7.44% point to improving short term momentum, even though the year to date share price return is down 12.5% and the 3 year total shareholder return is down 38.26%.
Spot similar earnings-driven setups to Wizz Air Holdings by scanning our curated list of 6 high quality undiscovered gems.For Wizz Air Holdings, this sharp rebound comes just after earnings that combine higher quarterly profit with weaker half-year per-share figures. That raises a simple puzzle: Is the market repricing the business or is this just mood music?
Most Popular Narrative: 10% Overvalued
On the analyst consensus Narrative on Simply Wall St, Wizz Air Holdings screens as modestly overvalued, with a fair value of £10.41 against the latest close at £11.41, so the recent rebound is sitting above that assessed range while hinging on execution improving earnings quality.
Management has rephased the Airbus order book so that fleet growth of about 7% is expected to translate into roughly 11 to 12% ASK growth by FY30, which is intended to support sustainable capacity expansion at larger scale and improve earnings through route maturity effects.
See why 35 investors see Wizz Air Holdings as 10% overvalued.
Result: Fair Value of £10.41 (OVERVALUED)
Still, the narrative can crack if high network churn keeps routes immature or if elevated maintenance and depreciation costs linger longer than Wizz Air Holdings expects.
Find out about the key risks to this Wizz Air Holdings narrative.
Another View: What Multiples Say About Wizz Air Holdings
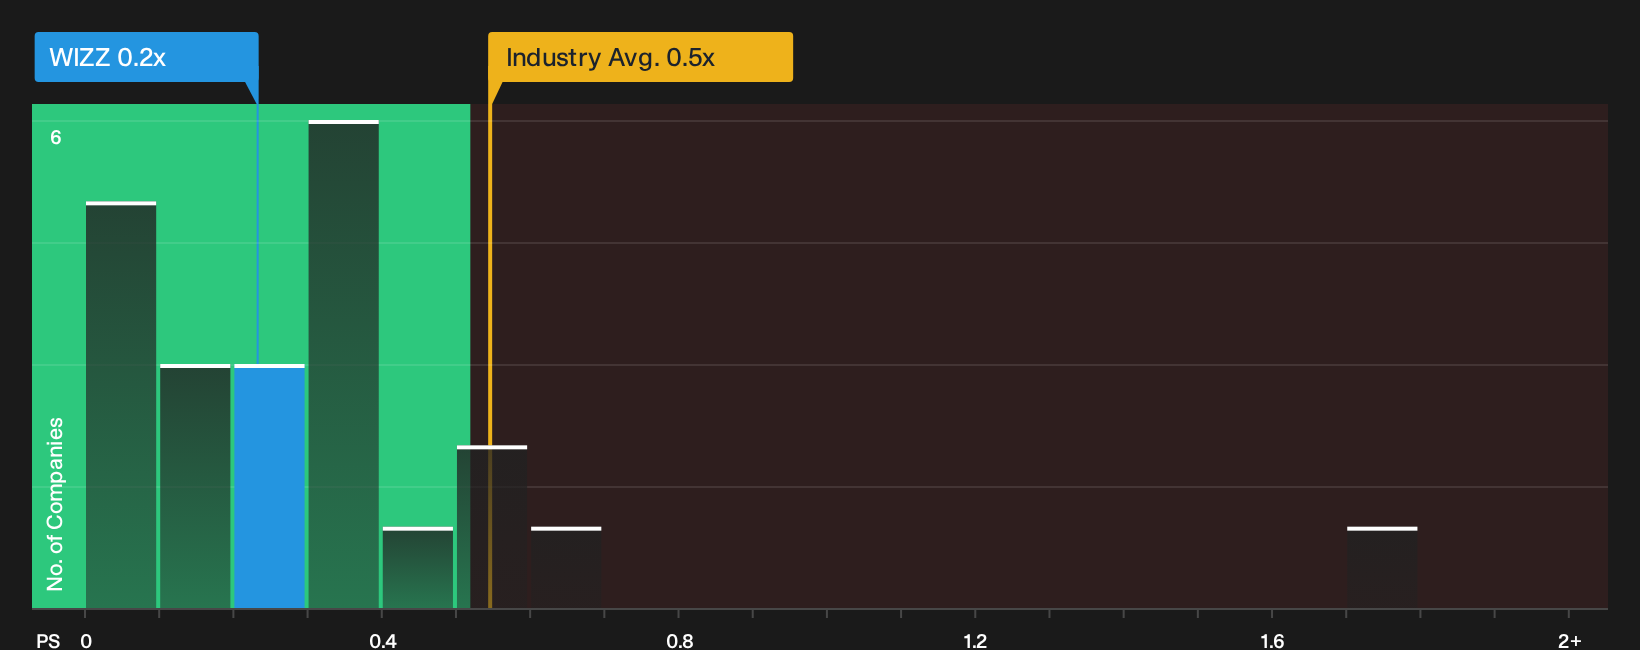
The DCF narrative paints Wizz Air Holdings as overvalued around £11.41 compared with a fair value near £10.41. The picture looks very different on sales based measures. At a P/S of 0.2x versus peers at 0.5x and a fair ratio of 0.4x, the stock screens as cheap on headline revenue. Which story do you trust when the signals clash?
See what the numbers say about this price in our valuation breakdown, then weigh it against how you think Wizz Air Holdings can actually use its fleet and route plan to lift earnings quality over time. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Curious whether this upbeat read on Wizz Air Holdings matches your own instincts? Pull up the underlying numbers, pressure test the assumptions, and then weigh those optimistic reward signals for yourself with 3 key rewards.
Looking for more investment ideas beyond Wizz Air Holdings?
If Wizz Air Holdings has sharpened your thinking, do not stop with a single stock. Broaden your watchlist now so you are not late to the next opportunity.
- Target dependable balance sheets and steady fundamentals by scanning our list of solid balance sheet and fundamentals (9 results).
- Hunt for potential mispricings by running through a curated set of 15 high quality undervalued stocks.
- Prioritise resilience over drama by focusing on a 5 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com