
3 Japanese Quality Stocks For November 2026
AI hardware trade is surging, with AI related goods driving most of global goods trade growth in early 2026 and East Asia at the center of that supply chain. Japanese companies with strong balance sheets, high return on equity and solid track records sit in an interesting spot as this wave unfolds. This article highlights three financially resilient Japanese stocks from that universe that may merit a closer look.
The three stocks profiled next are only a sample, as the full screen surfaced 21 more Japanese companies with solid balance sheets, high return on equity and consistent fundamentals that are not covered in the article. To see the complete list and start sorting through potential high conviction ideas, head straight into the Solid Balance Sheet and Fundamentals screener
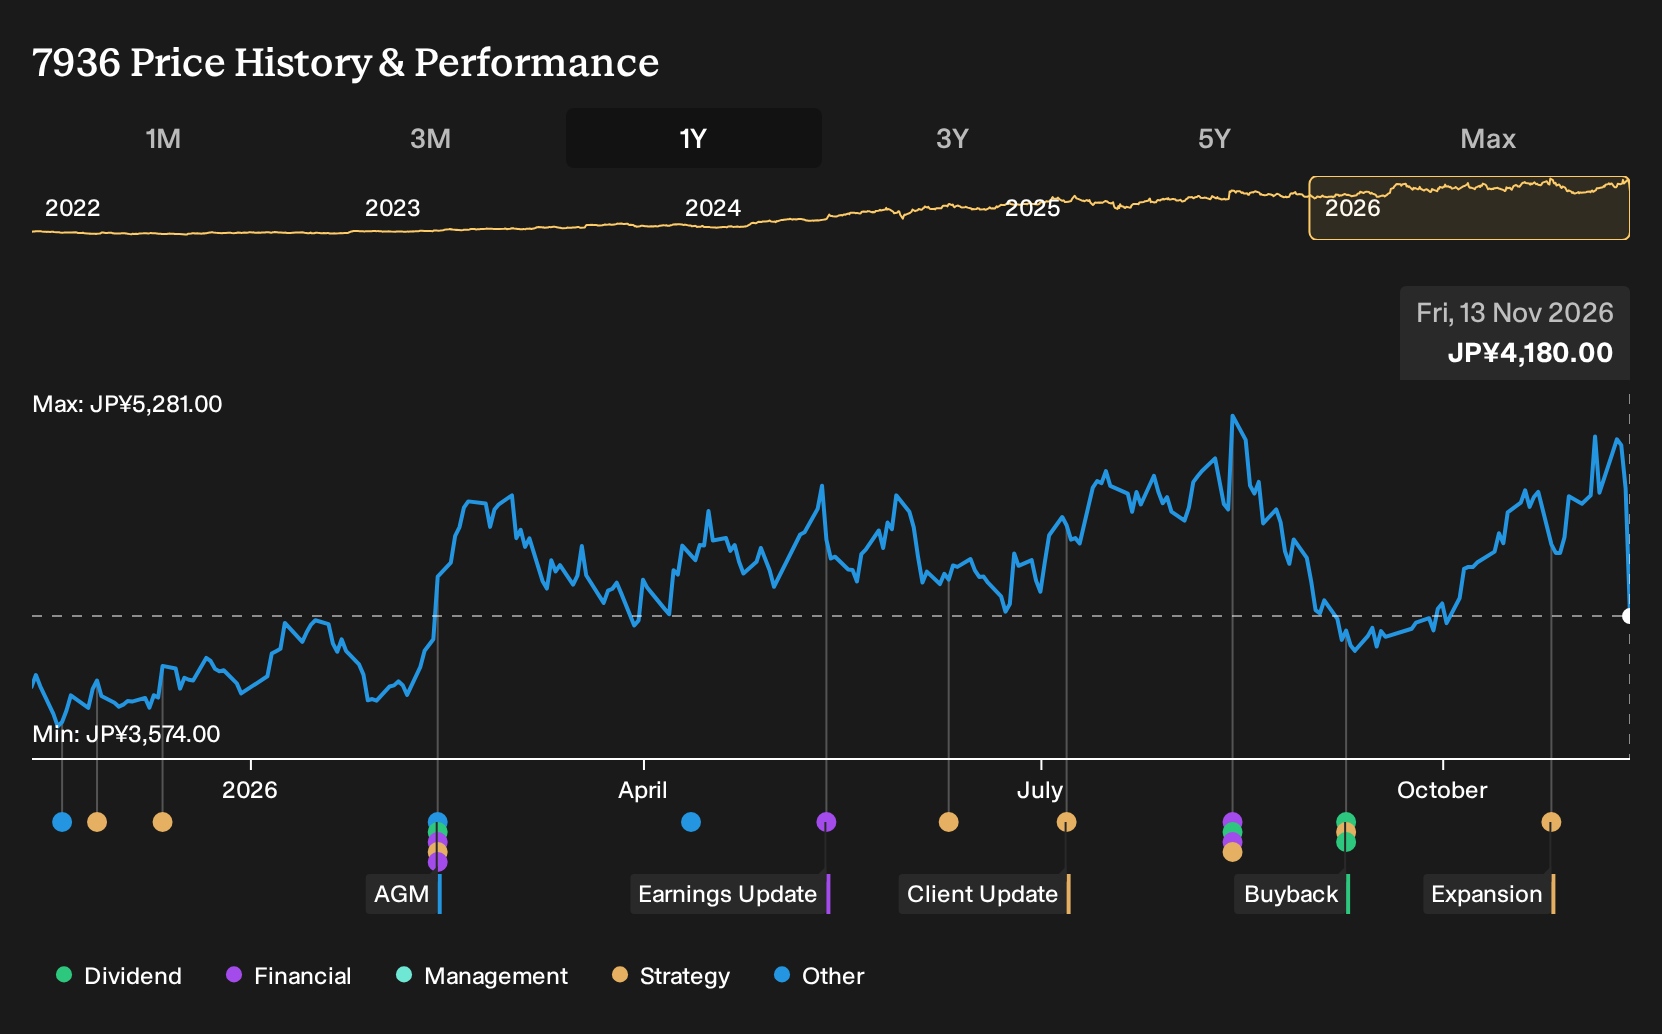
ASICS (TSE:7936)
ASICS is a Kobe based sportswear group best known for its premium running shoes. These anchor the solid balance sheet and fundamentals theme by supporting steady footwear sales worldwide across Japan, Europe, North America and Greater China. Recent annual revenue by region includes ¥278.6b from Europe and ¥211.1b from Japan, and the business carries a market value of about ¥2,858.7b.
ASICS taps its premium running and performance footwear to support strong margins, high return on equity and a healthy balance sheet, then backs that up with rising dividends and active share buybacks. The investment case turns on what happens when that core running engine meets one unseen pressure on future pricing power.
That pricing pressure question is exactly why it is worth pulling up the 4 key rewards and 1 important warning sign to see what the balance sheet strength may be masking.
Sansan (TSE:4443)
Sansan runs a cloud contact and document management suite that helps corporations turn business card data, invoices and contracts into shared sales intelligence, linking neatly to the solid balance sheet and fundamentals theme. The Sansan/Bill One segment produced about ¥48.9b, Eight added roughly ¥7.1b, and the group is valued at about ¥275b.
Sansan ties its solid balance sheet profile to a software model that already carries net profit margins near 14.3% and guidance pointing to ¥63.7b to ¥65.3b in fiscal 2027 net sales with ¥12.5b to ¥14.5b in operating profit. The scale of that earnings power, and any factors that affect how efficiently clients adopt more modules, will matter a lot.
That adoption curve is exactly where you may want to pull up the analyst forecasts for Sansan to see how Sansan's model could scale before sentiment fully catches up

Oracle Corporation Japan (TSE:4716)
Oracle Corporation Japan runs database, cloud and enterprise software that fits the screener’s focus on high return on equity from recurring cloud and software contracts. It has a market value of about ¥1.31t, which reflects the scale of its Japan focused enterprise footprint.
The cloud heavy software engine at Oracle Corporation Japan speaks directly to the Solid Balance Sheet and Fundamentals theme, and the bearish analyst Narrative on Simply Wall St frames the key debate over how durable that high quality profit stream really is.
Although AI functions are embedded across Oracle Corporation Japan products and visible in projects such as predictive maintenance at ITOKI and AI document search at the Ministry of Health, Labour and Welfare, slower replication of these use cases into other industries could limit the uplift to cloud consumption and consulting profit margins.
The real test is what happens if a single assumption about how quickly enterprises deepen their cloud commitments quietly stops holding.
If that core assumption is starting to wobble, the full narrative for Oracle Corporation Japan shows how Oracle Corporation Japan could still convert AI workloads into accelerating cloud and profit momentum.

Seeking Fresh Paths For Your Curiosity?
Markets move fast and the most interesting ideas often gain momentum before headlines catch up. Scan these fresh stock shortlists while they are still under the radar for now and consider them while they are still early in wider coverage.
- Explore emerging yield opportunities and stress test your income plan against the curated 28 dividend fortresses to understand how different payout profiles might fit your objectives.
- Track powerful secular themes by scanning the focused 53 AI infrastructure stocks while these backbone providers of AI capacity are still less widely followed.
- Examine structural commodity trends with the hand picked 17 top copper producer stocks to see how various supply and demand scenarios could affect the landscape.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com