
Did AAK AB (publ.)'s Fall Catch You Out? What Bears Saw
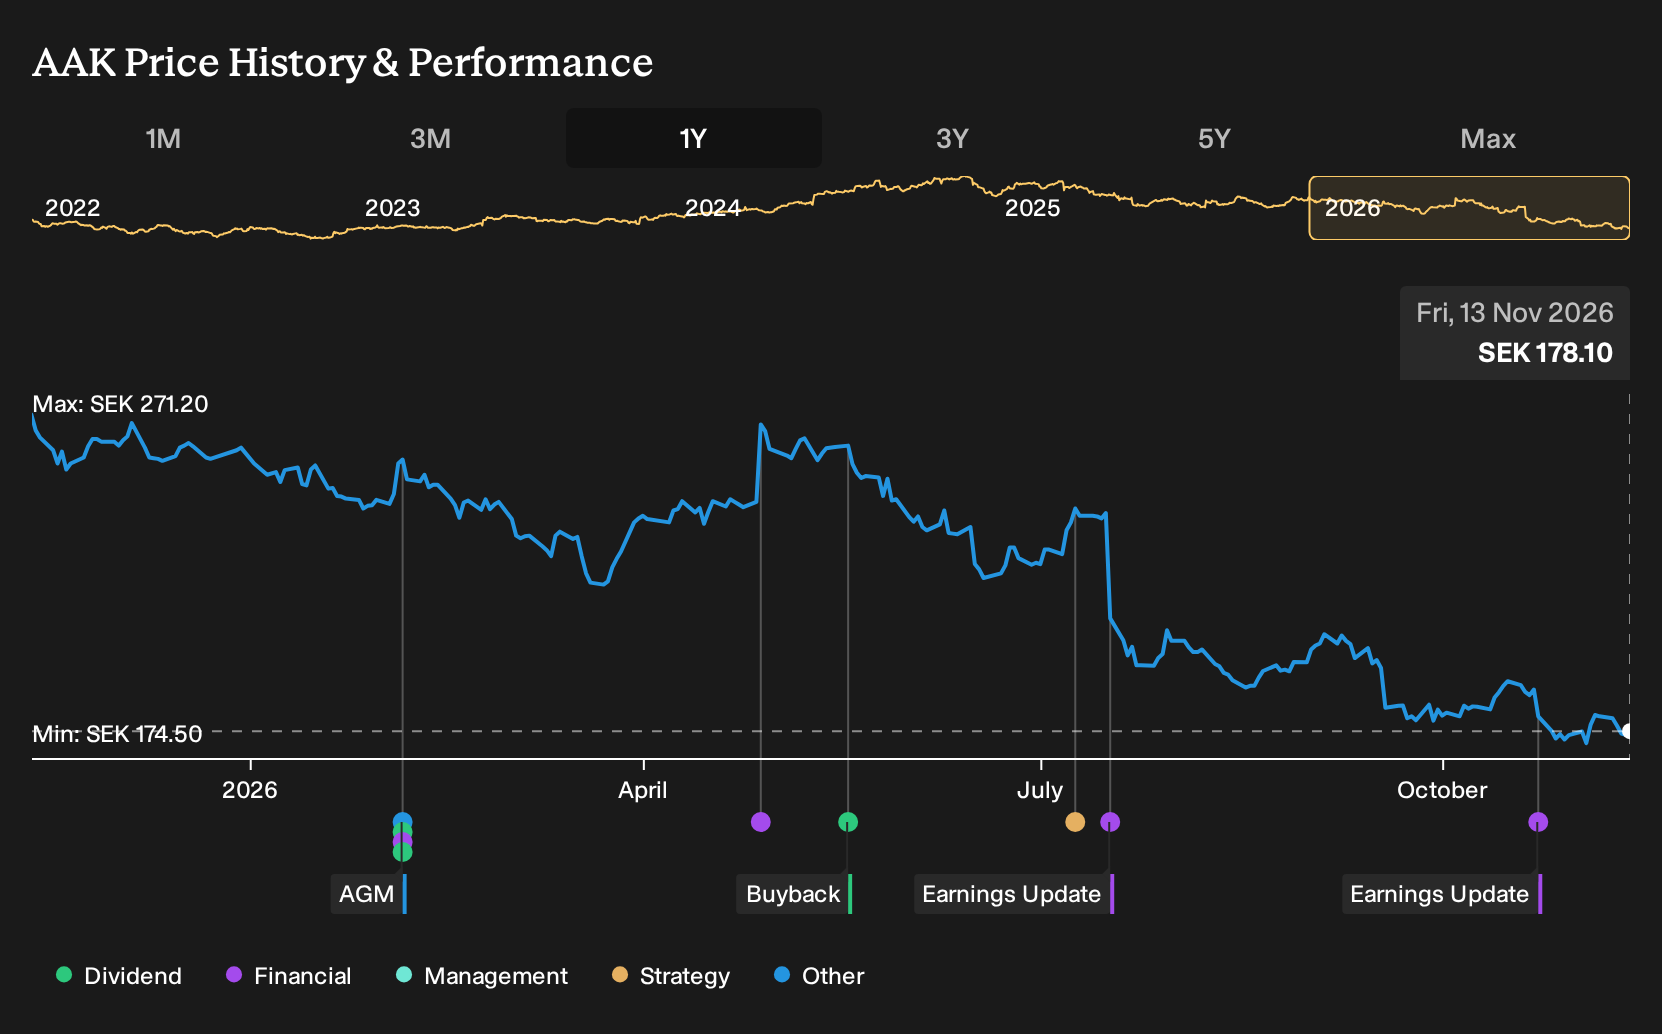
If you had backed AAK AB (publ.) on the promise of steady plant-based demand, ESG tailwinds and efficiency gains, the past year would have felt harsh. For AAK AB (publ.) shareholders, the loss over the past year was 30.8%, including dividends. That outcome sits uncomfortably against earlier expectations for modest revenue growth, firmer profit margins and a mid teens uplift to fair value. If those were your assumptions, which part of that original case did not allow for what actually unfolded?
If the move has made AAK AB (publ.) harder to judge, start where the gap is still open and scan 195 high quality undervalued stocks.
The Two Stories Investors Had To Choose Between On AAK AB (publ.)
The shares cost SEK269 at the start of the period, and investors were really choosing between two credible stories about where AAK AB (publ.) might head next.
The bullish script pointed to a Fair Value of SEK308, a price implied by assumptions of 1.0% revenue growth, a 9.9% profit margin and a future P/E of 19.6x over roughly three years.
The cautious view used a Fair Value of SEK245, reflecting concerns about food ingredient volumes, rising input costs and tighter regulation.
What The Results Changed For The AAK AB (publ.) Thesis
The Q3 2026 report gave AAK AB (publ.) investors mixed evidence. Revenue moved from SEK11,498m in Q3 2025 to SEK11,910m in Q3 2026, which leaned toward the bullish expectation of modest top line growth. Profit told a different story, with net income slipping from SEK909m to SEK837m and net margin easing from 7.9% to 7.0%. The period cut both ways.
The key assumption here was not just that sales could grow, but that earnings quality and margin strength would follow. When you test another company, line up that claim directly against net income and reported net margin quarter by quarter to see if the story is actually playing out.
What AAK AB (publ.) Buyers Are Really Paying For Today
AAK AB (publ.) now trades at SEK178, well below where it started one year ago. The analyst consensus Narrative on Simply Wall St sets its Fair Value above that price and attributes the gap to margin quality, product mix and cash discipline rather than a simple volume rebound.
Your decision today comes down to execution. A buyer at SEK178 would be assuming AAK AB (publ.) can continue improving its mix toward higher value fats while delivering its Fit to Win and Cash to Grow targets under ongoing competitive and operational pressure.
"The main thing that has to go right is that AAK AB (publ.) successfully executes its profitability and efficiency programs, including Fit to Win and Cash to Grow, while managing competitive pressure and production disruptions in Food Ingredients."
One Narrative has put a figure on that disagreement. → See the Narrative with its higher Fair Value, assumptions and all
Go Straight To The Source
The next headline does not have to be where your research begins. Go straight to the companies and see whether a contrarian opportunity could be taking shape.
- Company 1 - 29% below our estimate - targets a larger share of platform inflows using one core tech stack.
- Company 2 - 47% below our estimate - supplies full-stack AI factory hardware and software to cloud and neocloud customers.
- Company 3 - 36% below our estimate - handles AI related freight and customs work as compliance workloads become more complex.
That is three of the list. See every one of the 197 solid balance sheet companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com