
Nishimatsu Construction (TSE:1820) Moved, What Is Behind The Fresh Attention?
Nishimatsu Construction (TSE:1820) moved back into focus after its October 30 board meeting approved interim dividends funded from retained earnings, aligning the ¥110 per share payout with previously announced guidance.
Nishimatsu Construction’s interim dividend decision lands as momentum has been picking up, with a 13.68% 7 day share price return and an 11.30% 30 day share price return. The 1 year total shareholder return of 12.57% sits on top of much stronger 3 and 5 year gains that hint at interest building around the longer term story.
Scan other construction and infrastructure plays showing similar dividend momentum and balance sheet strength using our hand picked list of solid balance sheet and fundamentals (24 results) as a starting universe around Nishimatsu Construction.
Nishimatsu Construction now offers a richer dividend stream and a stronger recent share price run, but do those positives leave the stock fairly valued or already priced for strength?
Price-to-Earnings of 7.9x: Is it justified?
Nishimatsu Construction trades on a P/E of 7.9x, and that multiple sits below both peers and the wider Japanese market despite the recent share price strength around ¥5,809.
The P/E ratio compares what you pay today for each unit of earnings, so for a construction contractor like Nishimatsu Construction it gives a quick read on how investors are weighing current profits against future expectations.
Here the stock changes hands at a discount to the JP Construction industry average of 10.7x and to the peer group on 13x. The estimated fair P/E from the SWS fair ratio work sits at 9x, which indicates that the present market pricing is more conservative than those reference points and that there could be scope for the valuation multiple to move closer to that fair level if sentiment shifts.
Explore the SWS fair ratio for Nishimatsu Construction.
Result: Price-to-Earnings of 7.9x (UNDERVALUED)
Still, the narrative around Nishimatsu Construction can be shaken by declining annual net income growth and by any hit to large infrastructure or real estate project pipelines.
Find out about the key risks to this Nishimatsu Construction narrative.
Another View: DCF points the other way
The P/E story painted Nishimatsu Construction as attractively priced, yet the SWS DCF model points in a different direction. On that cash flow view, the estimated value sits at ¥3,802.03 per share while the current price is ¥5,809. That gap frames the stock as overvalued on this method and raises the question of which lens investors should treat as their anchor.
Look into how the SWS DCF model arrives at its fair value.
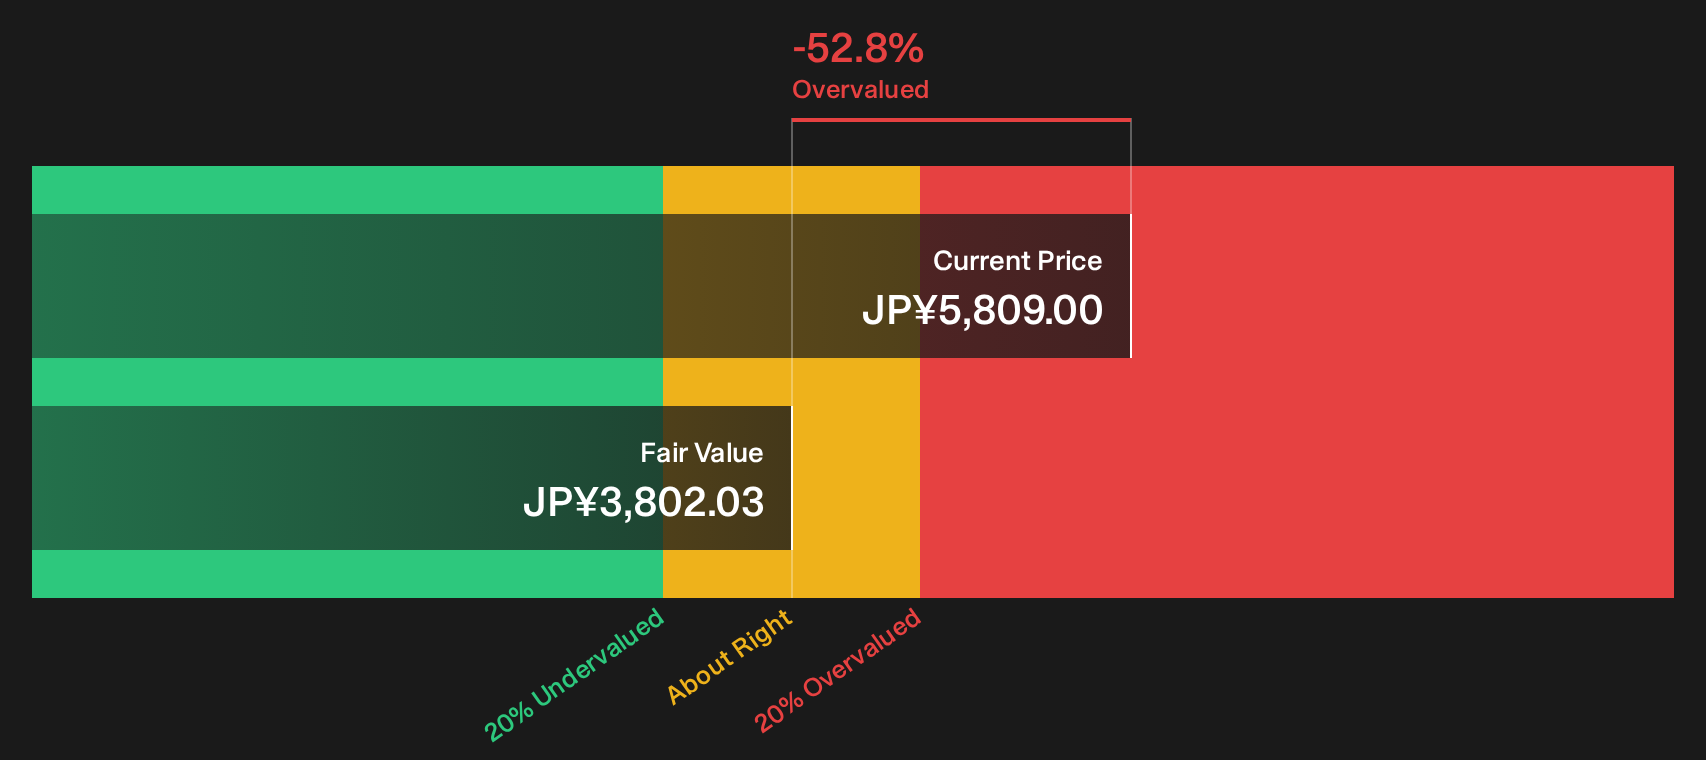
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Nishimatsu Construction for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 19 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Conflicted about the mixed messages around Nishimatsu Construction and its current valuation signals? Act promptly and consider both sides of the story by reviewing the 3 key rewards and 3 important warning signs
Looking for more investment ideas beyond Nishimatsu Construction?
If you are weighing what to do next after reviewing Nishimatsu Construction, broaden your watchlist with fresh ideas filtered by quality, value, and resilience.
- Target potential mispricing by scanning a universe of quality opportunities through the 19 high quality undervalued stocks, which filters for strong fundamentals at appealing valuations.
- Strengthen your income stream by reviewing the 28 dividend fortresses, focused on companies combining higher yields with more robust financial profiles.
- Lower the probability of painful surprises by starting with the 20 resilient stocks with low risk scores, built around businesses that carry more resilient risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com