
How Updated Guidance At Kawasaki Kisen Kaisha Stock Has Changed Its Investment Story
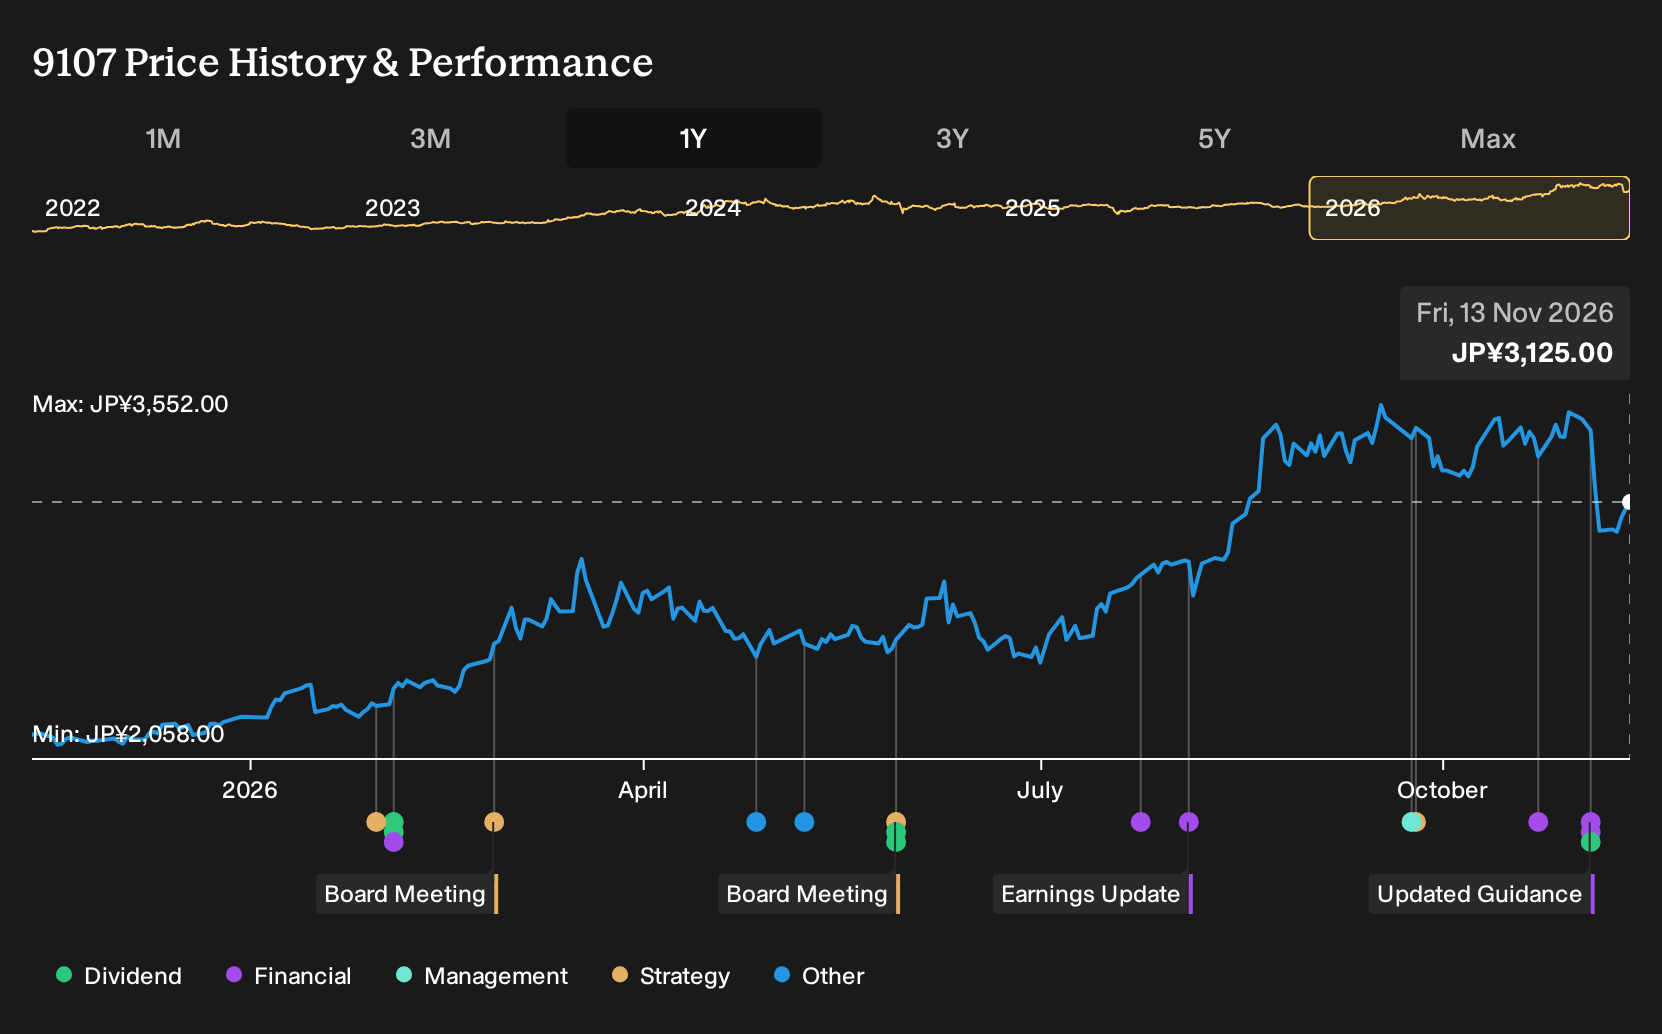
- Kawasaki Kisen Kaisha updated its earnings outlook, including a 2031 net income target of ¥120.0b and fresh FY 2027 guidance, while affirming a ¥60.00 interim dividend per share scheduled for payment on December 3, 2026.
- The mix of long dated income targets, current year profit guidance and an unchanged dividend highlights how Kawasaki Kisen Kaisha is addressing near term shipping pressures while maintaining an emphasis on predictability for cash generation and shareholder returns.
- This article will examine how Kawasaki Kisen Kaisha's refreshed earnings guidance interacts with its existing investment narrative around cash generation.
Kawasaki Kisen Kaisha Investment Narrative Recap
To own Kawasaki Kisen Kaisha, you need to be comfortable with a shipping group that relies on long term energy transport contracts and a solid balance sheet to offset pressure in dry bulk, container and car carrier markets. The analyst consensus Narrative on Simply Wall St already highlights ongoing earnings pressure, so the 2031 net income goal mainly frames management’s ambition rather than changing the near term story.
Currently, the key short term swing factor is how quickly weaker freight markets feed through to margins and equity method earnings from container shipping. That risk is already elevated, and the new guidance plus the 2031 target does not materially change that near term earnings sensitivity.
The most relevant disclosure for you as a shareholder is the FY 2027 consolidated guidance. Management now expects operating revenue of ¥1,170,000m, operating income of ¥91,000m and profit attributable to owners of parent of ¥190,000m, with profit per share of ¥316.46. These figures provide a concrete reference point against the earlier consensus view of earnings pressure.
These numbers matter because they sit between two moving parts. On one side, sector wide overcapacity and weaker container and dry bulk conditions that could keep pressure on profitability. On the other side, long dated LNG and energy transport contracts plus the reaffirmed ¥60.00 interim dividend, which indicate that Kawasaki Kisen Kaisha is still planning around steady cash generation, even if headline profit remains under strain.
Kawasaki Kisen Kaisha's narrative projects ¥1,189.9b revenue and ¥144.7b earnings by 2029, which builds on analyst assumptions of 2.0% yearly revenue growth and implies an earnings decline of ¥44.2b from ¥188.9b today.
Uncover how Kawasaki Kisen Kaisha's fair value indicates a 3% potential downside to its current price, suggesting that the premium may not hold.
Exploring Other Perspectives
One alternate view leans heavily on Kawasaki Kisen Kaisha's contracted Energy Resource Transport earnings as a potential upside catalyst. Bullish analysts were pencilling in revenue of ¥1,670.3b and earnings of ¥169.3b by 2029 before this guidance and dividend update. You can treat that as a more optimistic script that might be rewritten as new information filters through. You can then compare it with the more cautious consensus to see where your own expectations land.
Explore 2 other Kawasaki Kisen Kaisha fair value estimates, including one that suggests the potential for as much as 28% upside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your Kawasaki Kisen Kaisha research is our analysis highlighting 1 key reward and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Kawasaki Kisen Kaisha. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Kawasaki Kisen Kaisha's overall financial health at a glance.
Looking For More Investment Ideas Beyond Kawasaki Kisen Kaisha?
Once you have a view on Kawasaki Kisen Kaisha, it can help to compare it with companies that share similar qualities or offer a very different risk and income profile. The Simply Wall St Screener gives you a structured way to do that without getting lost in ticker hunting.
- If capital preservation is your first filter, start with a basket of companies that have lower risk scores and more resilient profiles through our 20 resilient stocks with low risk scores.
- Income focused investors who want yield backed by fundamentals can review a focused set of high payout opportunities through the 28 dividend fortresses.
- For those who like to get in early on underfollowed stories, scan a curated group of strong fundamental outliers using the 72 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com