
What Murphy Oil Holders Bought Into
If you only read one headline on Murphy Oil this year, it was probably about the Bubale-1X discovery offshore Côte d’Ivoire and the follow-up drilling plans that put deepwater growth firmly on the table. Investors who held Murphy Oil over the past year are up 28.2%, including dividends. If you were deciding back on 12 November 2025, what would you have needed to believe about those exploration bets to feel comfortable buying in?
Murphy Oil is not the only name tied to this theme. Zero in on 17 nuclear energy infrastructure stocks and compare how each one is priced.
The Argument You Would Have Been Weighing On Murphy Oil
The shares cost US$28.85 at the start of the period. Anyone looking at Murphy Oil then had to decide whether deepwater exploration could reshape the business or whether long-run decarbonization pressures would dominate.
On the optimistic side, the bullish story pointed to a Fair Value of US$40, a price implied by assumptions about exploration success and margins. That view leaned on large prospects such as Vietnam Hai Su Vang and Côte d'Ivoire potentially adding up to one billion barrels of resources.
The cautious narrative saw Fair Value closer to US$23, again as an implied price from its own set of expectations. This camp focused on the risk that a global push toward net-zero policies would steadily erode oil demand and reduce the multiple investors might pay for Murphy Oil.
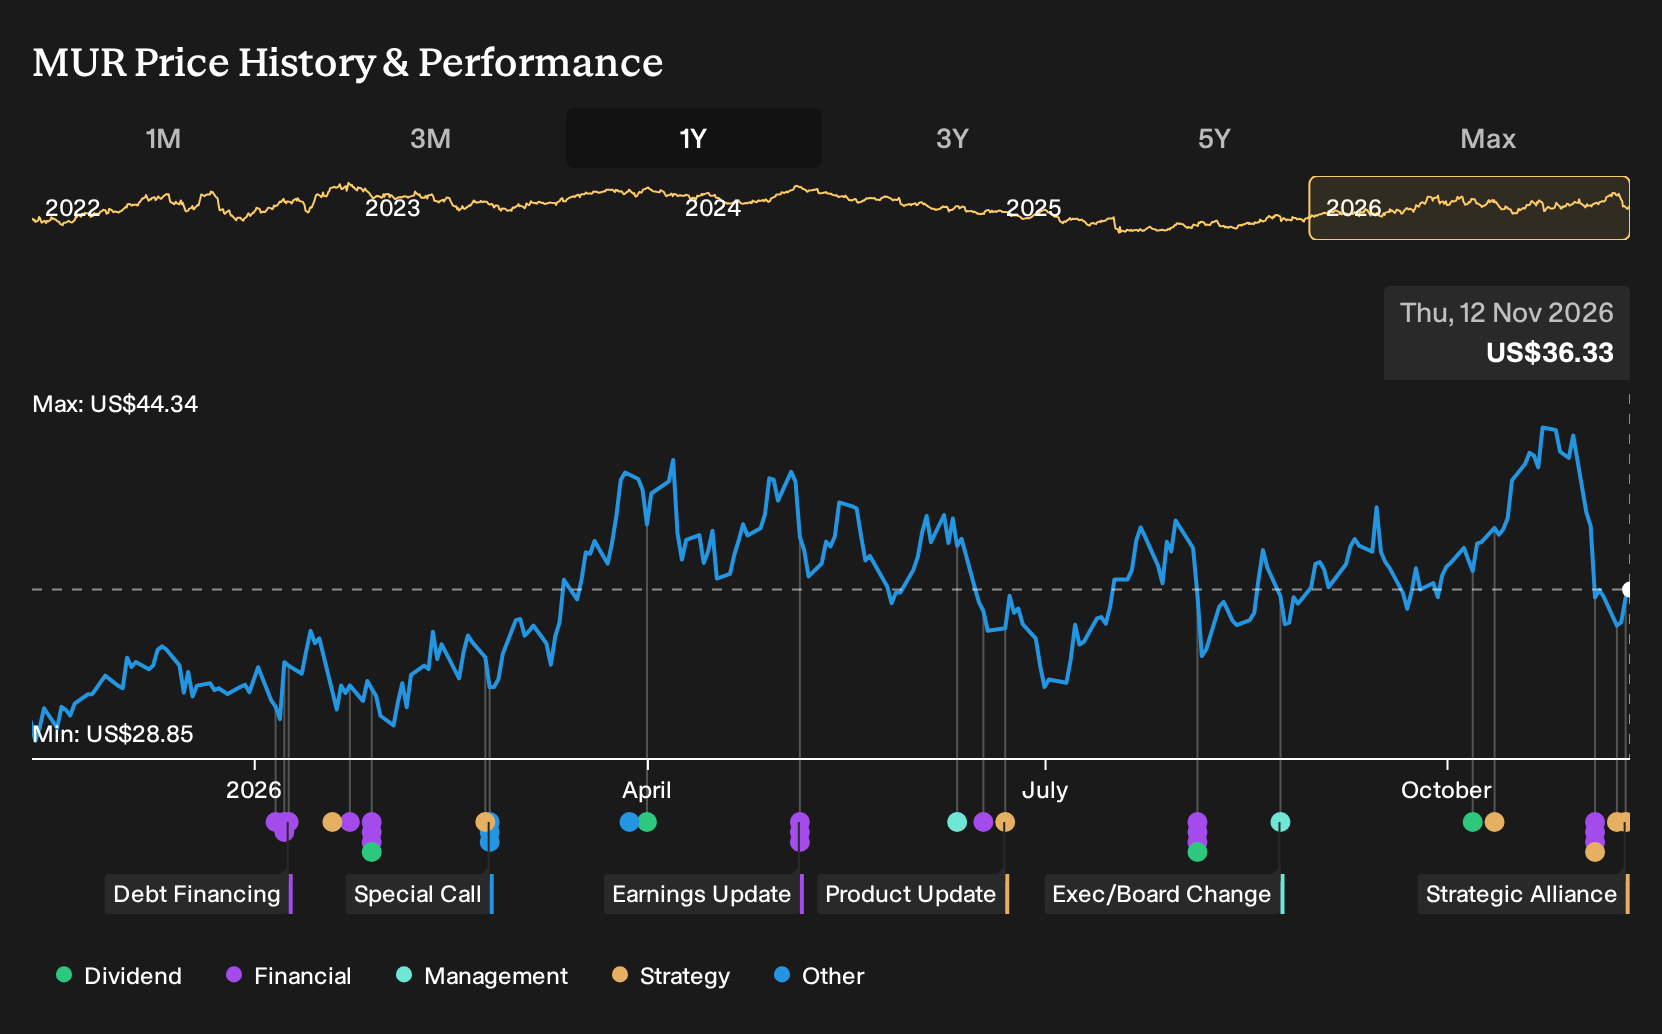
What The Results Changed For The Murphy Oil Debate
The biggest development was Murphy Oil turning a small Q3 2025 loss into Q3 2026 net income of US$171.4 million, with net margin moving from 0.3% in the red to 20.2%. That shift in profitability, together with reported offshore discoveries in Côte d’Ivoire and Vietnam, provided clear support to the optimistic view focused on exploration outcomes and stronger margins.
The takeaway is straightforward. When an investment thesis relies on high risk drilling and margin expansion, it should be tested against subsequent net income and margin figures rather than being based only on headline resource announcements.
What Murphy Oil's Recent Gain Already Prices In
Murphy Oil trades at US$36.33 today after a 28.2% gain over the past year. The bearish analyst Narrative on Simply Wall St sees Fair Value below the current price and frames that gap around how much offshore and shale execution risk investors are already accepting.
The Narrative argues today’s valuation only holds if capital heavy programs such as Bubale, Vietnam and Eagle Ford keep turning higher spending into durable output and free cash flow without stretching the balance sheet.
"Although the Bubale discovery offshore Côte d’Ivoire points to a sizeable new oil resource, the planned 18 to 24 month appraisal program with several wells and future development spending in the billions risks locking Murphy Oil into a capital heavy project where weaker appraisal results or cost creep could dilute returns and pressure future free cash flow."
That disagreement has a full argument behind it. → Uncover the lower Fair Value this Narrative argues for
Where Murphy Oil’s Theme Extends
Murphy Oil focuses on finding and producing hydrocarbons. One step away, another business concentrates on moving those molecules reliably.
Instead of drilling wells, it owns long routes that carry natural gas, liquids and crude. Those pipelines link producers with utilities, fuel buyers and power plants.
Storage sites and export terminals add another layer. They help customers shift energy between regions and balance demand over time.
As more power and data projects look to gas, that transport network could quietly become even more central to how energy actually flows.
One Narrative has already put a figure on it. → Uncover the company trading 21% below one Narrative's Fair Value
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com