
Haemonetics (HAE) Lifts 2027 Guidance Following Q2 Earnings, Is It Fully Priced?
Haemonetics earnings and guidance reset the story
Haemonetics (HAE) has investors’ attention after second quarter results showed higher sales and profit than a year earlier, along with an increase in fiscal 2027 revenue growth guidance to a range of 8% to 11%, up from the prior range of 5% to 8%.
Recent trading has been strong. Haemonetics’ share price is up 35.14% over the past 90 days and the stock has a 53.43% year to date share price return, while the 1 year total shareholder return of 66.03% suggests that momentum has been building rather than fading.
Scan beyond Haemonetics to see how other hospital technology and medtech stocks stack up in our hand picked list of solid balance sheet and fundamentals (23 results) that may be positioned for their own rerating moves.
After a 66% one year total return and a raised 2027 revenue outlook, Haemonetics now trades about 15% below the average analyst target and roughly 30% under one intrinsic value estimate. Which reference point deserves more weight?
Most Popular Narrative: 8% Undervalued
Haemonetics is trading at $122.71 against a fair value from the analyst consensus Narrative on Simply Wall St of $134, which implies an 8.4% discount based on a 7.87% discount rate and analyst forecasts for revenue, earnings, and margins.
The current numbers and this narrative’s view that Haemonetics is fairly valued imply that the share price already reflects meaningful recurring cash generation, margin expansion into the mid 20s, and continued execution on plasma and MedSurg growth without requiring a step change in performance.
Enterprise wide portfolio transformation that has already lifted adjusted gross margin to 60.3% and adjusted operating margin to 25.4%, together with free cash flow conversion above 100% of adjusted net income over the last twelve months, supports the idea that a richer mix of disposables and software can help maintain net margin resilience and cash generation.
See why 9 investors see Haemonetics as 8% undervalued.
Result: Fair Value of $134 (UNDERVALUED)
Still, rising tariff costs and Haemonetics’ US$1.2b debt load could squeeze margins and limit flexibility if revenue or cash generation softens from current expectations.
Find out about the key risks to this Haemonetics narrative.
Another View: Haemonetics on richer earnings multiples
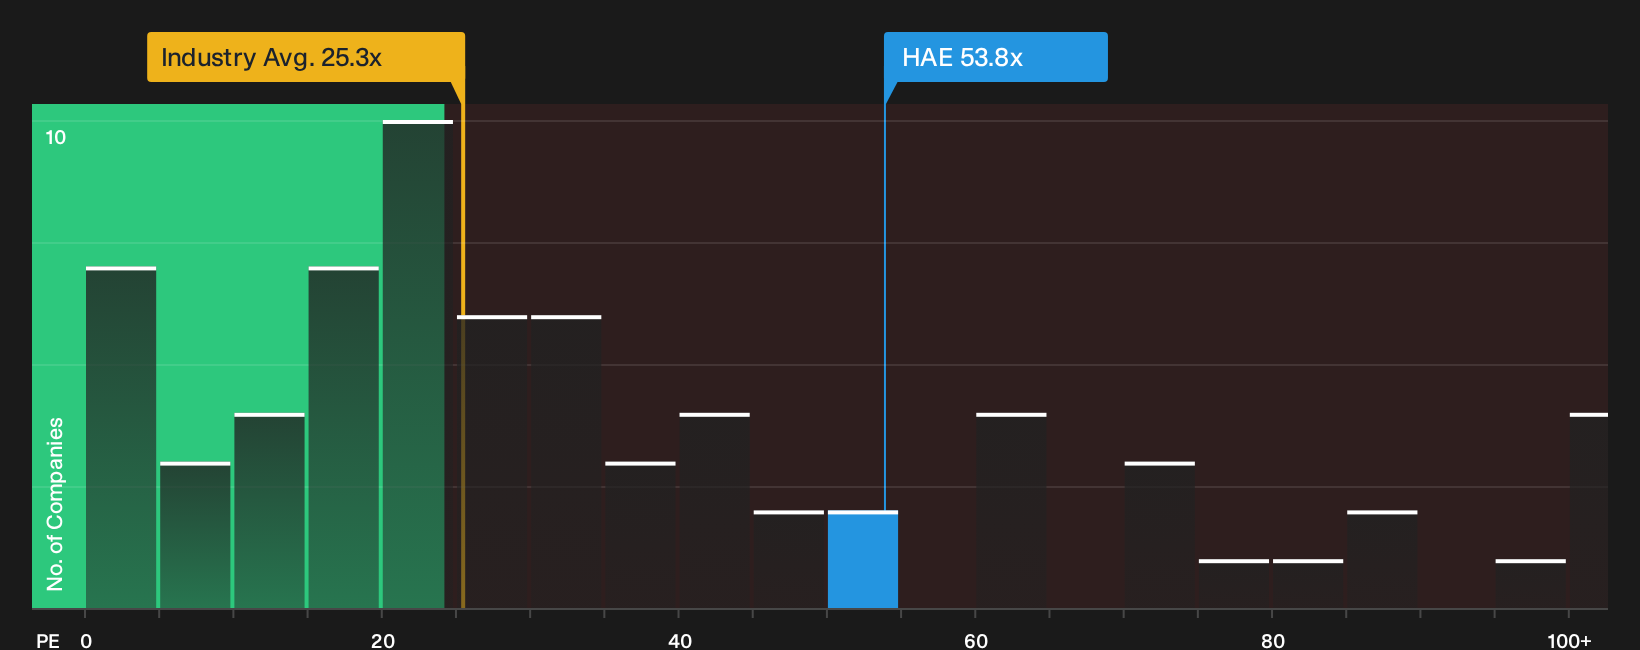
On earnings multiples, Haemonetics looks far less forgiving. The stock trades on a P/E of 53.8x compared with 26x for the US Medical Equipment group and a fair ratio of 34.2x. That premium prices in a lot of future execution. How comfortable are you paying up for it?
Investors who want to see how this earnings based view lines up against a more cash flow driven approach can review the SWS model in detail here, starting with the full breakdown in the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Haemonetics is mixed, with strong recent returns but real questions on valuation and balance sheet risk. Act quickly, review both sides of the story, and weigh the 2 key rewards and 3 important warning signs
Looking for more investment ideas beyond Haemonetics?
If Haemonetics has sharpened your focus on quality, now is the moment to widen your search and let data rich screeners surface your next candidate before the crowd.
- Target resilient performers by reviewing a focused 29 resilient stocks with low risk scores that highlights businesses with more controlled risk profiles and sturdier fundamentals.
- Hunt for mispriced quality through a curated 32 high quality undervalued stocks that filters for stronger balance sheets and healthier cash generation relative to current valuations.
- Spot under followed opportunities early by scanning a concentrated 20 high quality undiscovered gems that zeroes in on companies with solid metrics but limited market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com