
3 U.S. Energy Stocks That Could Benefit From Higher Fuel Prices
Fuel prices are on the move again as US wholesale inflation runs hot and the latest 0.3% PPI reading for October keeps pressure on input costs. That kind of squeeze can affect some parts of the market while creating fresh openings elsewhere. This piece walks through three U.S. energy sector stocks exposed to the current fuel shock and explains how the same inflation story can present opportunity or risk depending on where you look.
The three stocks highlighted below are just a sample, and the full investing idea screen surfaced 25 more U.S. energy producers and refiners with equally compelling stories that are not covered here.
If you want to identify potential winners from this fuel spike, go straight to the U.S. Energy Sector Beneficiaries of Higher Fuel Prices screener to filter, analyze, and focus on the highest conviction opportunities.
Ranger Energy Services (RNGR)
Overview: Ranger Energy Services is a U.S. oilfield services provider that supports exploration and production companies with well servicing, wireline work, and rented processing equipment that can see more demand when higher fuel prices encourage additional drilling and well maintenance.
Operations: Ranger Energy Services generates about $425 million from High Specification Rigs, $161 million from Processing Solutions and Ancillary Services, and $54 million from Wireline Services, all from U.S. operations totaling roughly $641 million in revenue.
Market Cap: $291 million
Ranger Energy Services sits right in the slipstream of the screener theme, as a U.S. well services specialist whose fortunes are closely tied to how much work upstream oil and gas producers choose to push through the field. The bearish analyst narrative on Simply Wall St frames the key tension here as less about fuel prices themselves and more about how effectively management converts a larger rig footprint into cleaner earnings.
"Although Ranger Energy Services is still working to integrate American Well Services and has early signs of progress, continued billing delays, elevated receivables and the need to harmonise price books and ERP systems point to a real risk that the planned synergy capture lags and keeps adjusted EBITDA margins below what the larger rig fleet might suggest, which would weigh on earnings quality."
What really matters for investors now is how one unresolved execution pressure ultimately shapes Ranger Energy Services' ability to turn rising activity into durable margins.
That margin question is exactly what the full narrative for Ranger Energy Services unpacks, highlighting how execution risk, contract quality, and capital discipline could be decoupling from headline activity.

Permian Resources (PR)
Overview: Permian Resources is a Midland based oil and gas producer focused on liquids heavy drilling in the Delaware Basin, giving it direct exposure to higher fuel prices.
Operations: Permian Resources generates about $6.4b in revenue from exploration and production of oil and natural gas, all from U.S. assets.
Market Cap: $18.7b
For the U.S. Energy Sector Beneficiaries of Higher Fuel Prices theme, Permian Resources matters because its Delaware Basin wells link directly into crude and liquids rich gas pricing. MRT23, an investor in the Simply Wall St Community, argues that one underappreciated infrastructure shift could change how that exposure flows through to cash generation.
"A significant embedded catalyst exists in the Waha gas basis resolution: 700+ MMcf/d of Gulf Coast and DFW firm transport capacity coming online in 2027 converts what is currently a meaningful revenue drag (Q2 2026 unhedged gas averaged -$2.40/Mcf) into a structural tailwind, and the market does not appear to be pricing this improvement"
What happens to Permian Resources' earnings power if that single friction in its pricing chain eases while fuel prices stay elevated?
If that friction is resolved in your favour, the full narrative for Permian Resources outlines how pricing, volumes, and capital choices could reshape Permian Resources' long term cash engine.

RPC (RES)
Overview: RPC is an Atlanta based oilfield services provider that supplies pressure pumping, tools, and rentals that help producers drill, complete, and maintain wells.
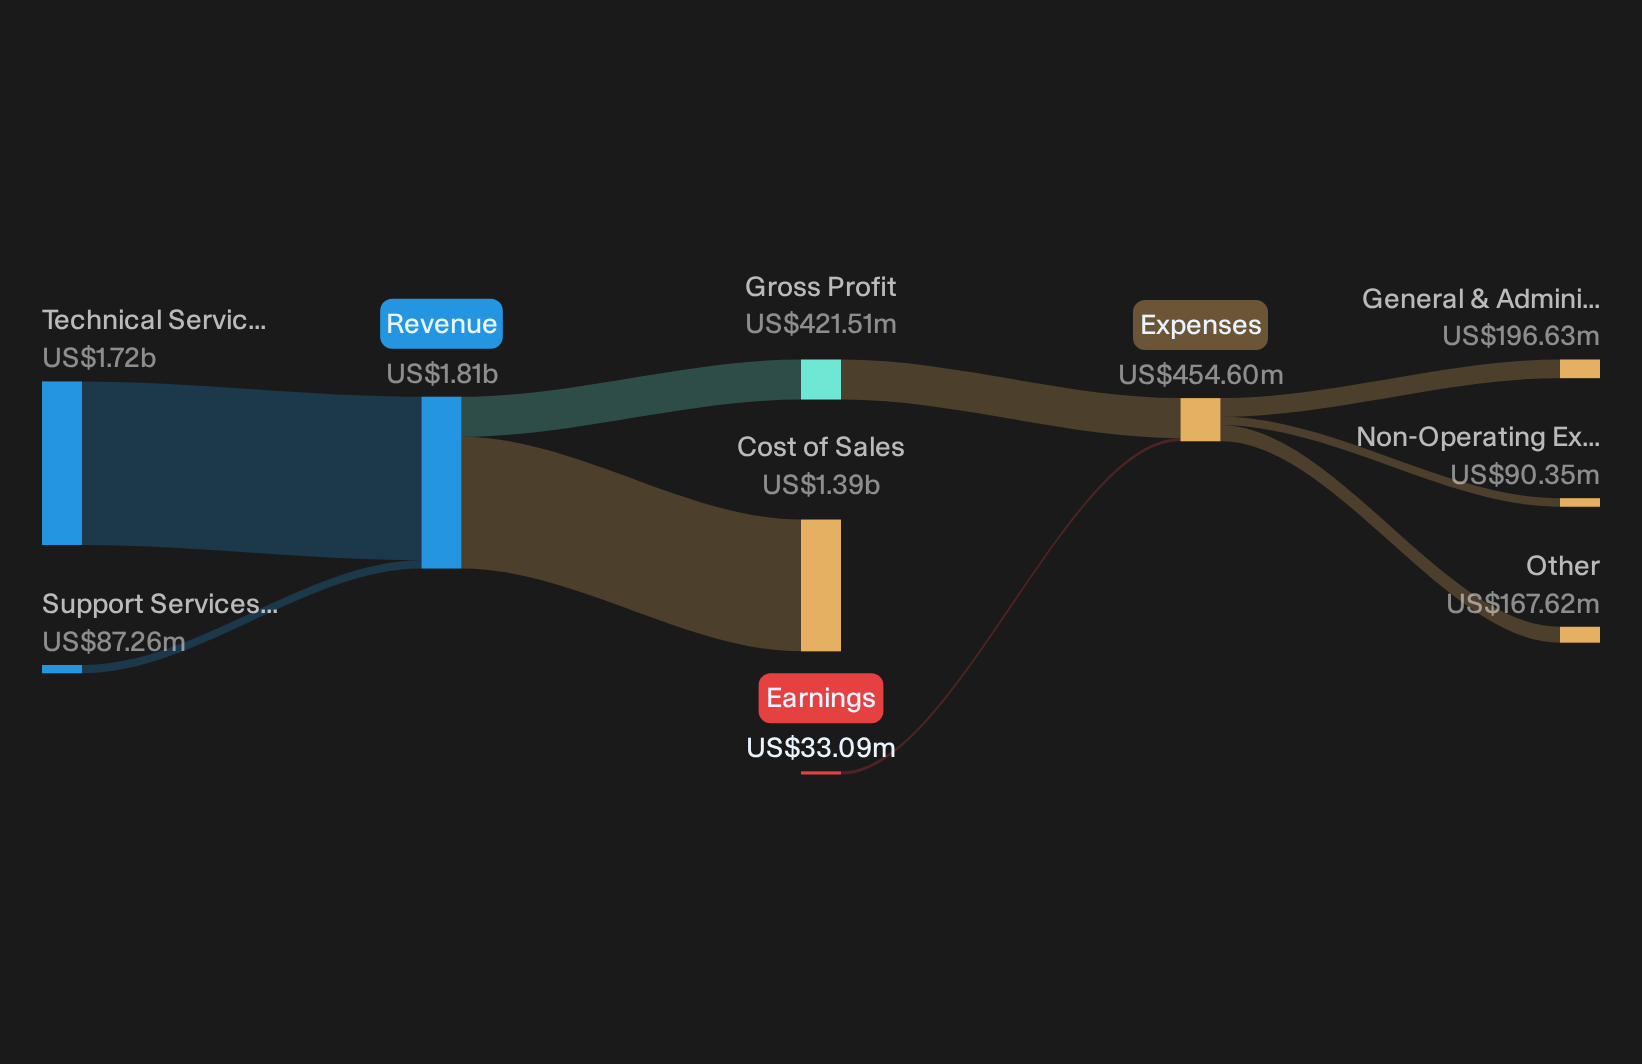
Operations: RPC generates about $1.72b from Technical Services and $87 million from Support Services, with around $1.78b earned in the United States.
Market Cap: $1.2b
RPC fits this higher fuel price theme as a geared play on drilling and completion activity. The analyst consensus Narrative on Simply Wall St argues that its shift toward higher tech services could change how that cycle flows through to earnings quality.
"Rapid adoption of higher tech downhole tools such as the MetalMax metal on metal power section, which early adopter districts are already using on more than half of their jobs and which has supported new depth records and entry into harsher applications, can continue to shift RPC’s revenue mix toward higher value work and support net margin resilience."
What happens to RPC’s margins if that one quiet change in mix gains traction just as fuel linked activity budgets reset higher?
If that margin reset is what you are watching, the full narrative for RPC shows how this shift could accelerate RPC’s earnings mix and where execution risk still lurks.
Seeking Fresh Alternatives Before They Fly
Markets move fast and the best breakout stories rarely stay under the radar for long. Spot fresh momentum plays before the crowd, while it matters, and get in early.
- Target resilient cash generators that can keep moving even when headlines turn choppy by running the list of solid balance sheet and fundamentals (23 results) and focusing on businesses built to stay standing.
- Hunt for cash flowing AI leaders that are not just burning runway capital by using the 42 profitable AI stocks that aren't just burning cash to narrow in on proven operators.
- Position for potential yield while prices are still dropping and sentiment is cautious by scanning the 6 dividend fortresses and zeroing in on income focused opportunities.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com