
3 Auto Stocks Tied To Eastern Europe’s Low Cost Manufacturing Shift
Mercedes-Benz hitting pause on fresh German plant investment has thrown a harsh spotlight on costs in Western Europe and quietly turned Eastern European production hubs into the new story to watch. Capacity and jobs do not vanish; they move, and that shift can reshape where value pools emerge. This article walks through three stocks exposed to that news and explains their role if more assembly work heads east.
The stocks covered next are just a first pass on the theme, and the full screen on Simply Wall St has surfaced 7 more Eastern European auto and parts companies with equally compelling stories that are not discussed here. To go straight to the source and identify, filter and analyze the highest conviction plays, head into the Eastern European low-cost auto manufacturing screener.
Schaeffler (XTRA:SHA0)
Overview: Schaeffler is a large German auto and industrial supplier that designs and manufactures powertrain, chassis and bearing systems across Europe and beyond.
Operations: Schaeffler generates most of its revenue from Powertrain & Chassis at €8.5b, Bearings & Industrial Solutions at €6.4b and E-Mobility at €5.2b.
Market Cap: €5.3b
Schaeffler sits right in the slipstream of Western carmakers rethinking where they source and assemble. This is why the bearish analyst Narrative on Simply Wall St pays so much attention to how its European footprint and cost program intersect with future profit potential.
"Although restructuring, footprint optimisation and capital discipline are already linked to higher gross margins in Powertrain & Chassis, Bearings & Industrial Solutions and Vehicle Lifetime Solutions, the decision to lower the 2028 revenue ambition while keeping margin targets intact raises the possibility that future EBIT delivery leans heavily on cost actions that are largely front loaded, which may leave limited additional cost levers to protect margins if volumes soften further."
For investors watching Schaeffler through this Eastern European manufacturing lens, a single unresolved pressure could decide how durable those margins really are.
That hinge point is exactly what the full narrative for Schaeffler unpacks, showing where cost cuts could stall and where a reworked footprint might quietly enhance the company’s ability to generate earnings.

PWO (XTRA:PWO)
Overview: PWO AG supplies metal components and systems for cars, focusing on cost efficient production in Germany, Czechia and Serbia for global automakers.
Operations: PWO AG generates about €504 million from auto parts and accessories, with revenue concentrated in Germany, Czech Republic, Mexico and Canada.
Market Cap: €64 million
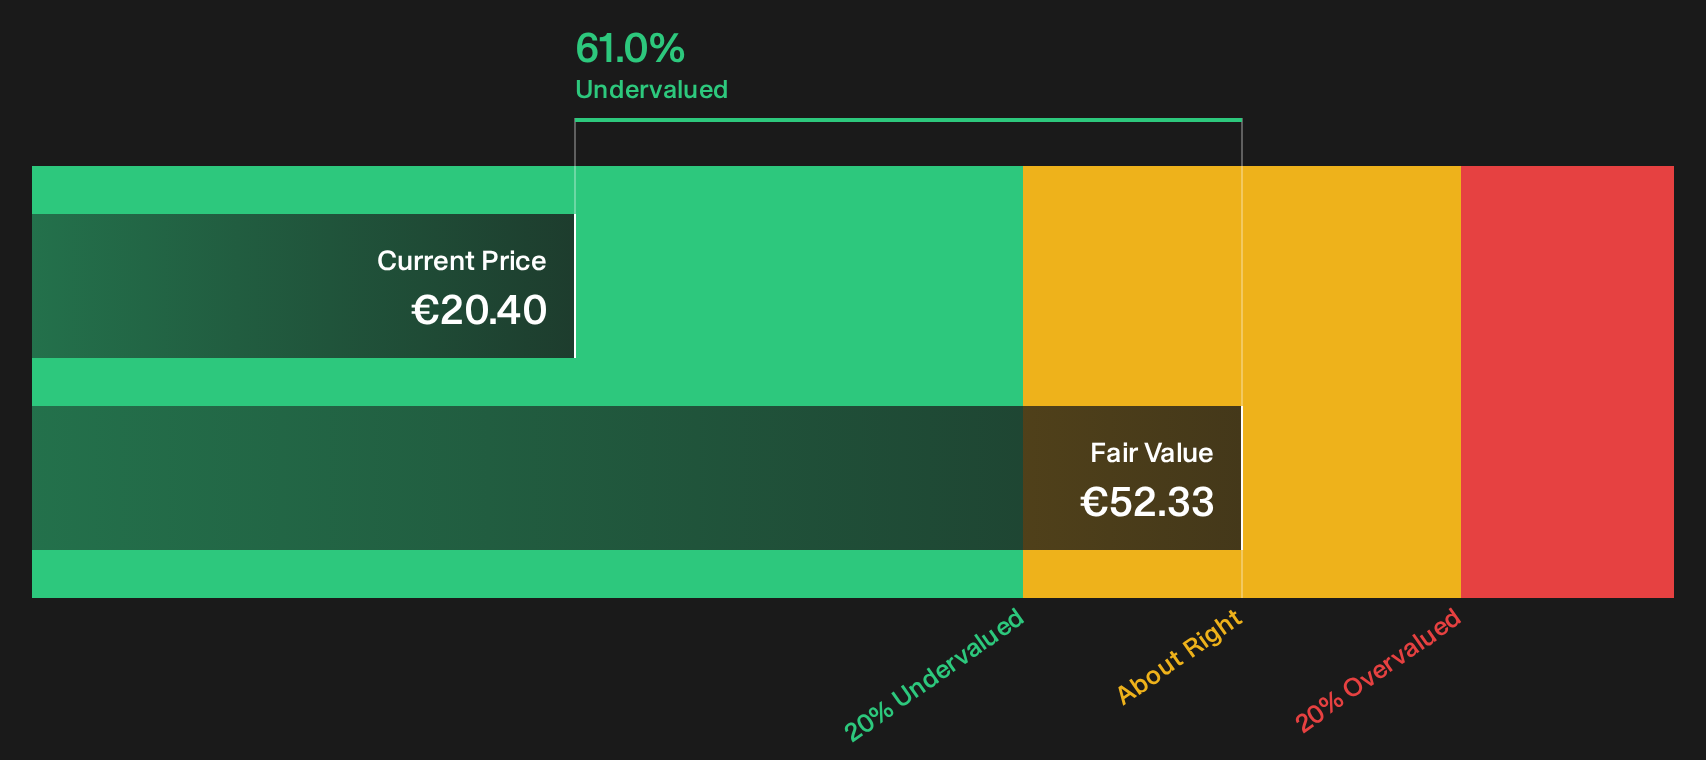
PWO ties directly into the Eastern European low cost auto manufacturing theme, with meaningful production in Czechia and Serbia feeding Western supply chains while Mercedes-Benz considers shifting capacity away from Germany. Earnings forecasts and a discount to estimated cash flow value are key considerations for investors, and future outcomes depend in part on how its thin margins interact with rising funding and interest costs.
Those thin margins put every euro of funding under the microscope, so it is worth scanning the 2 key rewards and 3 important warning signs (1 is major!) to see what the market might be missing.
ElringKlinger (XTRA:ZIL2)
Overview: ElringKlinger supplies European automakers with components, modules and systems for combustion and electric drivetrains, sealing, shielding and aftermarket engine repair, while also selling engineered plastics into other industries.
Operations: ElringKlinger generates about €1.27b from Original Equipment, €399 million from Aftermarket and €148 million from Engineered Plastics, with smaller Other and Consolidation items.
Market Cap: €402 million
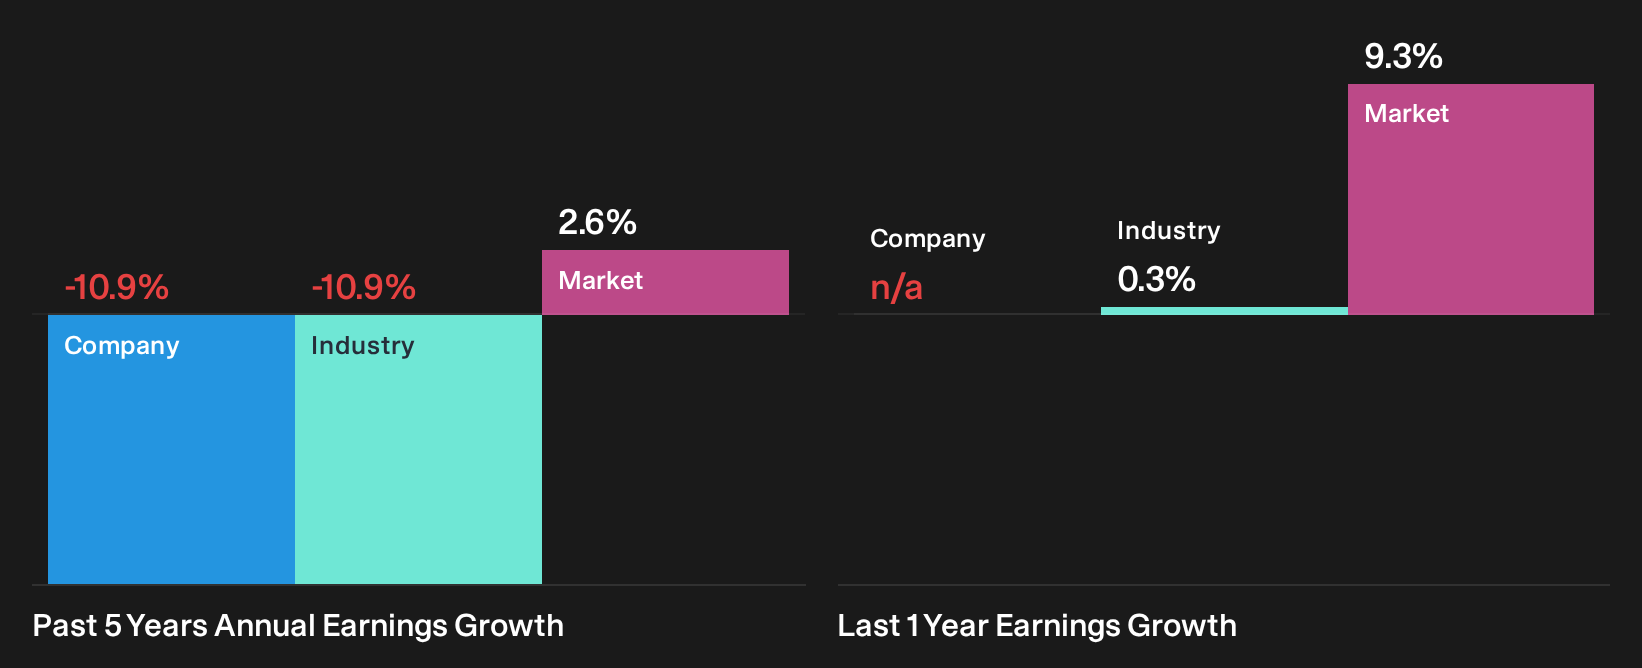
ElringKlinger matters for this Eastern European low cost auto manufacturing theme because it gives German based suppliers a way to lean on more flexible European production as carmakers such as Mercedes-Benz weigh shifting assembly east. The bearish analyst Narrative on Simply Wall St frames why that balance between new technology and cost control still sits on a knife edge.
"Although ElringKlinger’s E Mobility revenues are rising and management aims to expand this area further, the business area still reported an adjusted EBIT loss of €8.1 million in Q2 2026."
What happens to margins if one key cost saving push arrives slower than expected is what could really move this story.
If that cost saving push stalls or accelerates, the full narrative for ElringKlinger shows how ElringKlinger’s transition story could decouple from headline E Mobility losses.
Seeking Fresh Alternatives Before They Fly
Fresh opportunities rarely stay quiet for long. Breakout stories gain momentum, staying under the radar for now, then get caught once the crowd arrives. Scan these ideas while it matters and get in early.
- Target resilient compounding potential by reviewing a curated 205 resilient stocks with low risk scores that aims to hold up when volatility picks up and capital gets more selective.
- Hunt for strong cash engines with the 190 high quality undervalued stocks that blend healthy balance sheets with compressed expectations before momentum traders notice the gap.
- Ride long term infrastructure themes through the 44 power grid technology and infrastructure stocks featuring businesses tied to grid upgrades, electrification trends and capital projects that can reshape cash flows over time.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com