
Nebius Stock Crashed Nearly 25% After Earnings. How to Play NBIS Now.
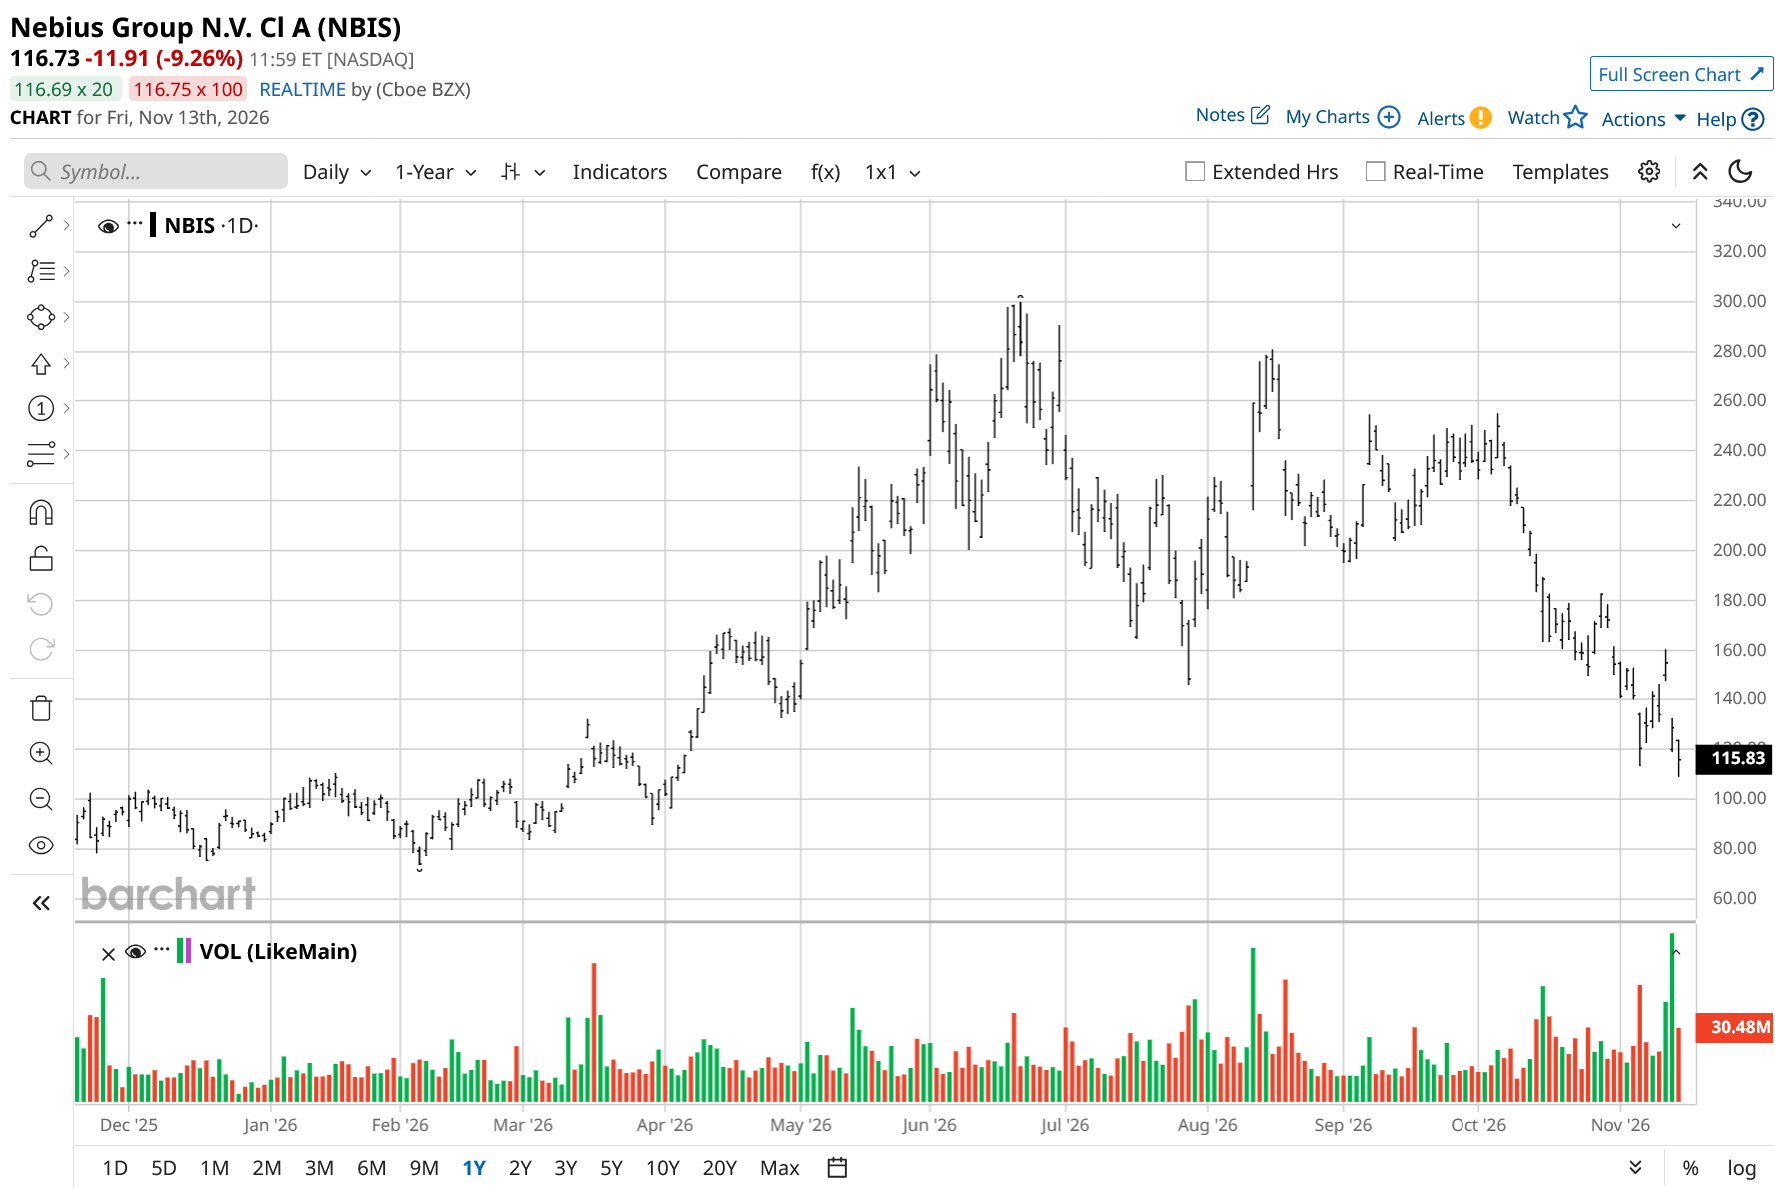
Nebius Group (NBIS) experienced another severe selloff after releasing third-quarter earnings on Nov. 12. The stock price fell 16.84% to $128.64 despite recording a 571% year-over-year (YoY) increase in revenue and beating analysts' forecasts. At its lowest price of $118.81, the stock had dropped more than 23% from its closing price the previous day. During a rough morning trading session today, NBIS stock hit a new six-month low at $109.14.
To the disapointment of investors, the earnings beat failed to overcome the negative impact on expectations of delayed capacity deployments, low near-term revenues, and the much larger investment plan. This comes amid growing investor concerns over how AI infrastructure companies can finance their expansion without overleveraging or diluting shareholders. On the other hand, the disclosure of improving customer economics and an ambitious revenue outlook for 2027 makes the selloff interesting for those willing to invest in a longer time frame.
About Nebius Stock
Founded in Amsterdam, the Netherlands, Nebius is a vertically integrated business specializing in AI cloud infrastructure and offering GPU computing capacity, data centers, cloud software, and managed AI services. The firm collaborates with clients ranging from AI startups to major corporations and hyperscalers like Microsoft (MSFT) and Meta Platforms (META). Its market capitalization is estimated at $39.1 billion.
Despite the recent pullback, the shares of the firm have advanced 39% this year, outperforming a 10% gain of the S&P 500 Index ($SPX). However, the stock price has decreased 61% from its 52-week high of $299.86.
Valuation has changed significantly as well. Given the market capitalization of $39.1 billion and management's updated revenue outlook for 2026 of around $3 billion, Nebius stock trades at 13 times estimated annual revenue. Using the midpoint of management's preliminary $12 billion to $13 billion 2027 revenue guidance, the multiple falls to 3.1 times forward sales.
Therefore, Nebius looks increasingly attractive relative to its future growth prospects. However, this valuation highly depends on management delivering its ambitious expansion plans. The current profitability also makes the P/E multiple irrelevant.
Beats Q3 Earnings Estimates, but Guidance Disappoints
Nebius generated $980.8 million of revenue in the third quarter, which exceeded consensus estimates by around $73.6 million. Moreover, it reported $0.38 of EPS, which was $1.01 higher than estimates. On the other side, though, the company recorded the GAAP net loss from continuing operations of $37.5 million, while the adjusted net income was $90.9 million. It shows the significance of understanding different earnings metrics.
More importantly, the adjusted EBITDA amounted to $465.8 million, up from the loss of $5.2 million in the same period of the previous year. The AI cloud business of the company showed an impressive 53.2% adjusted EBITDA margin. However, $325 million of the Q3 revenue is related to the non-recurring business of the firm, which is asset-light. Leaving this figure out gives us approximately $655.8 million of revenue.
The biggest disappointment came from the guidance. The management now expects 2026 revenue to be closer to the lower end of its previous $3 billion to $3.4 billion outlook range, while the capital expenditures are seen at approximately $27 billion compared with the earlier $20 billion to $25 billion estimate. Moreover, the company's plan to exceed the $7 billion mark in annualized revenue has been shifted from December 2026 to February 2027.
The problem here is in delayed capacity deployments at third-party facilities, especially in New Jersey, which supports Microsoft. According to the firm's plans, more than half of the contracted New Jersey capacity is expected to be delivered by the year-end, while the remainder will be delivered in the second quarter of 2027. Yet, the contracts remain intact, which means that the matter is related to implementation and timing.
That said, several factors improve the long-term investment case of Nebius. First, the firm announced signing more than $12 billion in contract value since the start of Q3, while prepayments on the agreements concluded in the third quarter fully covered capital expenditure. Payback periods also improved to 19 months from 22 months in the previous quarter. These factors mean that Nebius can secure better contractual conditions as demand for AI capacity grows.
Management expects 2027 revenue of $12 billion to $13 billion and sees itself at the pre-tax breakeven in the fourth quarter. However, the planned $40 billion to $45 billion capital expenditures program will represent a significant financial commitment. Even though the management expects 75% to 85% of the expenses to be covered with customer prepayments and asset-backed financing, the remaining amount may put the strain on the firm's balance sheet and may lead to further shareholder dilution.
What Do Analysts Expect for NBIS Stock?
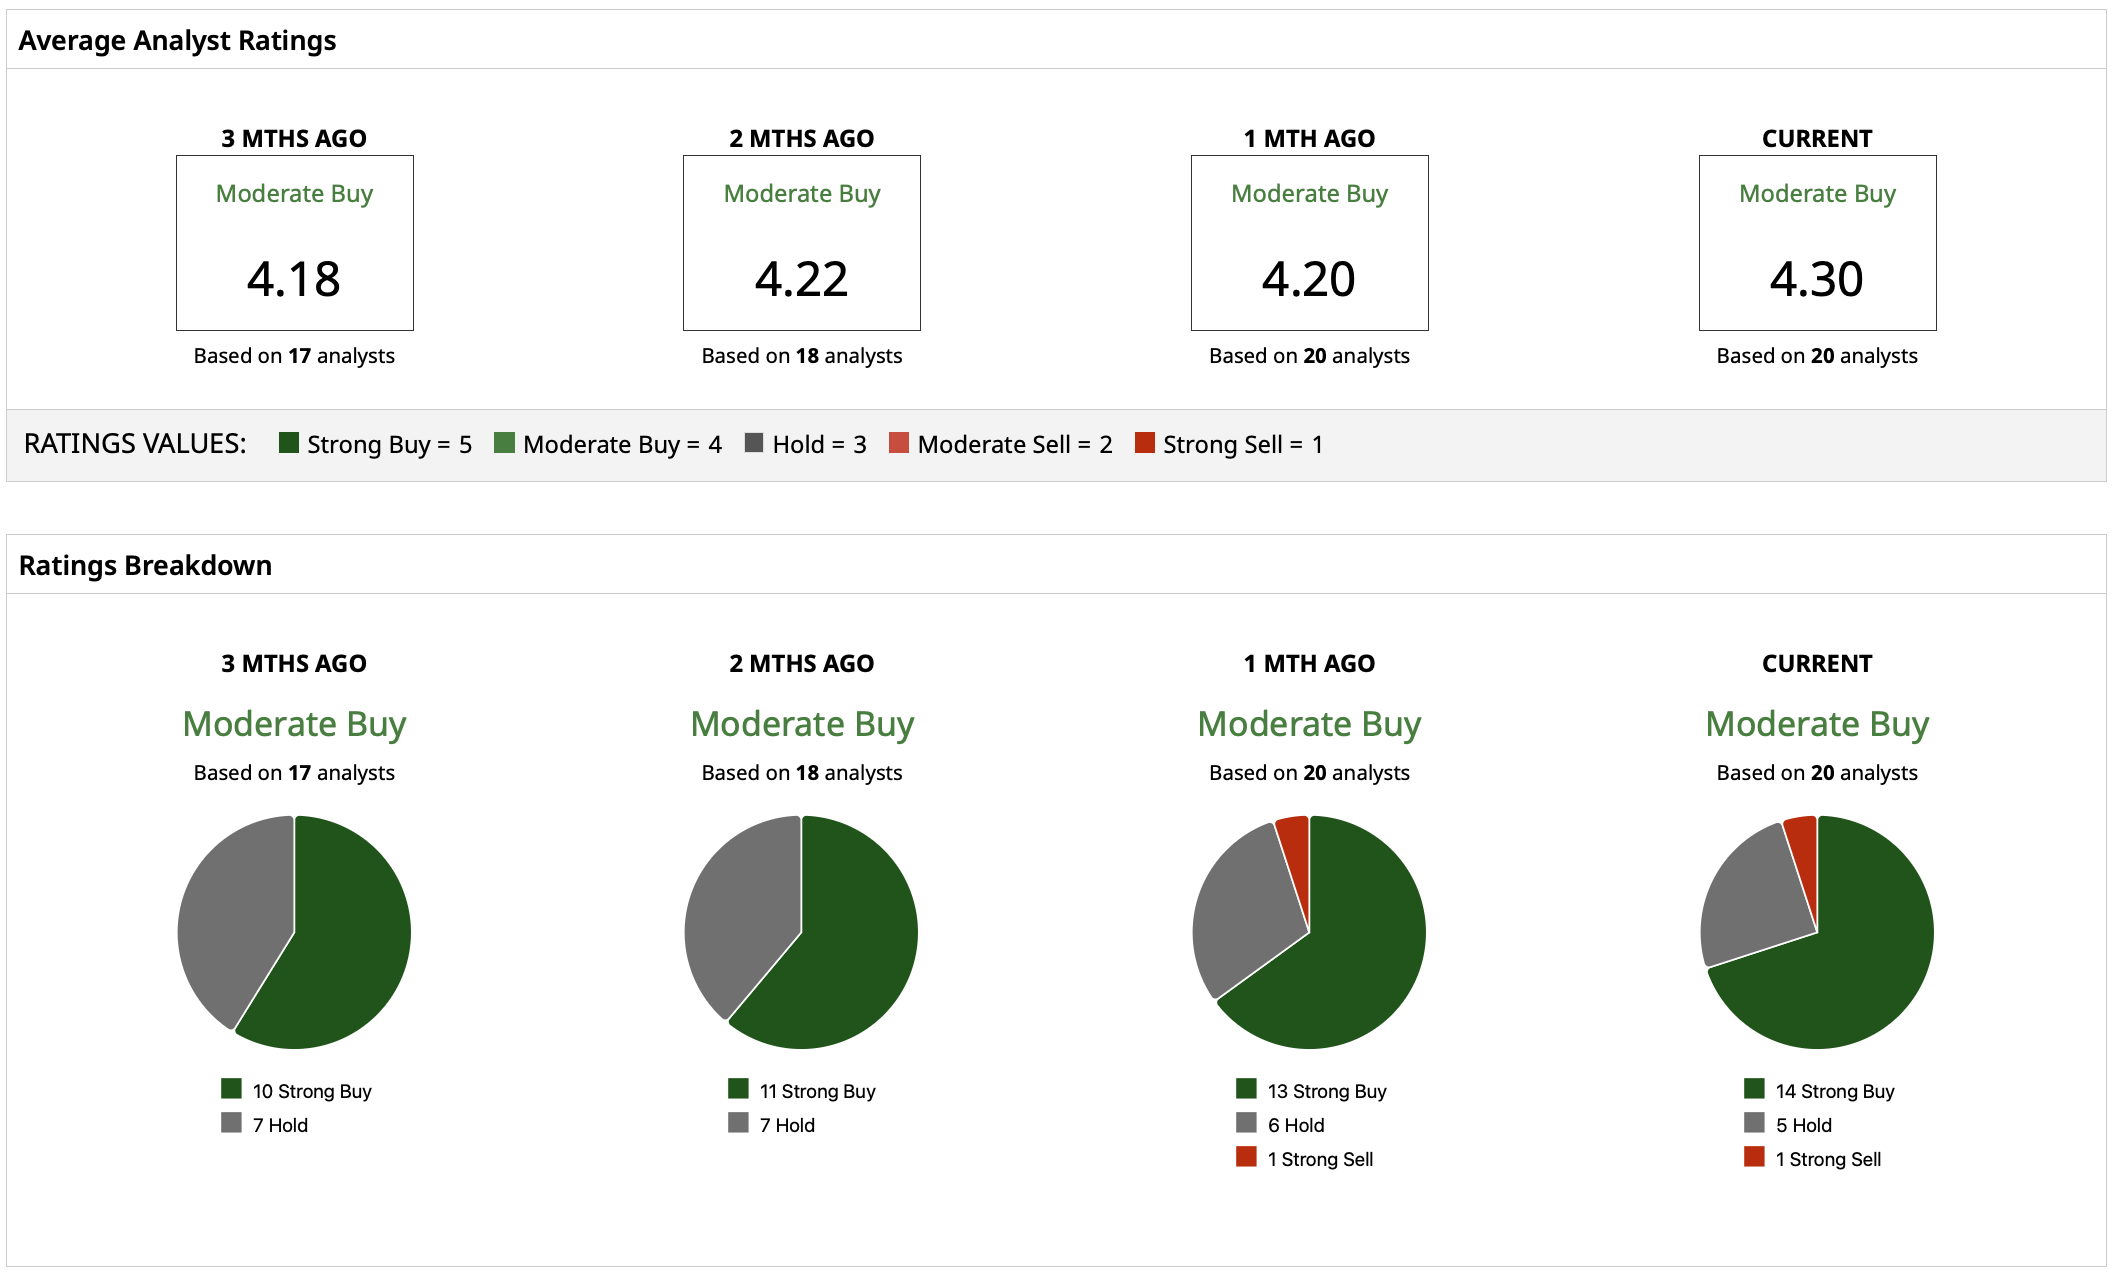
Investor sentiment towards Nebius is still positive despite the recent correction. There is a “Moderate Buy” consensus rating among 20 analysts, with 14 rating NBIS stock as a “Strong Buy,” five analysts giving it a “Hold,” and one analyst a “Strong Sell.” However, the reductions in price targets have become a frequent occurrence amid reappraisal of the financial needs of the AI infrastructure growth. For example, Robert W. Baird cut its price target from $340 to $200 after the earnings announcement and maintained the “Buy” rating. Before, Citigroup decreased its target from $324 to $265 and maintained its “Buy” rating.
On the date of publication, Yiannis Zourmpanos had a position in: NBIS . All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.