
HF Sinclair (DINO) Could Be 16% Below Fair Value As Fuel Quality Push Gains Attention
HF Sinclair (DINO) has put product development in the spotlight with Sinclair fuel featuring DINOCARE TOP TIER+ approved gasoline, a move that ties fuel quality, engine cleanliness and brand trust directly to its investment story.
Recent trading tells a story of cooling momentum after a strong run. HF Sinclair’s share price has a 1-week return of 5.11% and a 90-day share price return of 9.05%, yet the 30-day share price return is down 20.00%. Even so, the year-to-date share price return sits at 118.04% and the 1-year total shareholder return is 88.80%. The 5-year total shareholder return of 290.78% suggests that long-term holders have already captured substantial gains.
Scan how HF Sinclair’s fuel push compares with other energy players that screen well on balance sheet strength and fundamentals through our curated list of solid balance sheet and fundamentals (23 results).HF Sinclair now trades below both analyst targets and an in house fair value estimate after that sharp 30 day pullback. Is this caution about refining and renewables risk justified, or is it overdone ahead of a valuation check?
Most Popular Narrative: 16% Undervalued
HF Sinclair’s last close of $102.15 sits below the analyst consensus Narrative fair value of $122, which the analyst consensus Narrative on Simply Wall St bases on detailed revenue, earnings, and valuation assumptions using a 7.24% discount rate.
The main factor that has to go right is continued execution on the Go West logistics build-out, the Lubricants & Specialties spin-off, and renewable diesel utilization so the company can turn current refining strength into durable, lower capital intensity cash flows, even as regulatory and leadership risks remain.
The numbers and current share price imply that HF Sinclair is fairly valued, with investors already treating today’s elevated refining cycle, strong cash returns, and earnings as largely reflected in the stock, which leaves more room for disappointment than for additional re-rating.
See why 30 investors see HF Sinclair as 16% undervalued.
Result: Fair Value of $122 (UNDERVALUED)
Still, the HF Sinclair narrative could be knocked off course if electric vehicle adoption erodes fuel demand faster than expected or if RIN costs spike and squeeze refining economics.
Find out about the key risks to this HF Sinclair narrative.
Another View: HF Sinclair Through Cash Flows
The narrative crowd leans toward HF Sinclair being undervalued at a fair value of $122, yet the SWS DCF model tells a cooler story. On that cash flow view, DINO at $102.15 trades above an estimated value of $89.17, which flags less of a margin of safety than the multiple based fair value suggests. Which lens do you trust more when the two start to disagree?
For investors who want to see exactly how the cash flows are treated over time, Look into how the SWS DCF model arrives at its fair value..
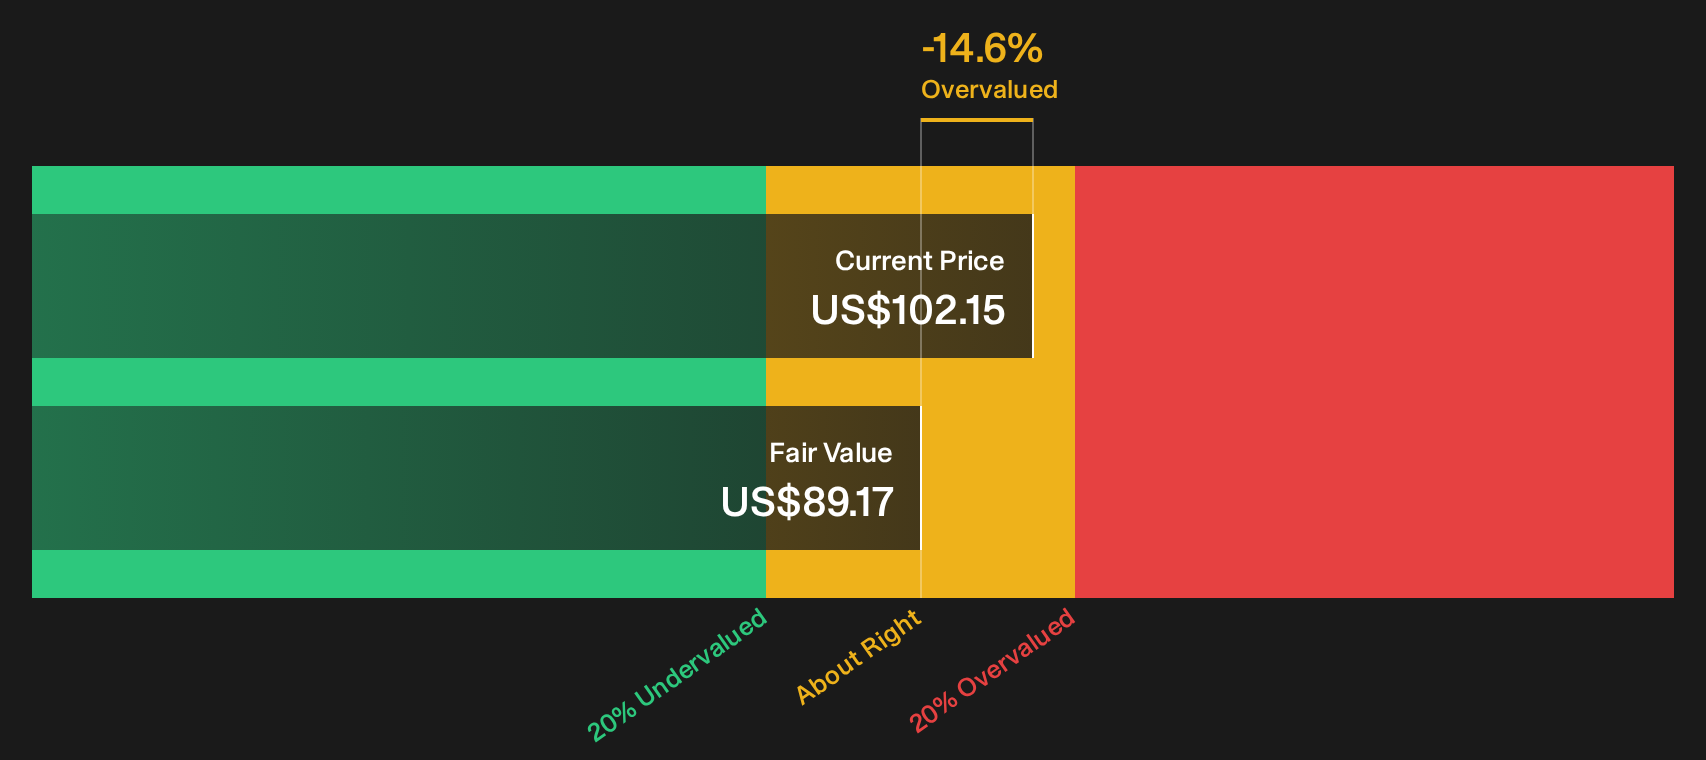
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out HF Sinclair for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Conflicted by HF Sinclair’s mixed signals on value and risk? Act while the data is fresh and weigh both sides through 3 key rewards and 2 important warning signs.
Looking for more HF Sinclair sized opportunities?
If HF Sinclair has sharpened your focus on pricing power and balance sheet strength, do not stop here. Broaden your watchlist with a few targeted stock idea lists that could surface your next high conviction position.
- Target resilient potential by reviewing companies that pass strict financial health checks through the 29 resilient stocks with low risk scores.
- Hunt for mispriced quality by scanning the 32 high quality undervalued stocks and see which businesses combine solid fundamentals with room for a re rating.
- Get ahead of the crowd by searching the 20 high quality undiscovered gems before attention and capital rush in.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com