
Occidental Petroleum Generates Strong FCF - Is OXY Stock Too Cheap?
Occidental Petroleum (OXY) reported very strong Q3 operating cash flow (OCF) and free cash flow (FCF) on Nov. 9. That was based on higher oil and gas prices. But revenue could drop next year, as analysts expect energy prices to fall. Nevertheless, OXY stock could still be undervalued, as this article will show, based on its strong cash flow margins.
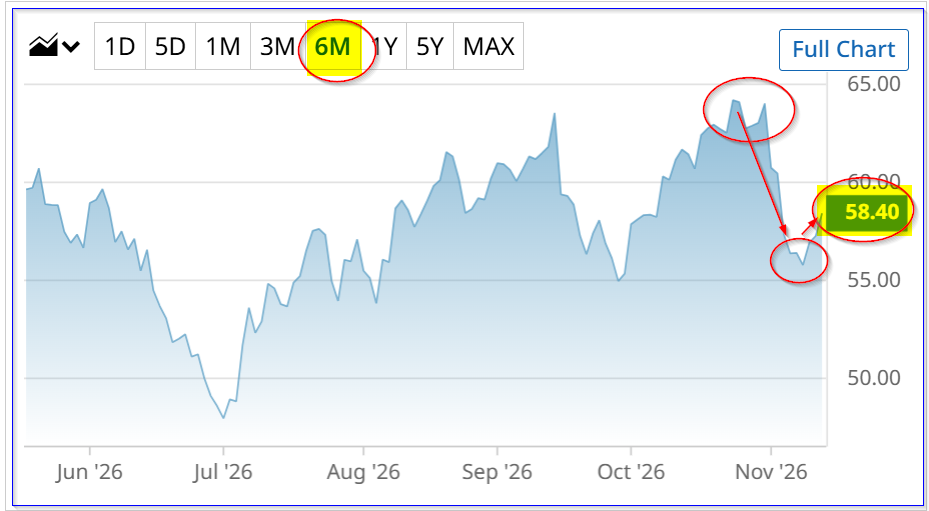
OXY is trading at $58.74 at midday on Nov. 12. That's up from a pre-market trough of $55.76 on Nov. 9, but well below its 6-month peak of $64.17 on Oct. 23. However, recent results suggest significant upside.
Strong Cash Flow Results
Occidental Petroleum reported that its Q3 free cash flow (FCF) rose 88% YoY to $2.779 billion, but was down 8% from Q2 ($3.021 billion). In addition, FCF was down 7% YTD, as can be calculated from the Schedule 1 table on page 5 of the earnings release.
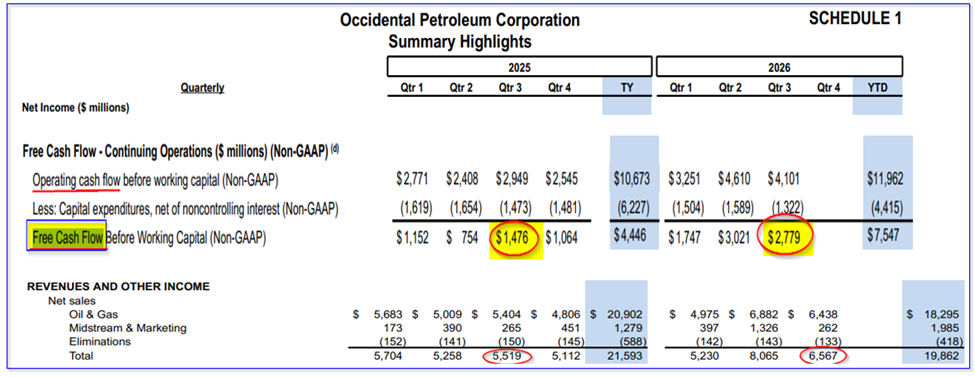
Nevertheless, its operating cash flow (OCF) margins were high. But management has said capex could drop next year. This could result in a higher FCF forecast.
Forecasting OXY's FCF
Here's why. First, the table below shows that its operating cash flow (OCF) margins, which are before capex, shows higher OCF margins.
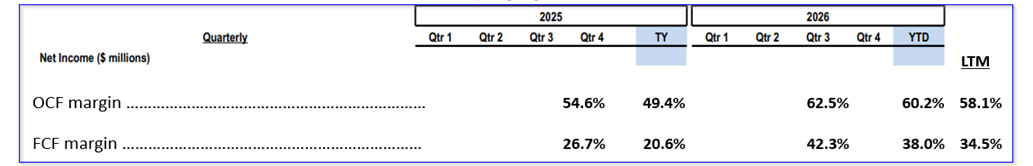
For example, in Q3, operating cash flow represented 62.5% of revenue (taken from the data in Schedule 1), vs. 54.6% last year. Over the past year, its LTM (last 12 months) OCF margin is 58.1% vs. 49.4% in 2025.
Next, if its capex stays flat over the next year (i.e., $4.4b +1.5b = $5.9b) and its operating margin averages 58%, we can forecast OXY's 2027 FCF using analysts' revenue forecasts.
For example, Seeking Alpha reports that 11 analysts are projecting $26.8 billion in 2027 revenue (down 4.5% from $28.05 billion forecast for 2026):
$26.8b x 0.58 = $15.54 billion OCF
$15.54b OCF - $5.9b capex = $9.64 billion FCF est.
That's almost 150% higher than the $3.843 billion in LTM FCF over the past 12 months, and also represents a 36% FCF margin in 2027.
Just to be conservative, on a worst-case basis, let's assume the OCF margin is only 55% and capex rises to $10 billion:
$26.8b x 0.55 = $14.74b OCF
$14.74b OCF - $10.0b capex = $4.74b FCF
That is still 23.3% higher than its LTM FCF of $3.843b. In other words, FCF could range between $4.74b and $ 9.64b, or $7.19 billion. That's 88% higher than the LTM figure.
The bottom line is that Occidental Petroleum's forecasted FCF next year could push OXY stock's valuation significantly higher.
Higher OXY Price Targets
Right now, OXY has a market cap of $54.3 billion, according to Yahoo! Finance. Over the last year, the stock price is up about 39%. So, that implies its average market value has been $46.68 billion.
Since OXY's LTM FCF has been $3.843 billion (taken from Schedule 1 shown above), that means the market has given OXY an 8.23% FCF yield:
$3.843b / $46.68 billion avg mkt cap = 0.0823 = 8.23% FCF yield
That means for next year, using the $7.19b avg FCF estimate, we can use this to project its valuation:
$7.19b / 0.0823 = $87.36 billion fair market value (FMV)
That is 60.8% above today's market cap.
But, just to be conservative, let's use a 10% FCF yield (i.e., 10x FCF):
$7.19b FCF x 10 = $71.9b FMV, or 32.4% higher
Therefore, the price target (PT) is 32% above today's price:
$58.74 x 1.324 = $77.77 PT
That coincides with what other analysts are projecting. For example, Yahoo! Finance says OXY's average PT from 28 analysts is $70.00, or 19% higher. Barchart's mean survey PT is $69.78, and AnaChart's PT is $67.15, from 19 analysts.
Summary and Conclusion
The bottom line is that Occidental Petroleum looks undervalued. That is based on its operating cash flow forecasts and analysts' revenue forecasts, as well as management's lower capex guidance.
Investors might like to buy in-the-money (ITM) long-dated calls or short out-of-the-money (OTM) near-term puts to leverage a position in OXY. I expect to write about these plays in the next week.
On the date of publication, Mark R. Hake, CFA did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.