
Is Bridgestone (TSE:5108) Undervalued As Its 2026 Outlook Resets Expectations?
Bridgestone (TSE:5108) has put fresh numbers on the table, issuing earnings guidance for 2026 that pegs revenue at ¥4,700,000 million and profit attributable to shareholders at ¥340,000 million.
Bridgestone’s guidance landed after a Q3 2026 earnings call and comes with the share price at ¥4,319, supported by a 30-day share price return of 9.29% and a year-to-date share price gain of 22.35%, while the 5-year total shareholder return of 110.50% points to longer term momentum that investors are still weighing against today’s valuation signals.
Spot 18 high quality undervalued stocks that, like Bridgestone after this guidance update, pair established business models with valuations that some investors may see as leaving room for a re-rating.For Bridgestone, the latest share price climb can look like a simple mood swing, or a clearer acknowledgment of the earnings power management has just outlined. Which story does the current valuation really tell?
Most Popular Narrative: 7% Overvalued
Bridgestone’s last close at ¥4,319 sits above the analyst consensus Narrative fair value of ¥4,020. In the analyst consensus Narrative on Simply Wall St, which uses a 6.83% discount rate, this frames today’s price as richer than its modeled cash flows.
The current valuation suggests the share price already reflects a fairly valued, bullish view that Bridgestone can sustain around 11% adjusted operating margins, expand higher margin premium and solutions businesses, and continue increasing shareholder returns through buybacks and dividends.
See why 4 investors see Bridgestone as 7% overvalued.
Result: Fair Value of ¥4,020 (OVERVALUED)
Still, U.S. tariffs that already cut into profit and a Latin American arm hovering near break even leave Bridgestone’s margin story exposed if those pressures deepen.
Find out about the key risks to this Bridgestone narrative.
Another View: Cash Flows Tell A Different Bridgestone Story
A separate lens comes from the Simply Wall St DCF model, which estimates that Bridgestone’s future cash flows imply a value of ¥5,695 per share. That is well above the current ¥4,319 price, presenting the stock as undervalued rather than 7% rich. Which signal do you trust more: cash flows or the analyst narrative?
For a closer look at how those projected cash flows and discount rate feed into that figure, Look into how the SWS DCF model arrives at its fair value.
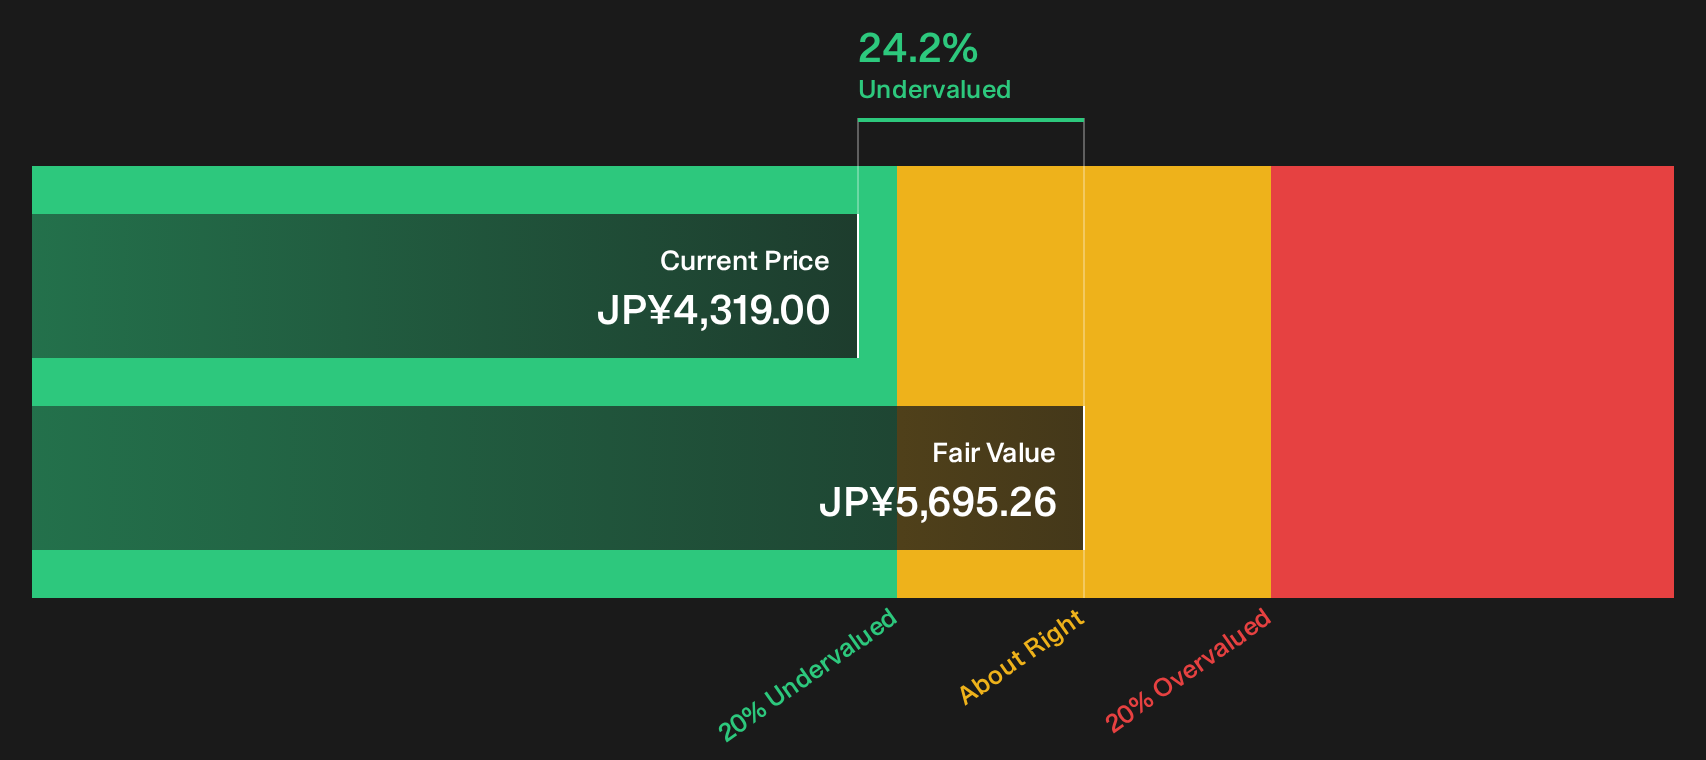
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Bridgestone for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 18 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Bridgestone’s value story can create both curiosity and urgency. Take a moment to look through the data and decide where you stand based on 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Bridgestone?
If Bridgestone has sharpened your focus on valuation and quality, broaden your watchlist now with other opportunities that could complement or challenge your current convictions.
- Target potential mispricings by scanning a curated 18 high quality undervalued stocks that combine robust business profiles with valuations some investors might view as appealing.
- Strengthen your search for resilience by reviewing a 20 resilient stocks with low risk scores that could help you balance out bolder positions in your portfolio.
- Get ahead of the crowd by tracking a 74 high quality undiscovered gems that pair strong fundamentals with lower market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com