
Duolingo (DUOL) AI Cost Cuts Put Its Valuation Back In Focus
Duolingo (DUOL) stock is back in focus after CEO Luis von Ahn said at Yahoo Finance’s Invest 2026 conference that switching to open-weight AI models cut certain training costs by roughly thirty times.
That AI shift comes after a bumpy stretch for Duolingo’s shares, with the price up 12.36% over the past month and 18.51% over 90 days, yet still down 10.80% year to date and delivering a 1-year total shareholder return decline of 15.61%, as investors weigh cost efficiencies, fresh revenue guidance for 2026, and ongoing securities class action headlines.
Spot emerging AI-driven education stories alongside Duolingo by scanning our hand-picked 41 profitable AI stocks that aren't just burning cash that pair real earnings with technology at the center of their products.Duolingo now trades slightly above the average analyst target, while screens still flag a hefty intrinsic discount. After the recent rebound, is the market being too cautious about AI and lawsuits, or not cautious enough?
Most Popular Narrative: 10% Overvalued
On the Simply Wall St analyst consensus Narrative, Duolingo screens as modestly overvalued, with a fair value of about $142.85 against the recent $157.42 close, built on detailed revenue and earnings forecasts discounted at 7.24%.
The numbers and current valuation imply that Duolingo is fairly valued with a bearish skew, with recent stock price weakness already reflecting concerns about slower bookings growth, lower gross margin guidance and the costs of its AI and subject expansion.
See why 177 investors see Duolingo as 10% overvalued.
Result: Fair Value of $142.85 (OVERVALUED)
Still, the narrative can break if daily active user gains fail to convert into subscribers or if China related AI rules keep delaying higher margin products.
Find out about the key risks to this Duolingo narrative.
Another View: Our DCF Model Sees Deep Value In Duolingo
While the Simply Wall St Narrative tags Duolingo as about 10% overvalued on a fair value of $142.85, the SWS DCF model points the other way. On future cash flows it marks fair value at roughly $296.21, which is about 47% above the current $157.42 share price. That kind of gap raises a blunt question: Is the market leaning too hard on today’s P/E and recent margin compression, or is the cash flow model overestimating how much of Duolingo’s AI and user base can ultimately be monetized?
For a closer look at how those assumptions come together in practice, and what would need to change for that gap to widen or narrow, Look into how the SWS DCF model arrives at its fair value.
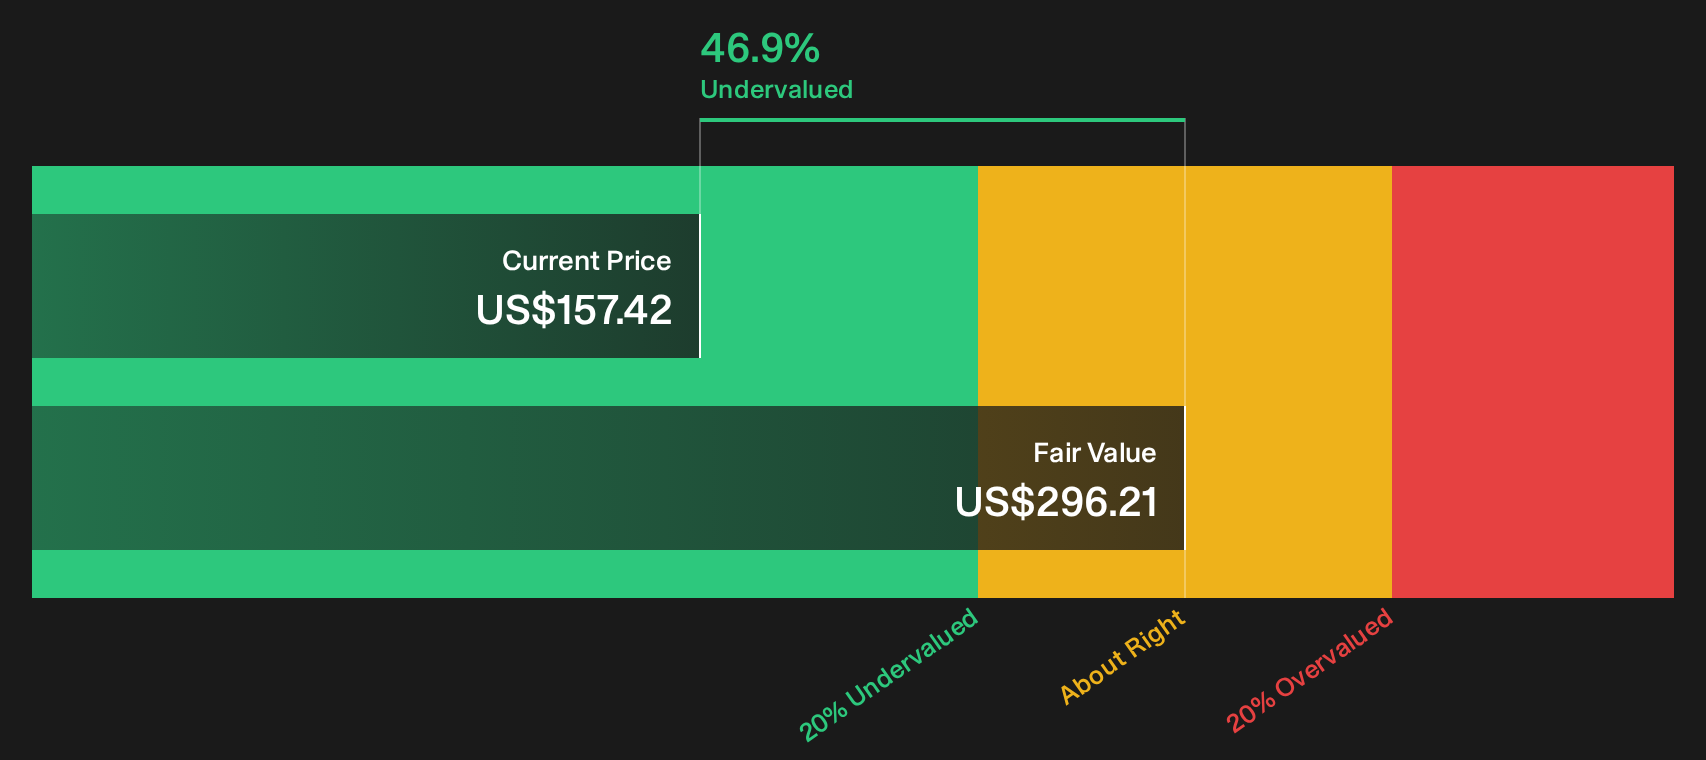
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Duolingo for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If this mix of optimism and concern around Duolingo feels familiar, move quickly and evaluate it carefully against the 2 key rewards and 3 important warning signs.
Looking for more ideas beyond Duolingo?
Broaden your watchlist now with a few focused screeners that surface clear, data backed stock ideas so you are not relying on Duolingo alone.
- Target quality at a discount by scanning our 32 high quality undervalued stocks that combine strong business fundamentals with prices below their assessed worth.
- Prioritize resilience by checking the 29 resilient stocks with low risk scores that score well on balance sheet strength and business stability.
- Hunt for potential future leaders early through the 20 high quality undiscovered gems before they attract wider market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com