
Can Allianz (XTRA:ALV) Justify Its Valuation On Raised Full Year Guidance?
Allianz (XTRA:ALV) is back in focus after third quarter earnings topped expectations, record asset management profit offset natural catastrophe costs, and management lifted the upper end of full year operating profit guidance to about €18.6b.
The raised guidance and record asset management contribution arrive against a strong backdrop for Allianz. The share price has climbed 11.55% over the past month and 21.85% year to date, while the 1 year total shareholder return of 35.96% and 5 year total shareholder return of 194.40% point to momentum that long term holders have already felt.
Scan beyond Allianz and see how other insurers and financial heavyweights with strong balance sheets and cash flows stack up in our hand picked list of solid balance sheet and fundamentals (199 results).
After a run like this and a market price near €472, while some analyst targets sit lower and intrinsic value models land higher, where does a fair tag for Allianz really fall in that spread?
Most Popular Narrative: 6% Overvalued
Allianz last closed at €472.40, while the analyst consensus Narrative on Simply Wall St points to a fair value of €447.27 using a 5.41% discount rate, which places the current price modestly above that estimate.
The build out of an integrated retirement and wealth platform, including the acquisition of HSBC Life Singapore with a 15 year bancassurance agreement and the purchase of UOB Asset Management with distribution across eight Asian markets, is expected to deepen Allianz’s access to Asian savings pools and support future fee and premium revenue growth.
See why 277 investors see Allianz as 6% overvalued.
Result: Fair Value of €447.27 (OVERVALUED)
Still, the Allianz story can change quickly if foreign exchange swings persist or large commercial claims continue to push up buffers and eat into profitability.
Find out about the key risks to this Allianz narrative.
Another View: Allianz Through The P/E Lens
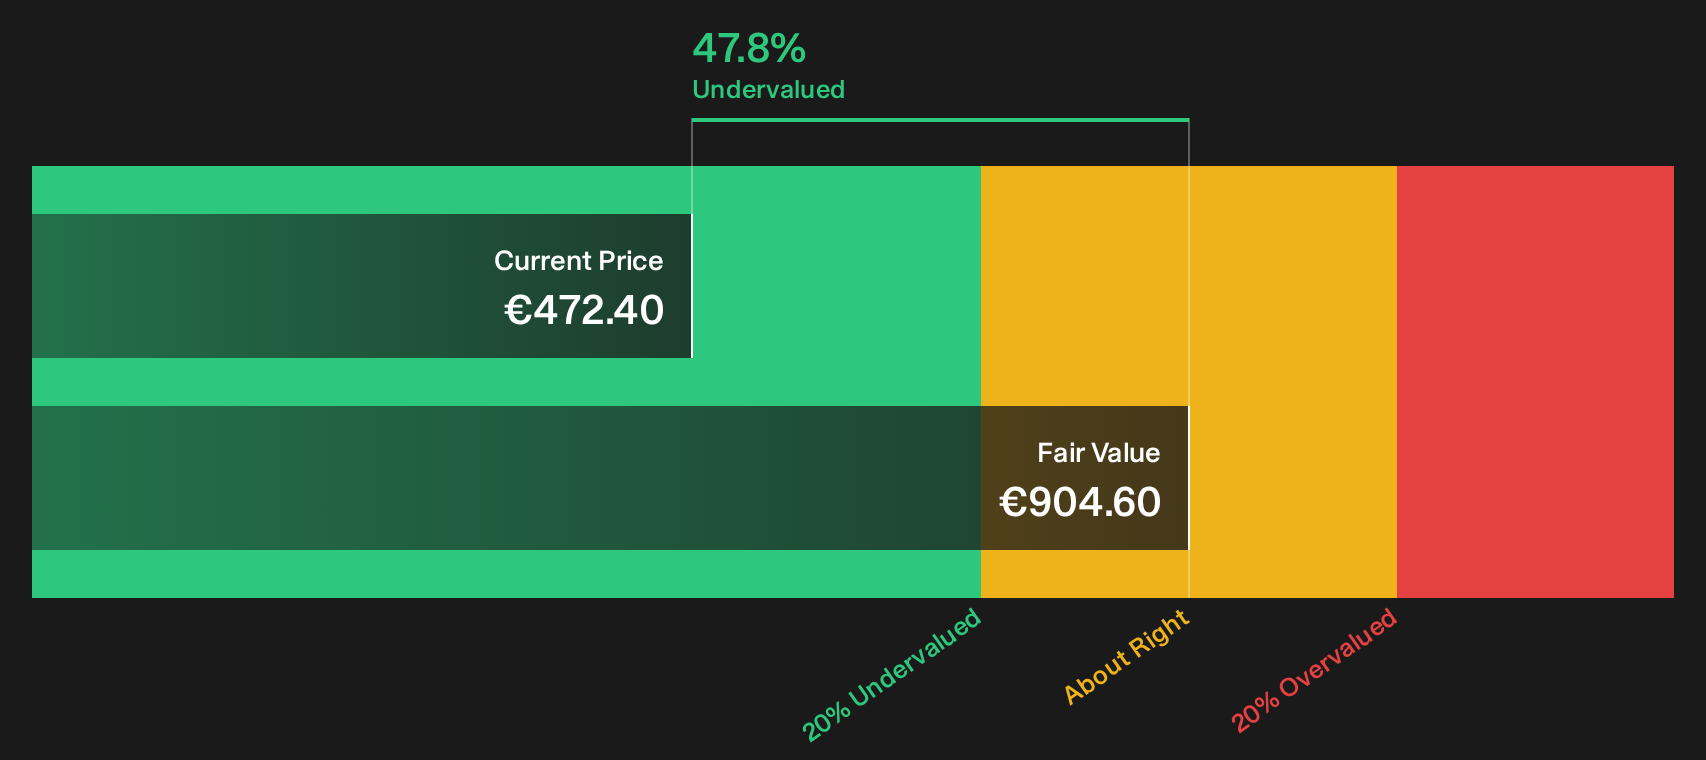
The SWS DCF model presents Allianz as trading well below an estimated future cash flow value of €904.60, which differs from the analyst narrative that places fair value at €447.27 and describes the stock as overvalued at around €472.40. With that gap between cash flow assumptions and earnings-based pricing, which story do you consider more compelling right now?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Feeling torn between the mixed fair value signals around Allianz and the strong recent share performance is normal. Act while the numbers are fresh in your mind, and pressure test the optimism in the data by taking a closer look at the 4 key rewards.
Looking For More Investment Ideas Beyond Allianz?
If Allianz has sharpened your appetite for quality, cast the net wider and let fresh ideas surface through a focused screen of potential opportunities.
- Target resilient compounding potential by reviewing companies that score as 207 resilient stocks with low risk scores and could help anchor the more volatile parts of your portfolio.
- Hunt for quality at a sensible entry point by scanning 193 high quality undervalued stocks that pair solid financials with pricing that still leaves room for upside.
- Build a cash flow stream you can track with confidence by zeroing in on 218 dividend fortresses that combine higher yields with robust fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com