
Why Navitas Stock Is In Focus After Patent Lawsuit And Revenue Guidance
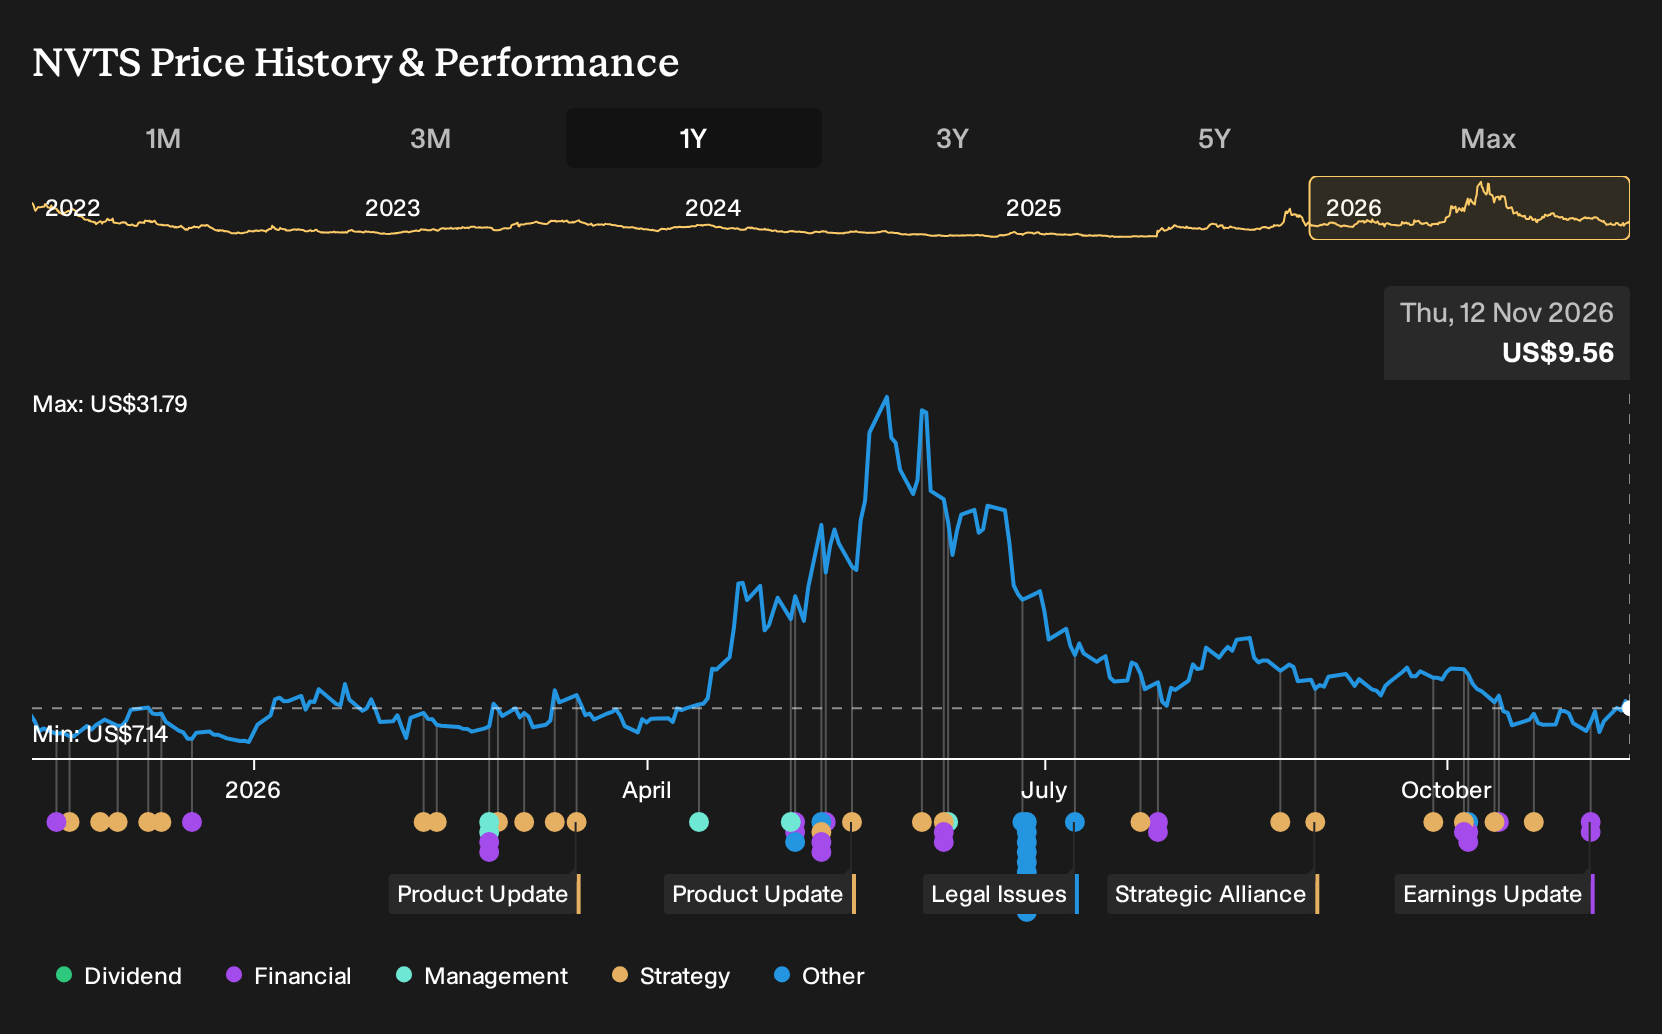
- Navitas Semiconductor reported third quarter 2026 sales of US$13.99 million with a net loss of US$37.11 million, and issued fourth quarter guidance that points to higher revenue and continued focus on high power products.
- The company simultaneously pursued an aggressive legal stance by filing a fresh patent infringement lawsuit against Renesas over GaN power devices, while projecting a greater contribution from high power revenue as mobile and low-end consumer sales shrink.
- Next, the focus will be on how this new Renesas lawsuit shapes Navitas Semiconductor's investment narrative as high power guidance tightens.
Navitas Semiconductor Investment Narrative Recap
To hold Navitas Semiconductor, you have to buy into the pivot toward high power GaN and SiC for AI infrastructure, grid and other demanding uses, even while the business is still loss making. The third quarter showed US$13.99 million in sales paired with a net loss of US$37.11 million, so the near term story is still about scaling, not profit.
The analyst consensus Narrative on Simply Wall St points to that high power transition as the key catalyst, and the latest guidance frames fourth quarter revenue as moving higher while mobile and low end consumer revenue falls away. The biggest operational risk right now sits in execution, plus legal and competitive pressure, if these new high power programs or ongoing lawsuits disrupt product availability or margins.
The fresh fourth quarter and 2026 outlook is the update that most directly ties into this earnings print and the new Renesas lawsuit. Management expects net revenue of about US$16 million in the fourth quarter, with guidance implying a greater share from high power products as the mobile and low end consumer portion shrinks toward zero after being a large majority last year.
That shift matters when you line it up against the earlier catalysts around data center and grid programs. If the book to bill ratio remains above one and backlog into mid 2027 converts into shipments, then those 800V AI rack designs and ultra high voltage SiC projects become the real test of whether Navitas Semiconductor can turn its broadened addressable market into more stable top line and eventually narrower losses despite heavier legal and R&D spend.
Navitas Semiconductor's current analyst narrative points to forecast revenue of US$161.6 million and expected earnings of US$32.3 million by 2029, built on an assumed 64.2% yearly revenue growth rate and an earnings swing of about US$345.4 million from earnings today of a US$313.1 million loss.
Uncover why Navitas Semiconductor's fair value indicates a 47% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view focuses less on legal risks and more on earnings pressure. The most bearish analysts were only pencilling in 2029 revenue of about US$123.6 million and earnings of US$24.8 million before this latest quarter and the new Renesas lawsuit. That creates a much tougher Navitas Semiconductor story, so it is worth exploring both narratives yourself.
Explore 2 other Navitas Semiconductor fair value estimates, including one that suggests it could be worth just $13.10!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Navitas Semiconductor research is our analysis highlighting 1 key reward and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Navitas Semiconductor. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Navitas Semiconductor's overall financial health at a glance.
Looking For More Investment Ideas Beyond Navitas Semiconductor?
If the Navitas Semiconductor story has sharpened your thinking about risk, growth and balance sheet strength, it can help to line it up against a wider watchlist built from clear starting points in the Simply Wall St Screener.
- For investors who care most about financial resilience and low leverage, start with a list of solid balance sheet and fundamentals (23 results) that can help you focus on sturdier opportunities when conditions get tougher.
- If capital preservation and a smoother ride matter more than chasing every rally, filter for a 29 resilient stocks with low risk scores that may better match a cautious approach.
- When you want to hunt for quality stories that are less crowded, scan a 20 high quality undiscovered gems that could widen your opportunity set beyond the usual tickers.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com