
Is WillScot Holdings (WSC) Undervalued Following Its Rating Upgrade And Raised Revenue Guidance?
WillScot Holdings (WSC) has moved into focus after a fresh analyst rating upgrade, along with raised 2026 revenue guidance and third quarter results that showed higher sales, revenue, and earnings per share.
Recent trading shows that WillScot Holdings has started to regain momentum, with an 11.21% 7 day share price return and a 14.75% 30 day share price return, even though the 90 day share price return declined 16.5% and the 3 year total shareholder return is down 47.81%. The fresh rating upgrade, raised 2026 revenue guidance and reaffirmed dividend, alongside a 16.54% 1 year total shareholder return, indicate that investors may be reassessing both growth potential and risk around the US$19.84 share price.
Scan beyond WillScot Holdings and see how other construction and capital goods plays are priced right now with our hand picked 32 high quality undervalued stocks list.
WillScot Holdings has just enjoyed a sharp short term rebound, yet the share price is still sitting well below its three year starting point. Investors may be weighing whether it makes more sense to step in at US$19.84 now or hold out for a cheaper entry as the valuation picture comes into focus next.
Most Popular Narrative: 21% Undervalued
Against a last close of $19.84, the analyst consensus Narrative on Simply Wall St points to a fair value of about $25.00. This implies a clear valuation gap that this framework ties to future cash flow and profitability forecasts rather than short term trading swings.
Growing modular pending orders, up in a 13% to 17% range year over year with a large and mega project pipeline that extends into 2027 and includes data centers, power generation and manufacturing, point to future leasing revenue that the market may not be fully pricing into WillScot Holdings yet.
Expansion of newer categories like climate controlled storage, where order books are up around 100% year over year and help offset pressure in traditional storage, supports a shift toward higher average rental rates and mix that can improve revenue quality and gross margins.
See why 5 investors see WillScot Holdings as 21% undervalued.
Result: Fair Value of $25 (UNDERVALUED)
Still, the bullish WillScot Holdings story can be knocked off course if portable storage weakness persists and if compressed EBITDA margins fail to recover as analysts expect.
Find out about the key risks to this WillScot Holdings narrative.
Another View: What P/S Says About WillScot Holdings
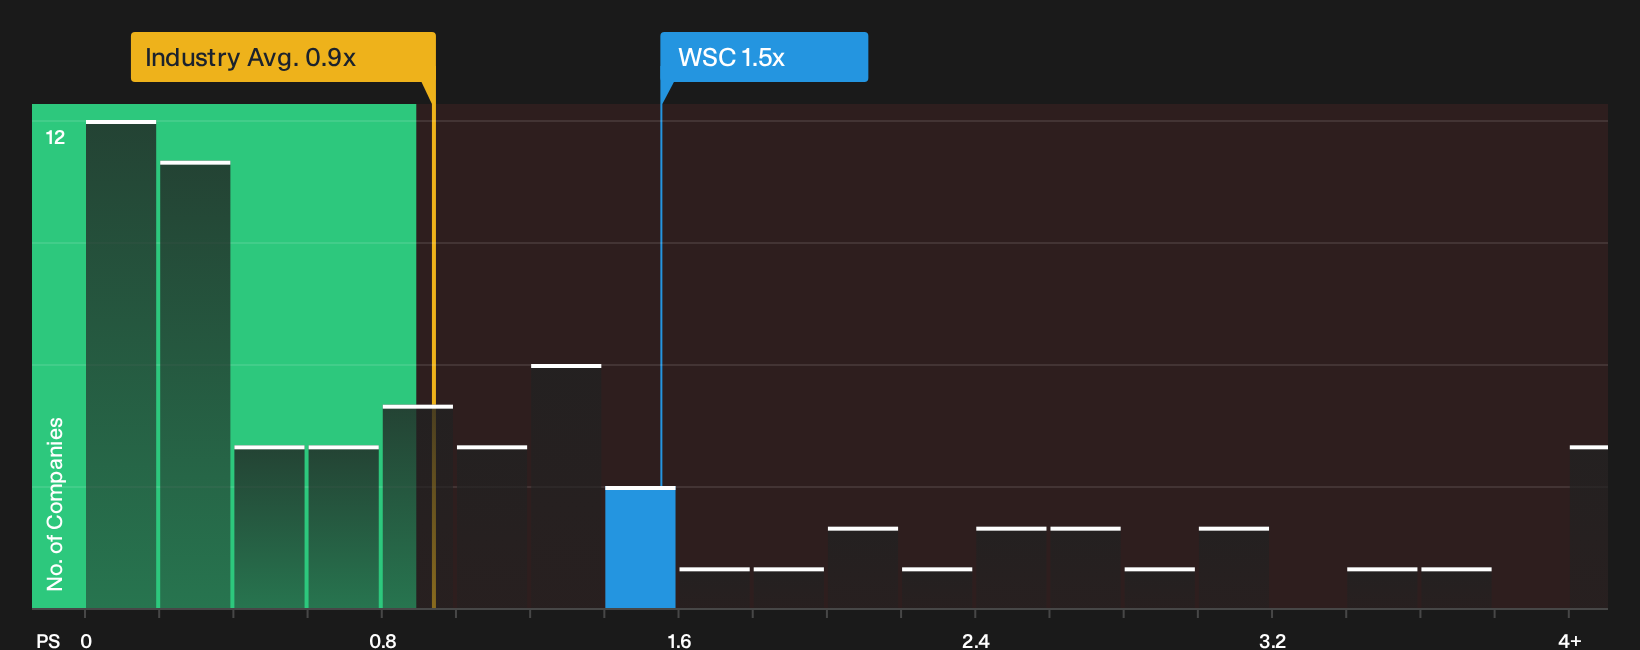
The cash flow work points to WillScot Holdings trading below an estimated future value. The simpler P/S yardstick tells a different story. WSC sits at roughly 1.5x sales, compared with about 1x for the wider US Construction group and 0.8x for peers, while the fair ratio is 2.4x. That gap suggests investors are already paying more than sector and peer averages today, even though the market could still move toward a higher sales multiple over time. The question is whether you see that premium to the sector as an opening or a risk if sentiment turns.
To see how the pricing stacks up in more detail across peers and the sector, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the WillScot Holdings story so far. Consider acting while sentiment is still resetting and weigh the balance of 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond WillScot Holdings?
Do not stop with WillScot Holdings. Put these tools to work so you can spot opportunities early, compare quality quickly, and avoid leaving better ideas on the table.
- Target potential mispricings by scanning a curated 32 high quality undervalued stocks list that filters for both quality fundamentals and attractive valuations.
- Strengthen your downside protection by focusing on a list of solid balance sheet and fundamentals (23 results) that can better handle shocks and funding pressure.
- Get ahead of the crowd by tracking a 20 high quality undiscovered gems that combines strong financials with limited current market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com