
Cinemark Holdings (CNK) Posts Stronger Earnings, Is The Stock Fully Valued?
Cinemark Holdings (CNK) just delivered third quarter earnings that showed higher revenue, net income, and earnings per share compared with a year earlier, coinciding with recent broker upgrades and a stronger analyst ranking.
Cinemark Holdings' latest earnings arrive as the stock trades at $41.46, after a strong run that includes a 76.20% year to date share price return and a 3 year total shareholder return of 194.02%. This suggests that momentum has been building as recent results and broker upgrades reshape how investors view both its growth potential and risk profile.
Scan how Cinemark Holdings compares with other momentum-driven entertainment and media plays by checking our curated list of 20 high quality undiscovered gems in a similar phase of renewed interest.
The question now is whether Cinemark Holdings’ sharp re-rating reflects a healthier, higher earning theatre business, or a swing in sentiment that has simply pushed the stock ahead of its fundamentals.
Most Popular Narrative: 1% Undervalued
Cinemark Holdings closed at $41.46 compared with a fair value of $41.82 in the analyst consensus Narrative on Simply Wall St, which builds off analysts’ earnings, revenue and discount rate assumptions rather than one person’s view. That small gap points to a stock where sentiment, forecasts and current pricing are closely aligned.
Accelerating consumer demand for out of home experiences, reflected in record box office periods and ongoing audience interest in theatrical releases through 2027 slates, can support higher admission revenue and operating leverage for Cinemark Holdings.
Continued expansion of premium formats such as XD, IMAX, ScreenX and D BOX, including newly announced ScreenX locations, can lift average ticket prices and concession spend per guest and support both revenue and net margin strength over time.
See why 9 investors see Cinemark Holdings as 1% undervalued.
The Narrative applies an 11.02% discount rate and a future P/E of 18.6x to reach that $41.82 estimate, using forecast revenue of $4.0b and projected earnings of $341.2m by 2029 as anchors. With Cinemark Holdings already trading within roughly 1% of that level, the implied upside is slim and places more weight on whether box office strength, premium formats and loyalty driven spending actually produce the margin and cash flow profile analysts have pencilled in.
Result: Fair Value of $41.82 (ABOUT RIGHT)
Still, Cinemark Holdings depends heavily on sustained box office strength, and rising fixed costs tied to premium formats and utilities could squeeze profitability if demand softens.
Find out about the key risks to this Cinemark Holdings narrative.
Another Angle On Cinemark Holdings’ Valuation
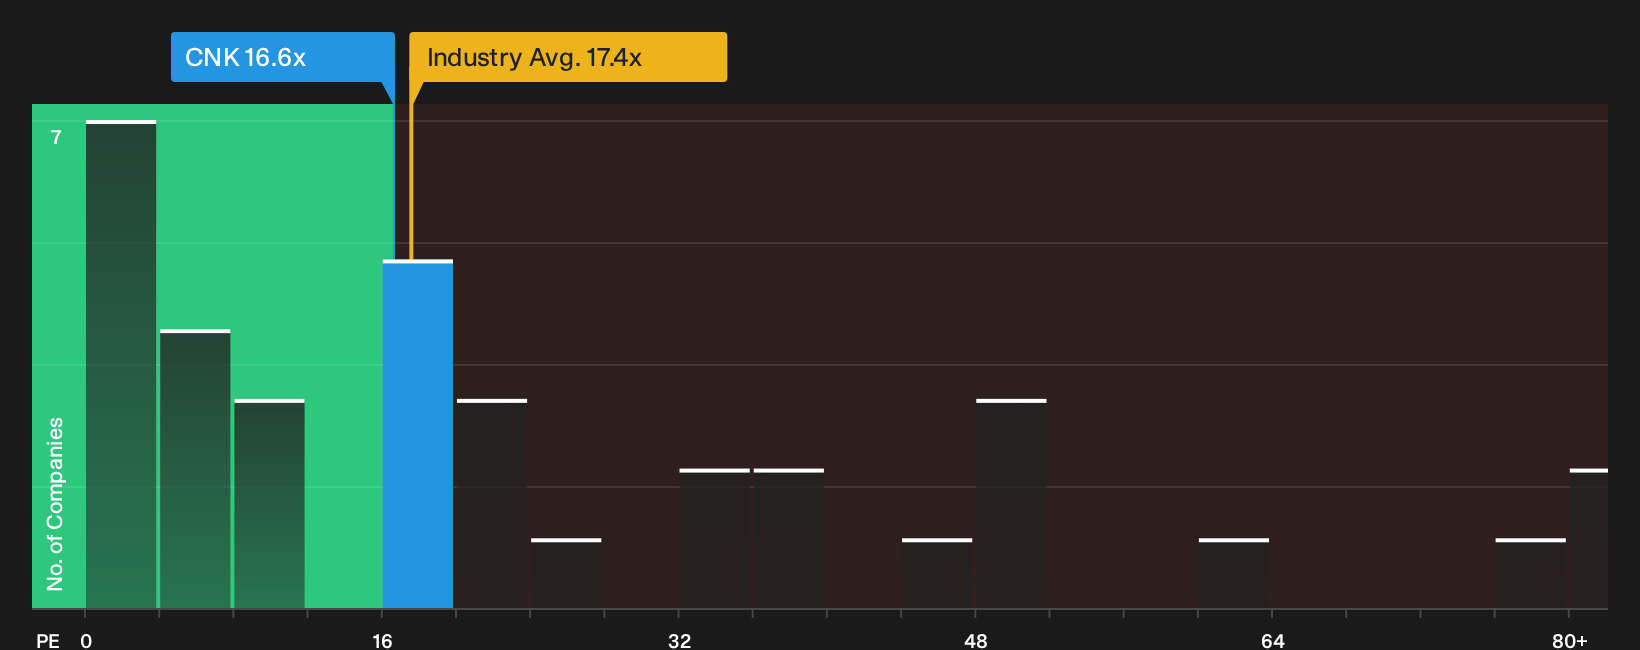
The earlier view framed Cinemark Holdings as roughly in line with its analyst fair value. A simple P/E comparison tells a slightly different story. CNK trades on 16.6x earnings, below the peer average of 23.6x, yet sits above its own fair ratio of 15.7x, which hints at some valuation stretch even if it looks cheaper than similar entertainment stocks.
That mix of relative cheapness versus peers and a premium to the fair ratio raises a practical question for investors: Is the market paying up a little too much for recent earnings strength, or is this the kind of premium that can persist if current profitability holds?
See what the numbers say about this price — find out in our valuation breakdown.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Cinemark Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Cinemark Holdings so far, with both concerns and bright spots in the latest data. Consider reviewing the details and pressure testing the story yourself with 3 key rewards and 1 important warning sign
Looking for more investment ideas beyond Cinemark Holdings?
Do not stop at Cinemark Holdings. Fresh opportunities keep appearing and a quick scan of other ideas can help you spot risk and reward combinations you might otherwise miss.
- Target steadier compounding by reviewing companies with consistent fundamentals through the 29 resilient stocks with low risk scores.
- Hunt for pricing mismatches by checking the 32 high quality undervalued stocks that match strong financial quality with more modest market expectations.
- Focus on balance sheet strength and resilient cash generation using our list of solid balance sheet and fundamentals (23 results) to see which businesses clear a higher quality bar.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com