
Does Return To Profitability Change The Bull Case For Air Products (APD)?
- Air Products and Chemicals reported fourth quarter 2026 sales of US$3,555.6m and net income of US$584.3m, with full year revenue of US$12,990.9m and a move from a net loss to net income of US$532.1m compared with the prior year.
- The shift from a full year loss to earnings per share of US$2.39 from continuing operations highlights how recent cost actions and portfolio changes are now flowing through to the income statement.
- The company’s sharp swing back to full year profitability may influence how investors view its longer term investment narrative.
Scan how Air Products and Chemicals’ return to profitability compares with peers by checking out the hand picked list of solid balance sheet and fundamentals (23 results) that also pair earnings power with resilient finances.
Air Products and Chemicals Investment Narrative Recap
To own Air Products and Chemicals, you need to be comfortable with a capital heavy industrial gases and energy transition story where multi decade projects and contracts take time to show through in earnings and cash. The analyst consensus Narrative on Simply Wall St leans on productivity gains and portfolio pruning. The latest return to full year profitability supports that idea, while the near term swing in earnings does not remove execution risk.
The key short term catalyst is how effectively new hydrogen, ammonia and electronics projects move from construction into steady operation without fresh cost surprises. The major risk remains heavy spending and high debt relative to current earnings, especially with a dividend that is not well covered by profit or free cash flow.
The full year 2026 result, with US$12,990.9m of sales and net income of US$532.1m after a prior year loss, gives a cleaner base to judge those big projects. Profitability from continuing operations at US$2.39 per share sets a new reference point for assessing whether future capex in the US$2.0b to US$2.5b range translates into better returns.
This earnings release also interacts directly with the earlier cost savings and portfolio actions highlighted in the analyst consensus Narrative on Simply Wall St. Delivery of about US$100m of targeted annual savings and the lower capex guidance now sits beside reported profits, so investors can track whether Air Products and Chemicals is turning its large industrial gas and clean energy backlog into durable cash generation, not just accounting earnings.
Air Products and Chemicals' current earnings sit at a loss of US$47.3m, while analysts project revenue growth of 7.7% per year and expect earnings to reach US$3.9b by 2029. This implies an earnings increase of about US$3.95b from today and would coincide with forecast revenues of US$15.7b in that same year.
Uncover why Air Products and Chemicals' fair value indicates a 9% potential upside to its current price, which could narrow quickly.
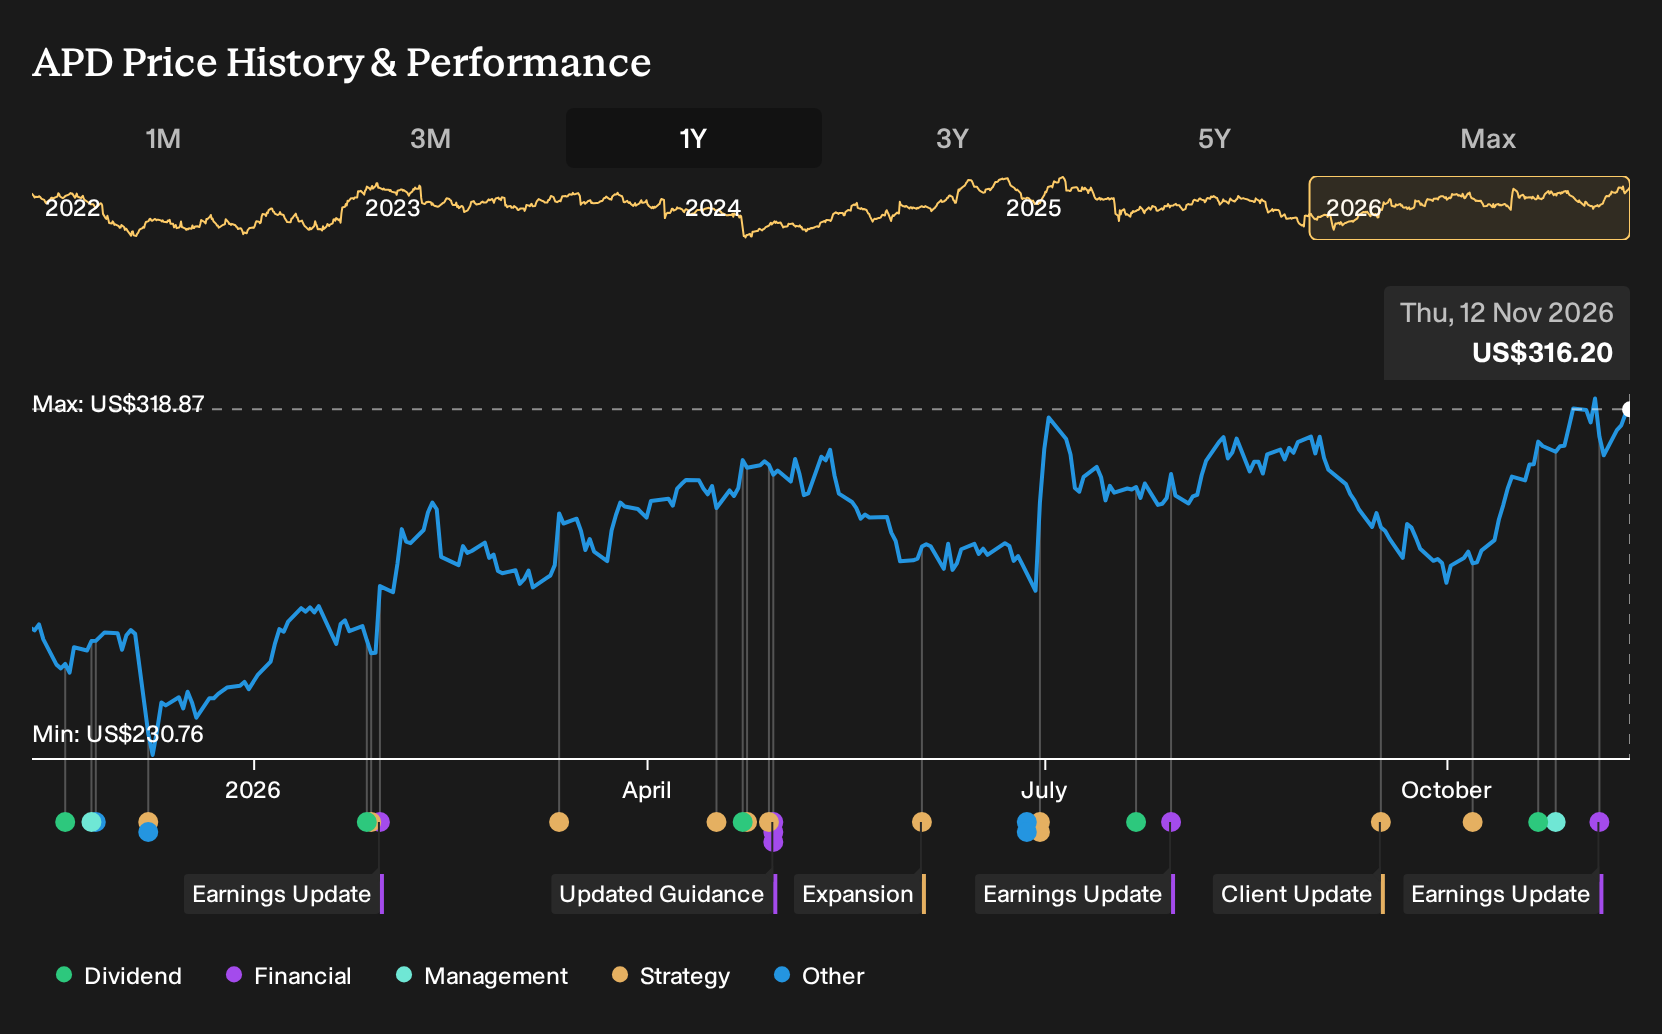
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community cluster between about US$344 and US$363 per share, so private investors are anchoring around a relatively tight band while still disagreeing on how much good news is already priced in. Air Products and Chemicals also carries heavy long term project commitments, so any fresh capex surge or project delay could change how that community reassesses the whole earnings story. Explore the different viewpoints before deciding where you sit.
Explore 2 other Air Products and Chemicals fair value estimates, including one that suggests as much as 15% upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own independent analysis.
- A great starting point for your Air Products and Chemicals research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Air Products and Chemicals. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Air Products and Chemicals' overall financial health at a glance.
Looking for more investment ideas beyond Air Products and Chemicals?
Once you have formed a view on Air Products and Chemicals, it can help to widen the lens and compare it with other businesses that match your preferred style of investing. The Simply Wall St Screener lets you move from a single stock story to a watchlist of candidates that share the balance sheet strength, value tilt, or income profile you care about most.
- If capital preservation is high on your list, start by checking companies screened for resilience and low risk through the 29 resilient stocks with low risk scores that filters for sturdier financial profiles.
- For investors who like the idea of paying less for quality, scan the 32 high quality undervalued stocks to see businesses where fundamentals and pricing look out of sync.
- If you want to pair income with staying power, review the 6 dividend fortresses that focuses on higher yielding payouts backed by stronger balance sheets.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com